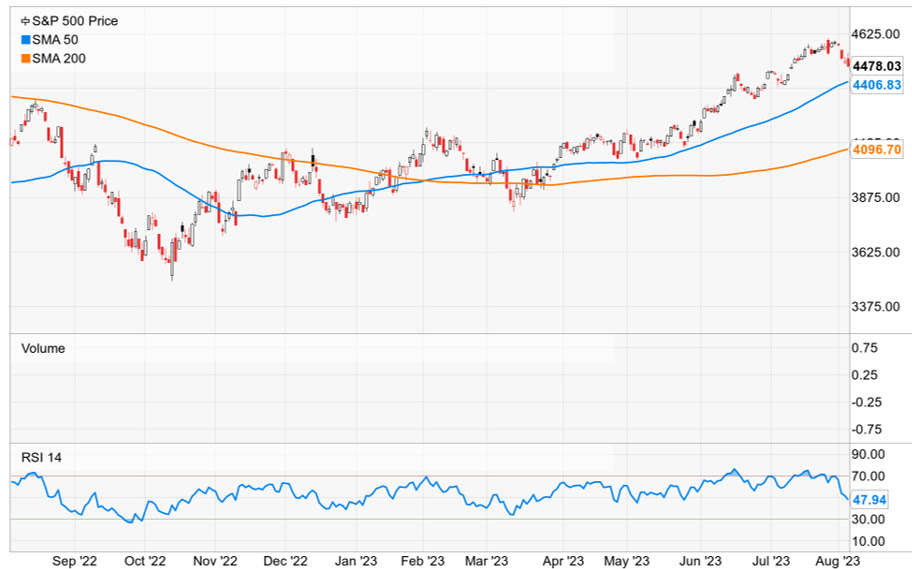
Global equity markets fell last week as investors digested a full dose of Q2 earnings reports, a packed economic calendar, more central bank policy decisions, and Fitch’s surprise downgrade of US sovereign
It was a busy week on Wall Street with announcements of monetary policy decisions from the Federal Reserve, European Central Bank, and the Bank of Japan, along with an active calendar of
US financial markets were mixed last week as investors continued to dissect 2nd quarter earnings results and economic data. The notion of a soft landing in the economy resonated with investors even
US markets rallied on the notion that the economy may be able to execute a soft landing as inflation wanes and employment continues to hold up. Inflation data reported during the week
The holiday-shortened week was discombobulated, to say the least. Trading desks on Wall Street were lightly staffed despite a full economic data calendar. The start of the third quarter ushered in equity
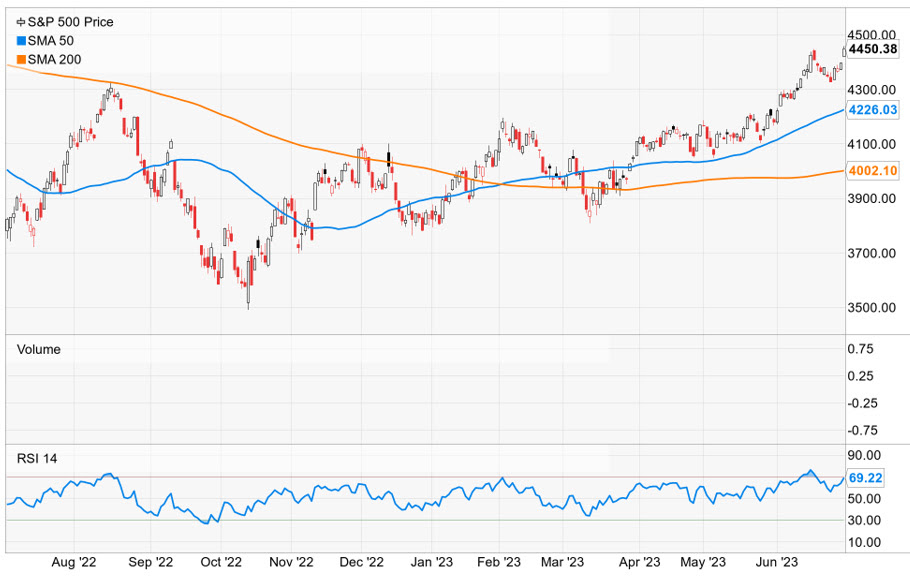
Markets ended the month of June in strong form. Better-than-expected economic data for the week showed a resilient economy and inflation moderating. Investors were dismissive of hawkish commentary from ECB President Lagarde
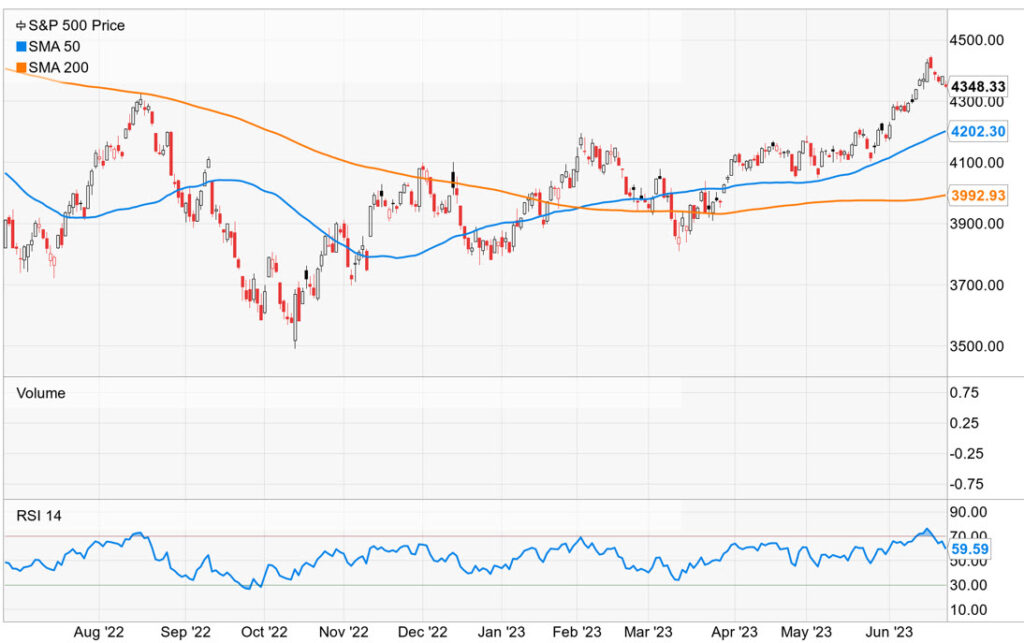
US equity markets tapped on the brakes with modest losses across the board. The notion that higher rates will further dampen global economic growth gave investors reason to take some profits. Economic
US equity markets continued to impress with another set of weekly gains. The mega-cap issues retook the lead, while small-cap issues lagged. Global central bank policy was top of mind for investors
The S&P 500 entered a new bull market, increasing 20% off the October lows. The move came with broader participation outside the mega-cap technology issues, responsible for most of the market’s performance
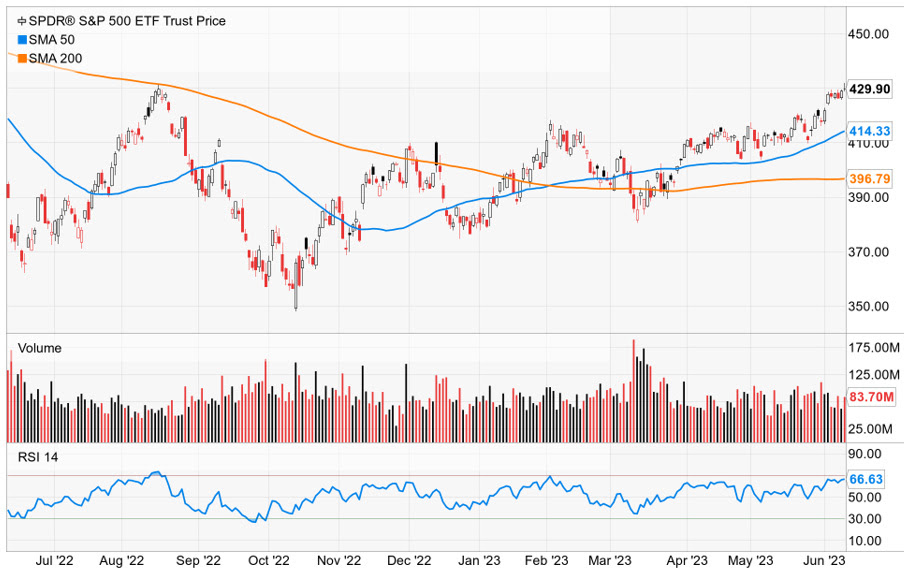
Investors enjoyed an excellent week of gains in US equity markets. Washington finally got a debt ceiling deal through Congress and onto President Biden’s desk. On the margin, it appears that the
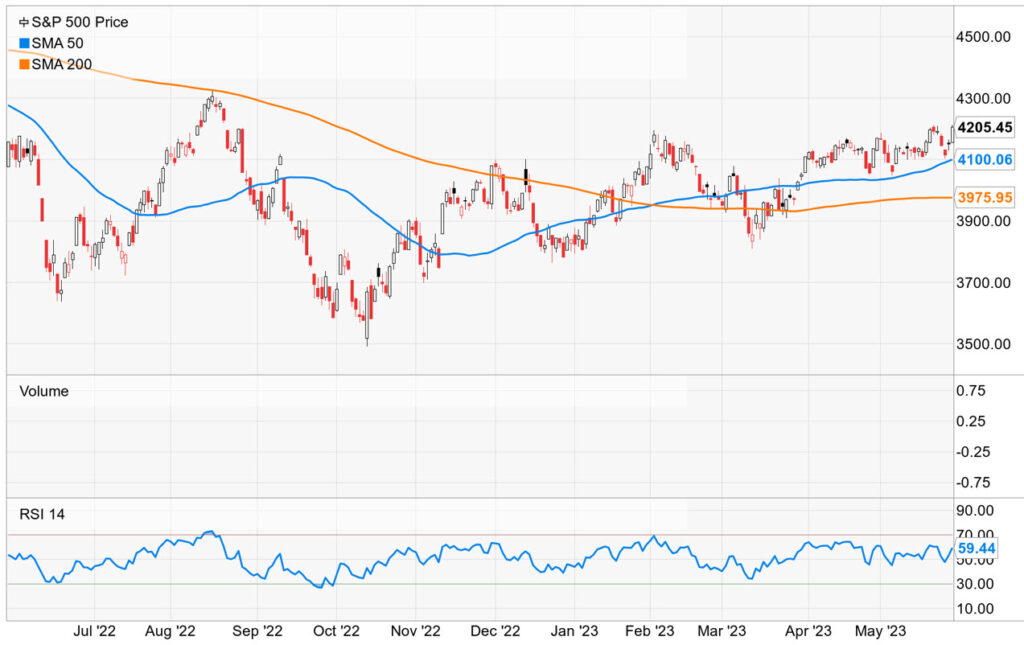
As investors awaited news from the debt ceiling negotiations, markets continued to ebb and flow. The S&P 500 continued to trade range-bound, oscillating between 4100 and 4200. Fed rhetoric continued to open
Investors were treated to a week of gains for US indices, while US Treasuries fell significantly across the curve. Early in the week, there was cautious optimism around debt ceiling negotiations as