Weekly Market Commentary

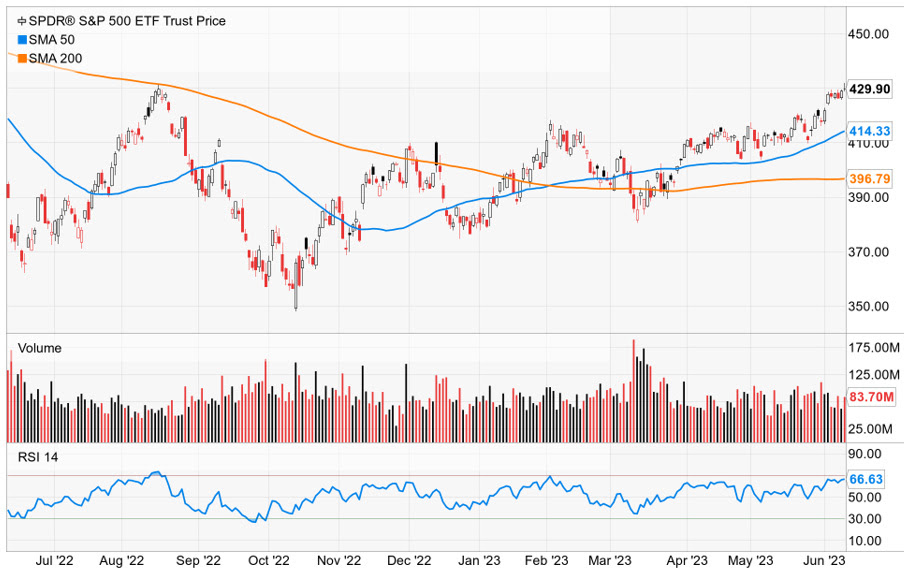
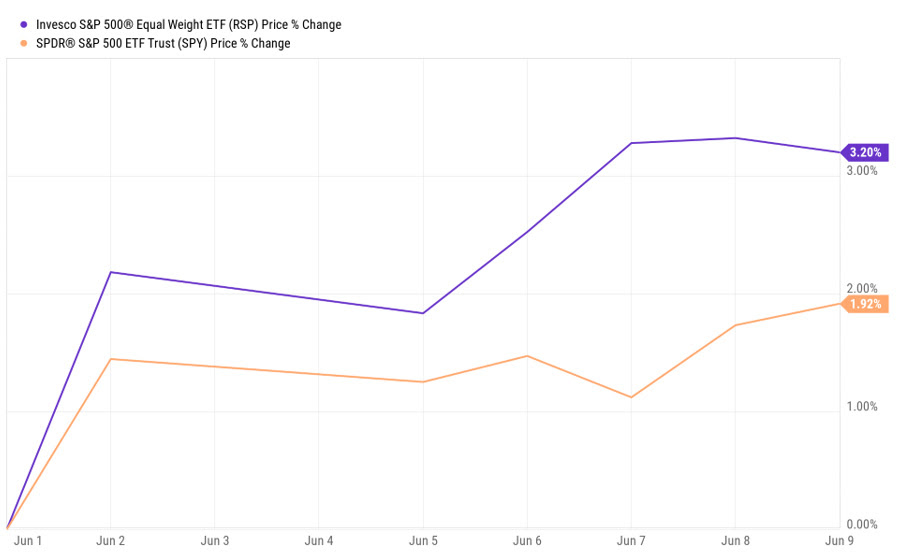
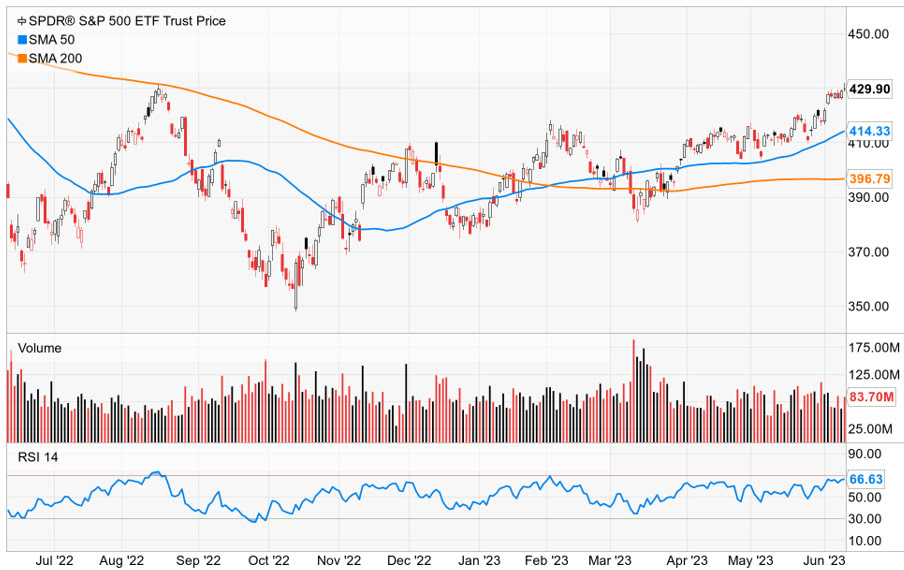
The S&P 500 entered a new bull market, increasing 20% off the October lows. The move came with broader participation outside the mega-cap technology issues, responsible for most of the market’s performance this year. Cyclical sectors such as the financials, consumer discretionary, and industrials posted solid gains for the week. Global Central Banks surprised investors with the Bank of Australia and Bank of Canada raising their respective policy rates by 25 basis points. The US Federal Reserve is expected to pause its rate hikes at the June meeting, which concludes on Wednesday, while the European Central Bank is widely expected to raise its rate by 25 basis points. Markets will likely be standoffish in front of the Fed’s FOMC and then react to Chairman J Powell’s assessment of the economy in his post-meeting Q&A.  Divergence in the opinions of Fed officials is likely and will foster uncertainly for the future path of Fed monetary policy. Currently, Fed Fund Futures’ price in a 29% probability of a 25 basis point hike at the June meeting and a 70% chance of a 25 basis point hike in July.
The week also saw former President Donald Trump charged with 38 criminal counts, including obstruction and the mishandling of classified documents, and the SEC announced that it is investigating cryptocurrency companies Binance and Coinbase.  Tesla had a great week with the announcement that the company would collaborate with GM on charging technology.

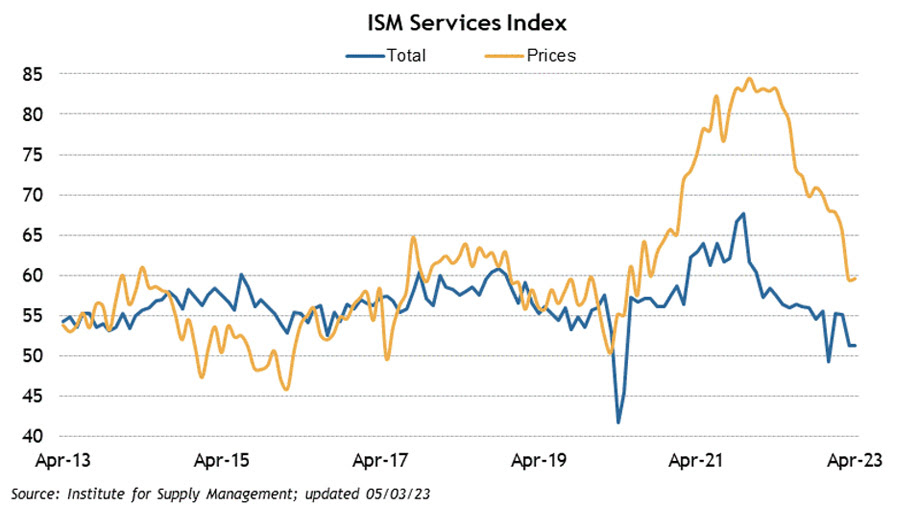
The Economic calendar was limited to a handful of data sets. Initial claims increased by 28k to 261k, the highest level since last November. Interestingly, Continued Claims fell by 37k to 1.757 million showing again a very resilient labor market. ISM Non-Manufacturing showed that the services side of the economy is still expanding but at a slower pace. The ISM figure came in at 50.3, down from the prior reading of 51.9. This week, we will get May Consumer Price Index data and Retail Sales figures.
The S&P 500 gained 0.4%, the Dow increased by 0.3%, the NASDAQ added 0.1%, and the Russell 2000 advanced by 1.9%. US Treasuries sold off across the curve. The 2-year yield increased by eleven basis points to 4.62%, while the 10-year yield added six basis points to 3.75%. The US Treasury will auction off 40 billion in 3 years on Monday. Oil prices decreased by 1.8% or $1.35 to $70.30. Goldman Sachs lowered their price target for the third time this year based on increased supply and softening global demand. Gold prices increased by $7.30 to $1977.10 an OZ, as Copper prices increased by $0.06 to $3.78 an Lb.
Investment advisory services offered through Foundations Investment Advisors, LLC (“FIA”), an SEC registered investment adviser. FIA’s Darren Leavitt authors this commentary which may include information and statistical data obtained from and/or prepared by third party sources that FIA deems reliable but in no way does FIA guarantee the accuracy or completeness.  All such third party information and statistical data contained herein is subject to change without notice.  Nothing herein constitutes legal, tax or investment advice or any recommendation that any security, portfolio of securities, or investment strategy is suitable for any specific person.  Personal investment advice can only be rendered after the engagement of FIA for services, execution of required documentation, including receipt of required disclosures.  All investments involve risk and past performance is no guarantee of future results. For registration information on FIA, please go to https://adviserinfo.sec.gov/ and search by our firm name or by our CRD #175083. Advisory services are only offered to clients or prospective clients where FIA and its representatives are properly licensed or exempted.
Share:

View the Latest Commentaries:

Weekly Market Commentary

It was a volatile week on Wall Street as traders assessed monetary policy decisions from several central banks, including the Federal Reserve.  The Fed did, as expected, raise its policy rate by 25 basis points to 3.75%-4.00%, but Fed Chairman Warsh’s very hawkish tone increased the likelihood of three more rate hikes starting later this year and in the first half of 2027.  The Fed Chair offered no forward guidance but did provide the dot plot from the other committee members.  The yield curve flattened on the announcement, with the front end of the curve selling off more than longer-duration Treasuries. Notably, the Bank of England kept its policy rate in place while the Bank of Japan raised its policy rate by 25 basis points.  A more dovish signal from the BOJ’s president sent the Yen lower.  Bottom line: the US economy is strong, employment looks stable, and inflation remains

Weekly Market Commentary

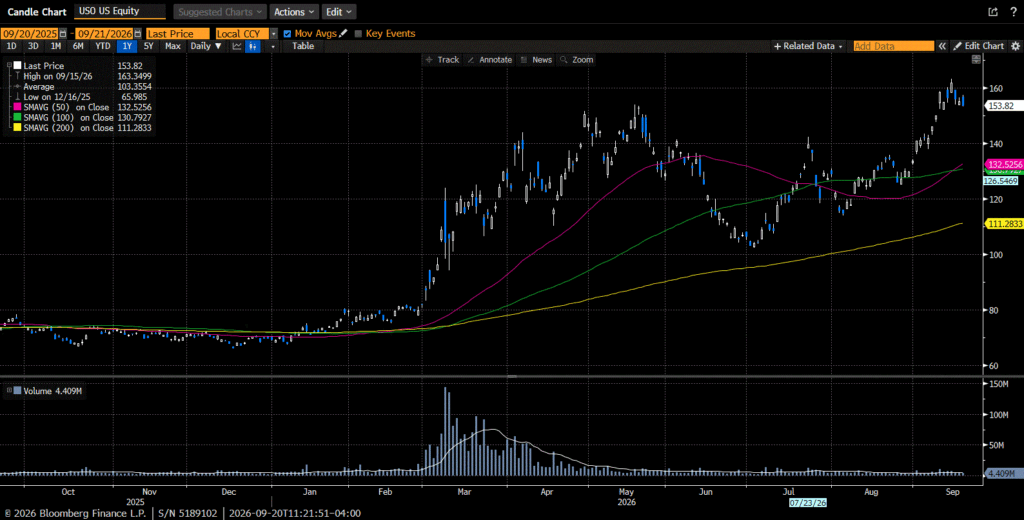
US equity markets fell in the holiday-shortened week as oil prices surpassed $100 a barrel, raising inflation concerns and pushing interest rates higher.  Additionally, elevated inflation data announced during the week increased the likelihood that the Federal Reserve would raise its policy rate by 25 basis points.  Several Gulf nations announced Friday that they would meet with Iranian officials this weekend to ease tensions, and on Sunday Tehran announced it would decide whether to open part of the Strait of Hormuz, but details of the opening were limited.  This followed Saudi Arabia’s announcement that it had shut down the oil pipeline used to circumvent the Strait. The S&P 500 fell 0.78%, the Dow gave back 1.56%, the NASDAQ declined 0.64%, and the Russell 2000 decreased by 2.39%.  US Treasuries suffered losses across the curve, with the front end of the curve getting hit hardest.  The 2-year yield increased by twenty-six

Weekly Market Commentary

Markets finished the week mixed as investors assessed the escalation of tensions between the US and Iran and recalibrated expectations of Federal Reserve monetary policy.  The week started with sharp declines after the US hit targets on an island in the Strait of Hormuz that were ready to launch mines into the strait.  Iran then countered with drone attacks on Jordan and the UAE.  On Saturday, there were reports that the US had hit three Iranian cargo ships after Iran fired ballistic missiles at two US Navy ships.  The news sent oil prices higher, which in turn raised inflation concerns.   Markets settled down mid-week after Dell reported a solid quarter and after dovish comments made by Fed Bank of New York President John Williams.  Markets moved higher on Thursday after Fed Governor Waller said he would be willing to hold rates steady if price pressures continue to ease and noted

Weekly Market Commentary

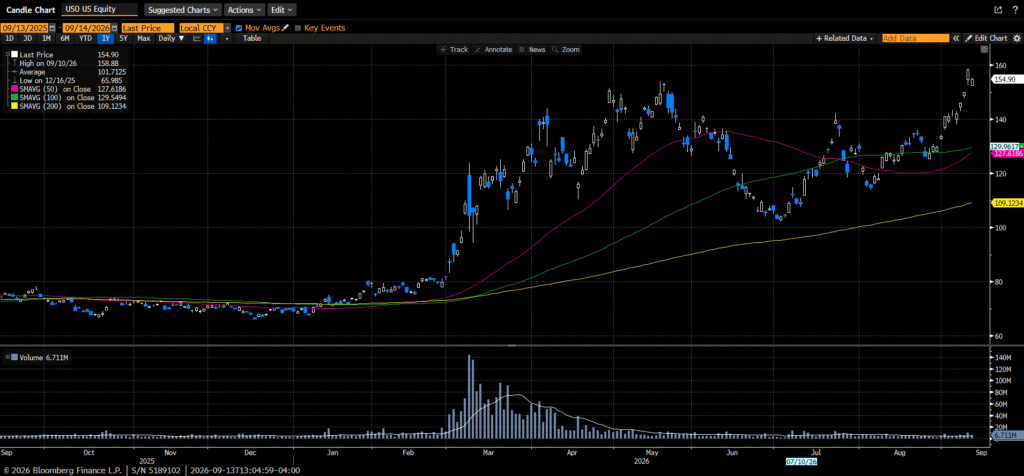
Markets ended the week mixed as investors assessed the implications of the US economic isolation of Iran, the fallout of increased tariffs on Canada, Nvidia Q2 earnings results, and the Fed Chairman’s speech at the Kansas City Federal Reserve’s Economic Symposium in Jackson Hole. Oh yeah, we were also treated to a slightly hotter print of the Fed’s preferred inflation measure, the PCE. On Monday, Treasury Secretary Bessent laid out a plan to isolate economic activity with Iran.  The plan, dubbed Economic D-day, promised economic punishment to any country doing business with Iran and suggested that, in the coming days, there will be announcements and actions taken against several entities that have worked alongside Iran to evade economic sanctions.  The US and Iran both said they would not return to the MOU signed in June, as negotiations have stalled.  Oil traded lower this week on reports that 10 million barrels