

Weekly Market Commentary

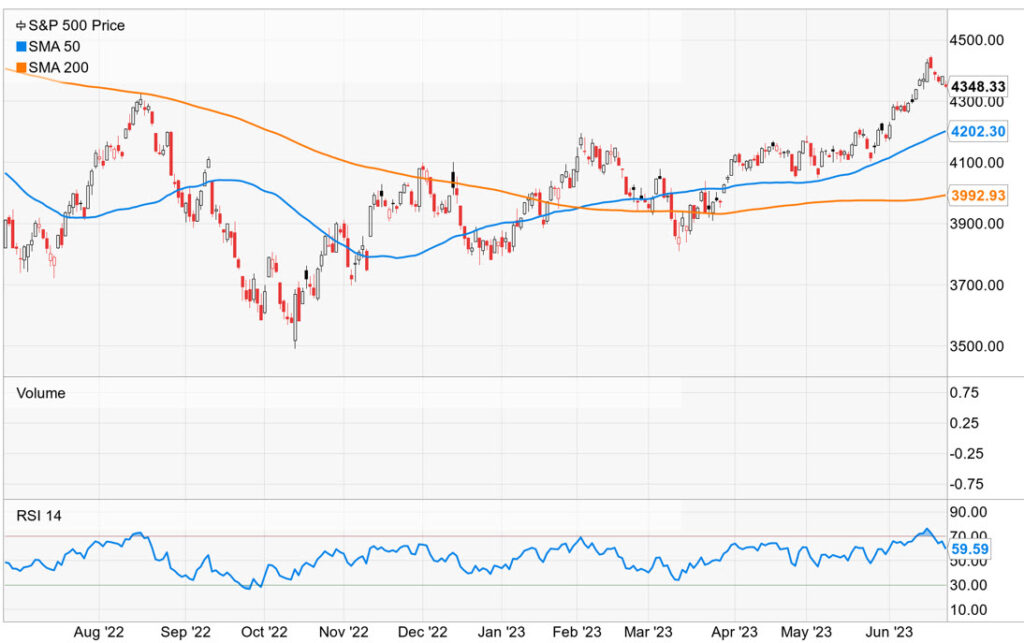
US equity markets tapped on the brakes with modest losses across the board.  The notion that higher rates will further dampen global economic growth gave investors reason to take some profits.  Economic data painted a resilient economy but continued to show signs of slowing.

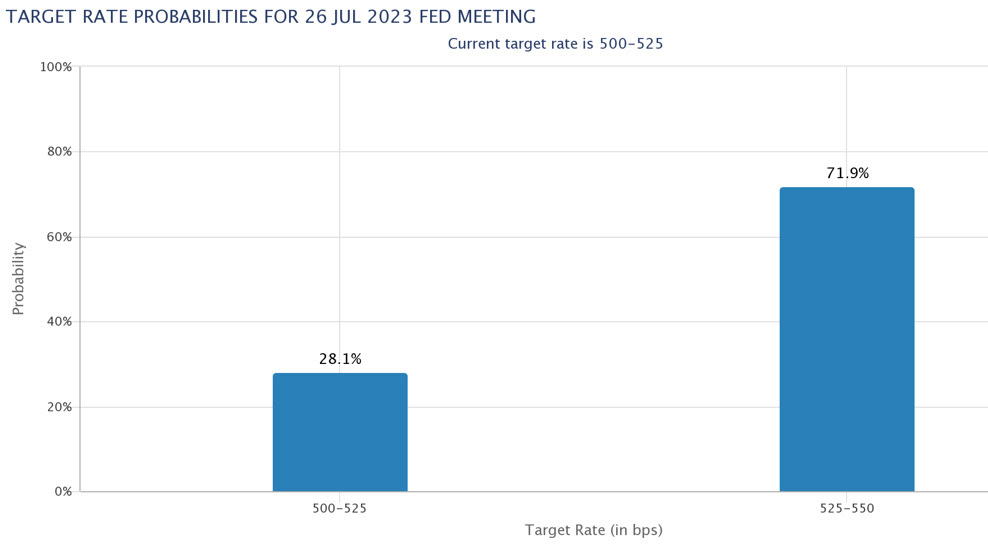
Global Central Banks’ rhetoric continued targeting elevated inflation and a vow to increase policy rates to lower prices.  Federal Reserve Jerome Powell was in front of the Congressional Financial Services Committee and the Senate Banking Committee for his semi-annual testimony, reiterating that two more rate hikes are likely despite the pause in June.  The Bank of England raised its policy rate by 50 basis points on the back of a hot UK CPI print.  The Norges Bank increased its policy rate by 50 basis points, while the Swiss National Bank upped its rate by 25 bps.
Of note, China’s central bank has been adding more stimulus to its economy by lowering key lending rates, but despite its efforts, investors appear to think more is needed. Chinese markets fell over the week. Indian Prime Minister Modi met with President Biden and Congress to strengthen relations between the two countries.  The Prime Minister also met with corporate executives from Amazon, GE, and Tesla to foster new investment within the Indian economy.

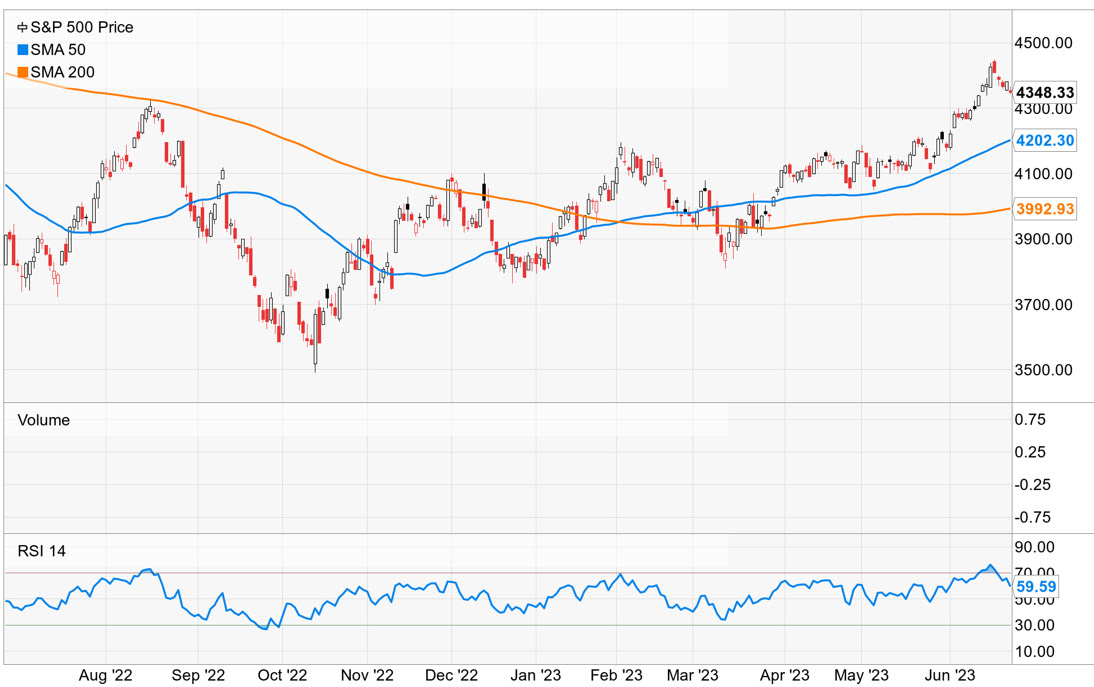
The S&P 500 lost 1.4%, the Dow fell 1.7%, the NASDAQ gave up 1.4%, and the Russell 2000 lagged, losing 2.9%.  US Treasuries lost on the front end of the curve, while longer-tenured issues had slight gains.  The 2-year yield increased by four basis points to 4.75%, as the 10-year yield fell by three basis points to 3.74%.  Despite a draw in weekly crude inventories, WTI prices continued to struggle.  Oil prices fell 3.8% or $2.74 to $69.18 a barrel. Gold prices fell by $40.40 to $1930.90 an Oz, while Copper prices regressed by $0.09 to close at $3.80 an Lb.
Economic data showed improvement in the housing sector.  MDA mortgage applications increased for the second week in a row, while Housing Starts and Permits surprised meaningfully to the upside.  Existing home sales fell by 20.4% year over year but came in better than expected at 4.30 million, highlighting the low supply of homes for sale. Initial Jobless claims continued to exceed 260k, coming in at 264K.  Continuing Claims fell from the prior week to 1.759 million.  Leading Economic indicators fell for the 14th consecutive time, coming in at -0.7 versus the previous reading of -0.8%.  Preliminary June IHS global PMIs showed manufacturing in contraction in the US, Eurozone, and Japan.  Services continue to show expansion but continue to moderate.

Investment advisory services offered through Foundations Investment Advisors, LLC (“FIA”), an SEC registered investment adviser. FIA’s Darren Leavitt authors this commentary which may include information and statistical data obtained from and/or prepared by third party sources that FIA deems reliable but in no way does FIA guarantee the accuracy or completeness.  All such third party information and statistical data contained herein is subject to change without notice.  Nothing herein constitutes legal, tax or investment advice or any recommendation that any security, portfolio of securities, or investment strategy is suitable for any specific person.  Personal investment advice can only be rendered after the engagement of FIA for services, execution of required documentation, including receipt of required disclosures.  All investments involve risk and past performance is no guarantee of future results. For registration information on FIA, please go to https://adviserinfo.sec.gov/ and search by our firm name or by our CRD #175083. Advisory services are only offered to clients or prospective clients where FIA and its representatives are properly licensed or exempted.
Share:

View the Latest Commentaries:

Weekly Market Commentary

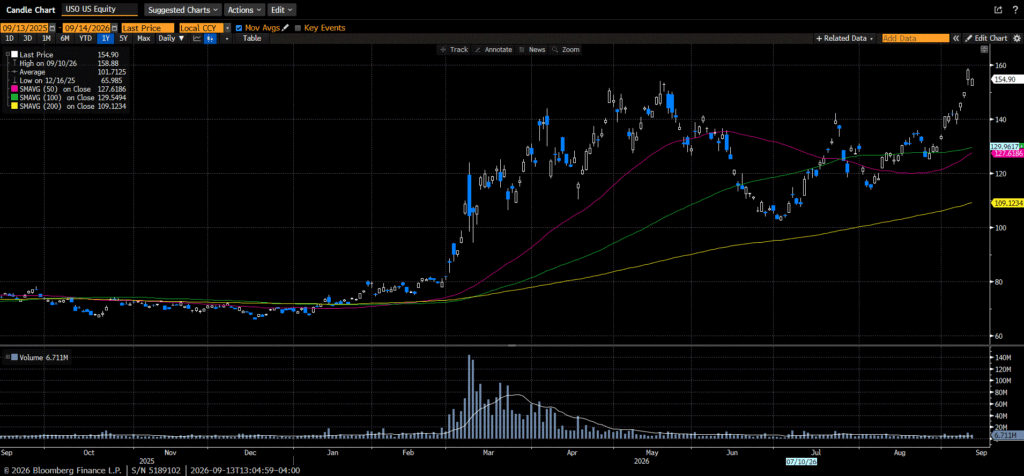
US equity markets fell in the holiday-shortened week as oil prices surpassed $100 a barrel, raising inflation concerns and pushing interest rates higher.  Additionally, elevated inflation data announced during the week increased the likelihood that the Federal Reserve would raise its policy rate by 25 basis points.  Several Gulf nations announced Friday that they would meet with Iranian officials this weekend to ease tensions, and on Sunday Tehran announced it would decide whether to open part of the Strait of Hormuz, but details of the opening were limited.  This followed Saudi Arabia’s announcement that it had shut down the oil pipeline used to circumvent the Strait. The S&P 500 fell 0.78%, the Dow gave back 1.56%, the NASDAQ declined 0.64%, and the Russell 2000 decreased by 2.39%.  US Treasuries suffered losses across the curve, with the front end of the curve getting hit hardest.  The 2-year yield increased by twenty-six

Weekly Market Commentary

Markets finished the week mixed as investors assessed the escalation of tensions between the US and Iran and recalibrated expectations of Federal Reserve monetary policy.  The week started with sharp declines after the US hit targets on an island in the Strait of Hormuz that were ready to launch mines into the strait.  Iran then countered with drone attacks on Jordan and the UAE.  On Saturday, there were reports that the US had hit three Iranian cargo ships after Iran fired ballistic missiles at two US Navy ships.  The news sent oil prices higher, which in turn raised inflation concerns.   Markets settled down mid-week after Dell reported a solid quarter and after dovish comments made by Fed Bank of New York President John Williams.  Markets moved higher on Thursday after Fed Governor Waller said he would be willing to hold rates steady if price pressures continue to ease and noted

Weekly Market Commentary

Markets ended the week mixed as investors assessed the implications of the US economic isolation of Iran, the fallout of increased tariffs on Canada, Nvidia Q2 earnings results, and the Fed Chairman’s speech at the Kansas City Federal Reserve’s Economic Symposium in Jackson Hole. Oh yeah, we were also treated to a slightly hotter print of the Fed’s preferred inflation measure, the PCE. On Monday, Treasury Secretary Bessent laid out a plan to isolate economic activity with Iran.  The plan, dubbed Economic D-day, promised economic punishment to any country doing business with Iran and suggested that, in the coming days, there will be announcements and actions taken against several entities that have worked alongside Iran to evade economic sanctions.  The US and Iran both said they would not return to the MOU signed in June, as negotiations have stalled.  Oil traded lower this week on reports that 10 million barrels

Weekly Market Commentary

US equity markets took a step back last week in what turned out to be a very busy week.  Increased yields on the long end of the curve prompted Treasury Secretary Scott Bessent to double buybacks of 10- to 30-year US Treasuries in an effort to temper the rise in rates.  The move was met with a rally in both bonds and stocks; however, it was short-lived, with much of the gains being given back within a day of the announcement.  A global debasement narrative has emerged as the US deficit topped $40 trillion.  The US Dollar sold off to levels not seen since May, while precious metals and Bitcoin prices soared.  Interestingly, the correlation between Gold and Bitcoin is the highest since Covid, following massive liquidity injections by global governments.  It’s notable that several other developed markets are facing similar pressure on their sovereign debt, including Japan, the UK,

