

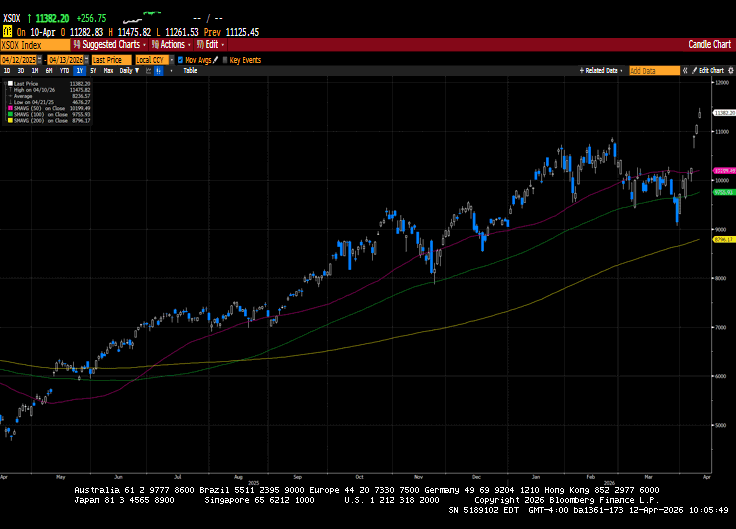
Global markets rose for a second week as the US and Iran agreed to a two-week ceasefire. The two sides met in Pakistan on Saturday to negotiate an end to the war, but talks ended without a resolution. The fragile ceasefire will be tested on Monday as markets reopen, with it likely that we see higher oil prices and a stronger US Dollar. Passage through the Strait of Hormuz continues to be at a standstill. However, there were reports over the weekend that US warships had mine-swept a path through the Strait that could lead to escorted passage. Markets have and will continue to be headline-driven. First-quarter earnings will begin this week, and it’s likely we’ll see tempered guidance from corporate management teams. Increased uncertainty about energy costs, tariffs, and consumer health may keep solid results from being rewarded. That said, solid monthly results from Taiwan Semiconductor helped push the Philadelphia Semiconductor index higher by 13.5%. Communication Services and the Consumer Discretionary sectors led market gains last week, with Information Technology also performing strongly. Software as a sub-index within Information Technology continued to struggle. The Energy sector was the worst-performing sector for the week, declining 4.1% as crude prices tumbled by over 13%.

The S&P 500 gained 3.6%, the Dow rose by 3%, the NASDAQ increased by 4.7%, and the Russell 2000 added 4%. International markets also had a great week, with Japan’s Nikkei rising by 7.2%, South Korea increasing by 9%, and the European Stoxx 600 rising by 3.5%. US Treasury yields fell across the curve. The 2-year yield fell by three basis points to 3.80%, while the 10-year yield declined by three basis points to close the week at 4.32%. The announcement of a two-week ceasefire sent oil prices tumbling. West Texas Intermediate crude prices fell by 13.29% or $14.93 to close at $96.55 a barrel. Gold prices advanced by 2.3% to close the week at $4,787.30 per ounce. Silver prices jumped by $3.74 or 5.1% to $76.48 per ounce. Copper prices surged by 5.3% to $5.88 per Lb. Bitcoin’s price increased by 8.1% to $72,900. The US Dollar index fell by 1.5% to 98.66.

&P 500 4/10/2026
This week’s economic calendar showcased global inflation data. In the US, the Producer Price Index increased by 0.4% in February, in line with the street’s expectation. The headline figure increased by 2.8% on a year-over-year basis, flat from the January reading. Core PPI also increased by 0.4% but was slightly higher than the 0.3% consensus estimate. The year-over-year figure declined to 3% from 3.1% posted in January. Headline March Consumer Price Index increased by 0.9%, well above the consensus of 0.7%. On a year-on-year basis, the CPI rose by 3.3%, up from 2.4% in February. The significant jump was attributed to a 10.9% increase in energy prices in March. Core CPI, which excludes food and energy, increased by 0.2%, less than the 0.3% consensus. Core CPI increased by 2.6% year-over-year, up from 2.5% in February. The increases in the CPI were concentrated in energy, but the question is whether this increase will bleed into other prices in the coming months, and the answer is likely yes. Personal Income fell by 0.1%, while Personal Spending came in slightly below expectations at 0.5%. ISM Services remained in expansion but is losing momentum. The reading came in at 54, down from the previous reading of 56.1. The third look at 4th-quarter GDP showed another downward revision to 0.5% growth. Again, much of this lost growth in GDP can be attributed to the government shutdown. Initial Claims increased by 16k to 219k, while Continuing Claims fell by 38k to 1794k. Finally, a preliminary look at the University of Michigan’s Consumer Sentiment for April fell to 47.6 from 53.3 in March.

Investment advisory services offered through Foundations Investment Advisors, LLC (“FIA”), an SEC registered investment adviser. FIA’s Darren Leavitt authors this commentary which may include information and statistical data obtained from and/or prepared by third party sources that FIA deems reliable but in no way does FIA guarantee the accuracy or completeness. All such third party information and statistical data contained herein is subject to change without notice. Nothing herein constitutes legal, tax or investment advice or any recommendation that any security, portfolio of securities, or investment strategy is suitable for any specific person. Personal investment advice can only be rendered after the engagement of FIA for services, execution of required documentation, including receipt of required disclosures. All investments involve risk and past performance is no guarantee of future results. For registration information on FIA, please go to https://adviserinfo.sec.gov/ and search by our firm name or by our CRD #175083. Advisory services are only offered to clients or prospective clients where FIA and its representatives are properly licensed or exempted.



