

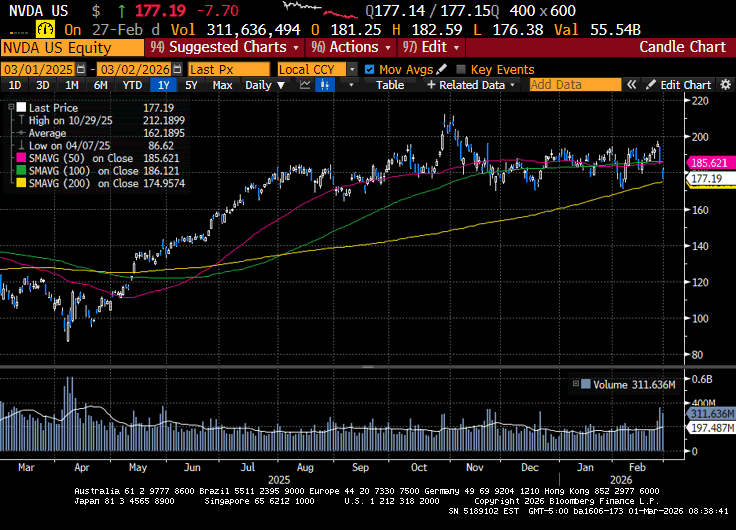
US equity markets regressed as several themes that have propelled the market higher over the last couple of years have had to be reassessed. Return on investment from AI capex, a Federal Reserve on hold, tariff uncertainty, and increased geopolitical tensions have investors recalibrating their market expectations.
Return on investment (ROI) on capital expenditures related to AI has been a recurring question mark for investors. Some problems in private credit have heightened concerns about the debt financing of AI initiatives. Nvidia’s 4th-quarter earnings were fantastic, but despite better-than-expected results and guidance, the company’s shares got hammered. “Sell the news” has been prevalent during this earnings season, especially with mega-cap technology companies. A clear rotation out of mega-caps and into other parts of the market occurred throughout February. Trades to value from growth have also been a prominent trend.

Recent economic data appears to be pushing out the timeline for a rate cut by the Federal Reserve. Hotter-than-expected inflation readings, along with a resilient labor market, have several Fed officials pushing back against the idea of a rate cut. Coming into the year, the market expected two rate cuts, which was considered a tailwind for markets. Currently, the market is expecting a rate cut in July, but the likelihood of this cut has diminished throughout February.
Companies are also considering their options in the current tariff environment. What does the recent Supreme Court ruling against the tariffs mean for businesses, and do Trump’s countermeasures delay business decisions, dampening corporate activity?
Saturday morning, the US and Israel attacked Iran, killing several key government officials, including the supreme leader. President Trump called for regime change, and it appears this conflict will not be measured in days but will likely last months, if not longer. There will be a bid for safe-haven assets once the markets open, and we saw signs of this last week with US Treasuries and gold trading higher. Oil has traded higher over the last couple of months amid heightened tensions between the US and Iran, but the closure of the Strait of Hormuz will have profound consequences for energy markets and global trade.
The S&P 500 lost 0.44%, the Dow shed 1.3%, the NASDAQ fell 0.95%, and the Russell 2000 declined by 1.18%. The NASDAQ lost 3.33% in February, while the Russell outperformed with a gain of 0.81%. As I mentioned earlier, US Treasuries were well bid last week, with the 2-year yield declining by ten basis points to 3.38%- the lowest level since August of 2022. The 10-year yield fell by thirteen basis points to 3.96%. For the month, the 10-year yield fell by twenty-eight basis points, while the 2-year yield declined by fifteen basis points. Oil prices increased by $0.57 to $67.06 per barrel. With the Strait of Hormuz closed, it is likely we will see an immediate $5 to $7 increase in oil prices when the market opens, and some have called for oil to trade above $100 a barrel if the Strait is closed for a prolonged period. OPEC on Sunday announced that it would increase production, but I am not sure how this will impact prices if the primary shipping lane is closed. Gold prices increased by 3.3% to $5,248.20 per ounce. Silver prices jumped 12.6% to $92.68 per ounce. Copper prices traded twenty-two cents higher at $6.06 per Lb. Bitcoin’s price fell 2% to $66,500. The US Dollar index fell by 0.2% to 97.60.

S&P 500 2/27/2026
The Producer Price Index came in hotter than expected. The headline reading for January increased by 0.5% versus the consensus estimate of 0.3%. The reading was up 3% year over year, up from 2.9% in December. The Core reading rose 0.8%, well above the consensus estimate of 0.3%, and 3.6% year over year, up from 3.3% in December. Interestingly, the increase in producer prices did very little to curb the bid into Treasuries but did push out rate-cut expectations. Consumer Confidence in February increased to 91.2 from 89 in January. Initial claims increased by 4k to 212k, while Continuing Claims fell by 31k to 1833k.

Investment advisory services offered through Foundations Investment Advisors, LLC (“FIA”), an SEC registered investment adviser. FIA’s Darren Leavitt authors this commentary which may include information and statistical data obtained from and/or prepared by third party sources that FIA deems reliable but in no way does FIA guarantee the accuracy or completeness. All such third party information and statistical data contained herein is subject to change without notice. Nothing herein constitutes legal, tax or investment advice or any recommendation that any security, portfolio of securities, or investment strategy is suitable for any specific person. Personal investment advice can only be rendered after the engagement of FIA for services, execution of required documentation, including receipt of required disclosures. All investments involve risk and past performance is no guarantee of future results. For registration information on FIA, please go to https://adviserinfo.sec.gov/ and search by our firm name or by our CRD #175083. Advisory services are only offered to clients or prospective clients where FIA and its representatives are properly licensed or exempted.



