

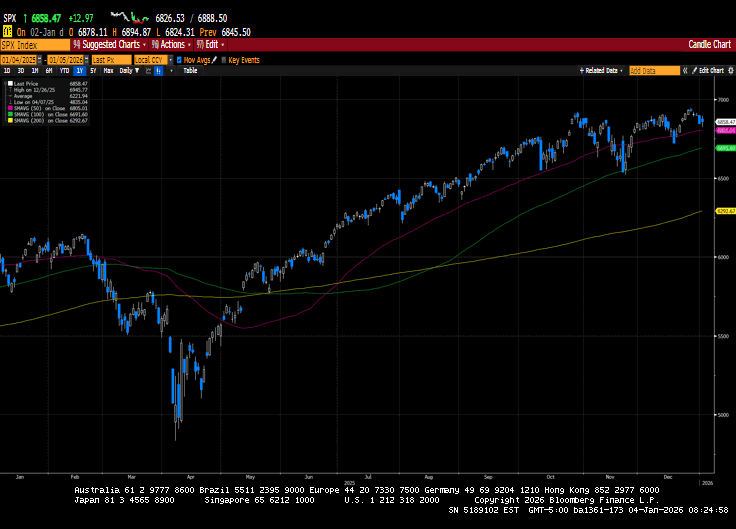
US markets ended the New Year holiday-shortened week with losses. Mega-cap Technology issues sold off on low volume, as did Financial and Consumer Discretionary sectors. That said, the S&P 500 posted its third straight year of double-digit gains as investors endured a wild ride in 2025. Many of the same themes that influenced markets in 2025 persist as we enter 2026. Geopolitical disruption was a central theme in 2025. As I write, the US has catalyzed a regime change in Venezuela by removing Maduro and declaring that it will run the country until a new government can be formed. Never a dull moment! Tensions with Iran are flaring up, and the Ukrainian and Russian war continues without a clear path to peace. Inflation declined in the US but remains well above the Federal Reserve’s mandate, and some fear it will reaccelerate in 2026 as the full effects of tariffs and increased fiscal spending feed through to prices. Markets experienced substantial tariff increases in 2025 and await a Supreme Court ruling on whether Trump’s unilateral tariffs are lawful. A verdict is expected within the next couple of months and will undoubtedly have a significant impact on markets. The Federal Reserve cut rates three times in 2025, and markets expect it to cut rates twice more in 2026. The cuts were driven by concerns about the Labor market, with fewer jobs being created and the unemployment rate rising to 4.6%. The Federal Reserve’s full-employment mandate took precedence over inflation in late 2025. In 2026, Artificial Intelligence will continue to drive several narratives, and one will be its effects on labor in the coming years and decades. Jobs lost to technological advances have occurred throughout history. I believe AI and its impact on employment will become a significant political debate heading into this year’s midterms. AI capital expenditure concerns were a recurring theme in 2025, and investors are likely to be even more skeptical about spending if the return on investment is further pushed out.
We remain constructive on the markets for several reasons. First, corporate earnings are expected to be even more robust than in 2025. Fourth quarter earnings start in earnest in a couple of weeks. Second, even if we receive only one rate cut, it occurs when the economy is growing rather than receding, which has always been positive for market returns. Third, AI capital expenditure, the build-out of energy infrastructure, and loose fiscal policy will drive corporate activity. There are several concerns as well. Market valuations, the circular nature of much of this AI capital expenditure, potential delays in AI buildouts, inflation, labor market pressures, geopolitical pressures, and Federal Reserve independence. Buckle up; 2026 is likely to be a wild ride as well.

Returns were generally positive across most asset classes in 2025. US, international developed, and emerging equity markets all finished the year higher. Fixed-income markets also enjoyed gains.
The S&P 500’s total return for 2025 was 17.72%, the Dow was up 14.70%, the NASDAQ increased by 20.89%, and the Russell 2000 was higher by 12.66%. Developed International markets returned 32.81%, while Emerging Markets gained 34.3%. The Communication Services sector led sector gains, returning 32.41%, followed by the Information Technology sector, which was up 23.31%. The Real Estate sector declined 0.35%, making it the only sector to post a negative return.
US Treasuries gained across the yield curve in 2025, except for the 30-year, which ended the year at 4.84%, up five basis points. The 2-year yield declined by seventy-seven basis points, closing at 3.48%, while the 10-year yield shed forty basis points to close the year at 4.17%.

Annual Asset Class Returns
Oil prices fell by 19.8%, the worst performance since 2020. West Texas Intermediate prices fell by $14.23 to close the year at $57.62 a barrel. Gold prices increased by 65% or $1,710.20 to close at $4,342.30, while silver prices increased by a whopping 148%. Copper prices increased by 41% to close the year at $5.68 per Lb., just off record highs hit a couple of weeks ago. Bitcoin’s price fell by 5.5% for the year, closing at $88,000. The US Dollar index fell by 9.40% to 98.38, marking its largest decline in nearly a decade.

Investment advisory services offered through Foundations Investment Advisors, LLC (“FIA”), an SEC registered investment adviser. FIA’s Darren Leavitt authors this commentary which may include information and statistical data obtained from and/or prepared by third party sources that FIA deems reliable but in no way does FIA guarantee the accuracy or completeness. All such third party information and statistical data contained herein is subject to change without notice. Nothing herein constitutes legal, tax or investment advice or any recommendation that any security, portfolio of securities, or investment strategy is suitable for any specific person. Personal investment advice can only be rendered after the engagement of FIA for services, execution of required documentation, including receipt of required disclosures. All investments involve risk and past performance is no guarantee of future results. For registration information on FIA, please go to https://adviserinfo.sec.gov/ and search by our firm name or by our CRD #175083. Advisory services are only offered to clients or prospective clients where FIA and its representatives are properly licensed or exempted.



