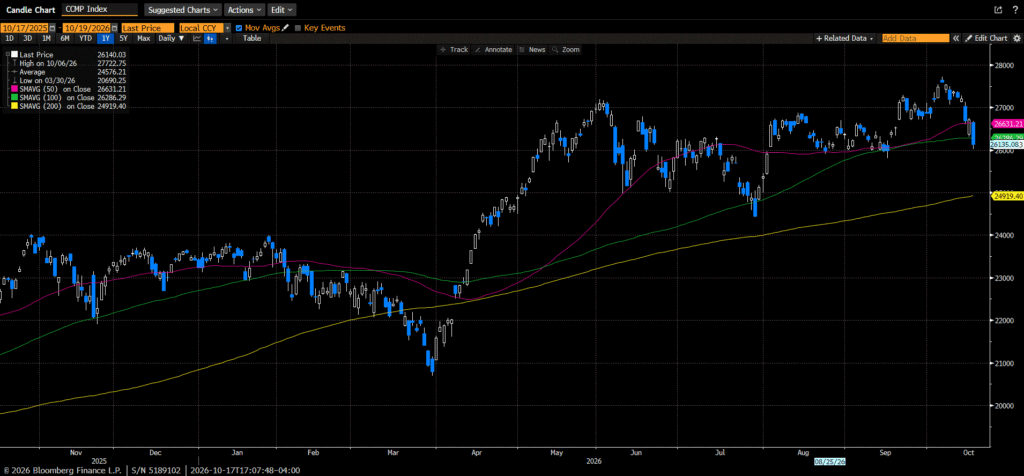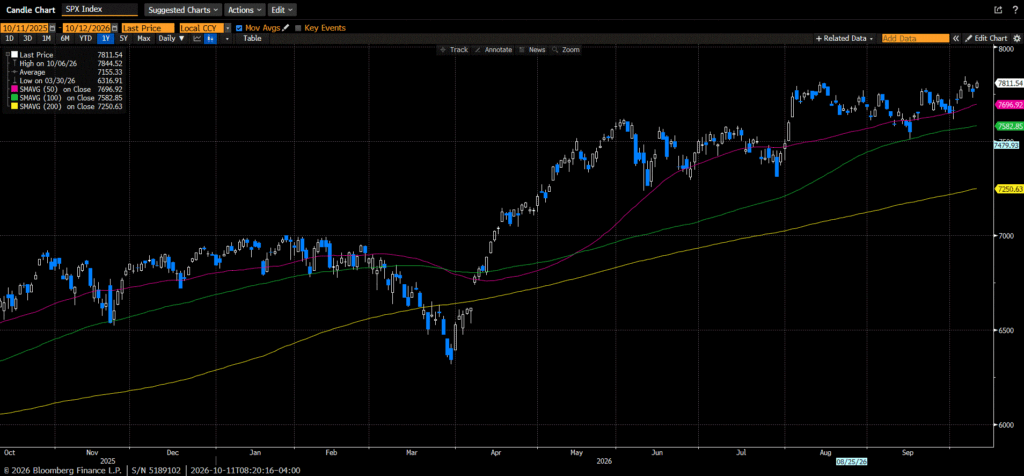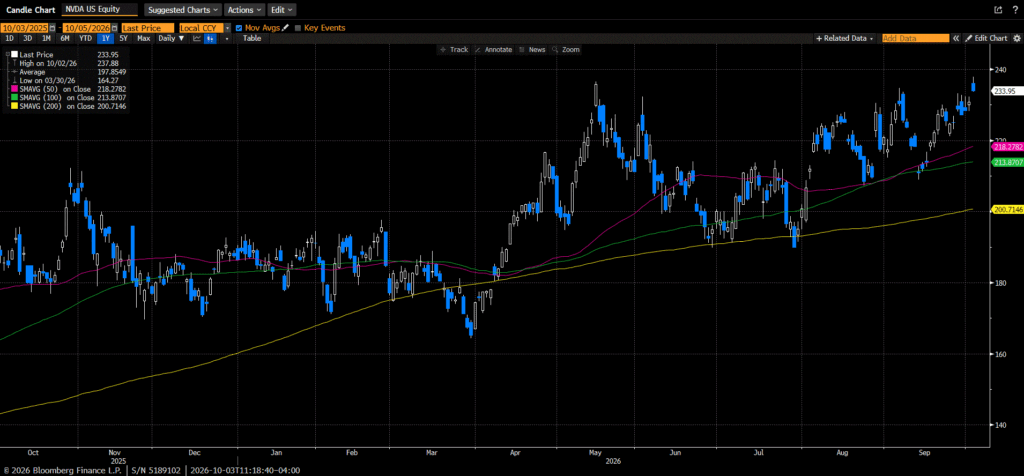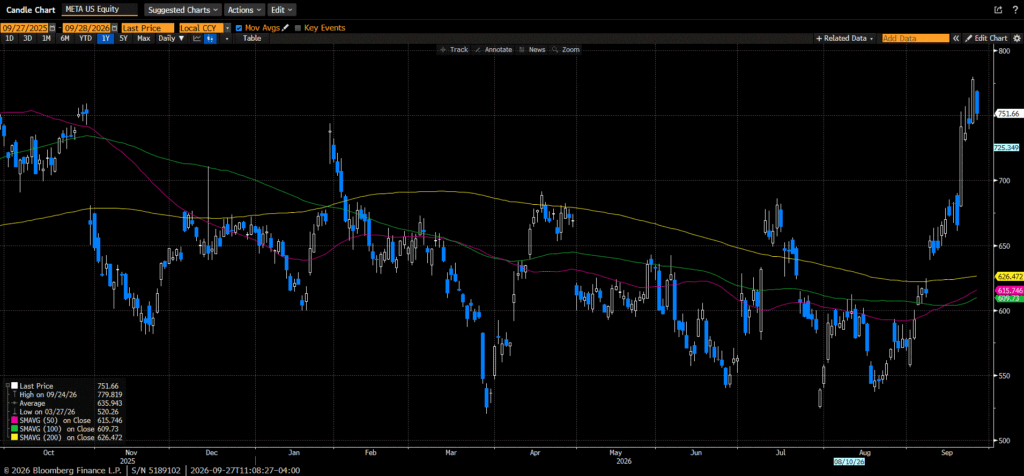
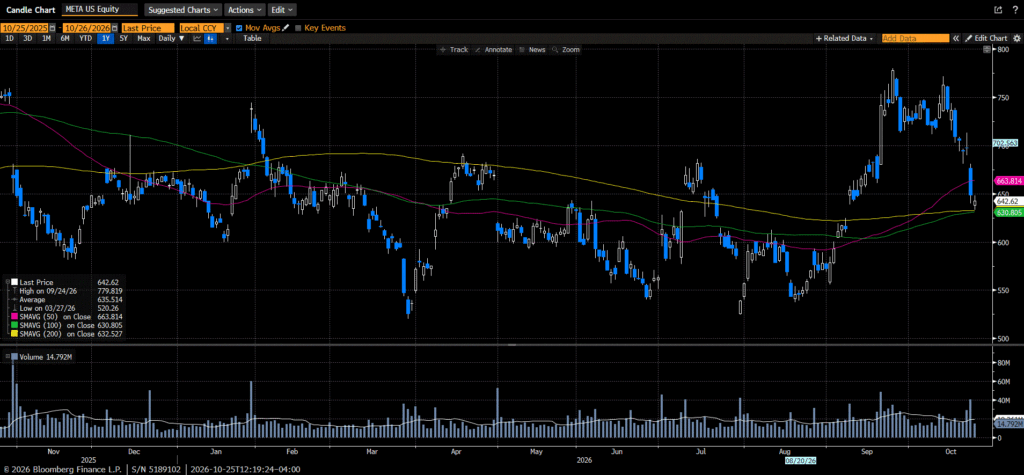
It was another volatile week on Wall Street, with US indices ending the week with mixed results. Ongoing concerns about AI financing and its return on investment continued after Meta announced its 3rd-quarter results. The company beat estimates and offered solid guidance. However, its higher AI capital expenditures, lower margins, and negative free cash flow fueled a sell-off in AI infrastructure names. Investors rotated into energy, staples, healthcare, and interest rate-sensitive sectors such as small-caps, real estate, and utilities. According to FactSet, we are about a quarter of the way through 3rd-quarter earnings. 83% of the companies that reported have beaten earnings expectations, while 66% have beaten revenue expectations. Earnings Per Share growth for the quarter is currently an impressive 29%. Microsoft, Google, and Amazon are set to report earnings this week.

Increased hostilities between the Houthis and Saudi Arabia, along with what appears to be an inevitable escalation in war between the US and Iran, sent oil prices to the highest level in six months. Brent oil settled at 116.72 a barrel, up 6.2% for the week.
Interestingly, interest rates have decoupled from crude prices over the last couple of weeks. Yields moved lower across the curve, with the 10-Year US Treasury yield closing at 4.99%. The Federal Reserve meets this week; it is widely expected to keep its policy rate unchanged at 3.75%-4%. There is currently a 76% percent probability that the Fed will hike rates at the December meeting. Also of note, the European Central Bank and the Bank of Japan are expected to keep their policy rates unchanged this week.
The S&P 500 shed 0.46%, the Dow rose 0.42%, the NASDAQ fell 0.71%, and the Russell 2000 gained 2.01%. As I mentioned, yields fell across the curve for the third straight week. The 2-year yield fell six basis points to 4.68%, while the 10-year yield fell eleven basis points to 4.99%. WTI oil prices increased by 1.74% to close the week at 103.17 a barrel. Gold prices fell 4.14% for the week, closing at $4,007.40 an ounce after trading below $4,000 on Friday. Silver prices plunged 5.86%, closing at $53.95 per ounce. Copper prices fell six cents to 6.51 per Lb. Bitcoin’s price fell by ~$1,100 to $80,400. The US Dollar index closed the week little changed at 101.81.

Economic data reported during the week showed a resilient economy. The S&P Global Manufacturing PMI increased to 56 from 55.9, while the Services PMI decelerated to 57.9 from 58.8 but remained in expansion. High-frequency employment data showed Initial Jobless Claims falling by 4k to 194k and Continuing Claims increasing by 25k to 1728k. Housing Starts came in at 1221k versus the previous reading of 1288k, while building permits increased by 1400k.
It should be another eventful week for investors. We have several Central Bank meetings to take cues from. The tone coming out of all these meetings will likely dictate market movements. 3rd-quarter earnings will ramp up this week, with Microsoft, Amazon, Google, Lilly, Caterpillar, and Intel reporting. We will get a first look at Q3 GDP estimates, with the consensus estimate at 3%, and the Fed’s preferred measure of inflation, the PCE, which is expected to come in at 0.5% on the headline reading.

Investment advisory services offered through Foundations Investment Advisors, LLC (“FIA”), an SEC registered investment adviser. FIA’s Darren Leavitt authors this commentary which may include information and statistical data obtained from and/or prepared by third party sources that FIA deems reliable but in no way does FIA guarantee the accuracy or completeness. All such third party information and statistical data contained herein is subject to change without notice. Nothing herein constitutes legal, tax or investment advice or any recommendation that any security, portfolio of securities, or investment strategy is suitable for any specific person. Personal investment advice can only be rendered after the engagement of FIA for services, execution of required documentation, including receipt of required disclosures. All investments involve risk and past performance is no guarantee of future results. For registration information on FIA, please go to https://adviserinfo.sec.gov/ and search by our firm name or by our CRD #175083. Advisory services are only offered to clients or prospective clients where FIA and its representatives are properly licensed or exempted.