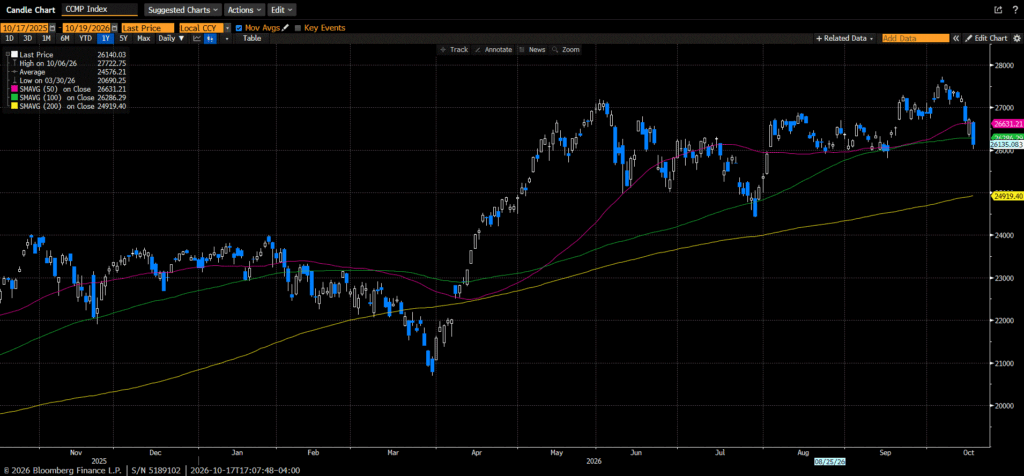
It was a chaotic week on Wall Street as investors tried to interpret mixed Q3 financial results, a spike in oil prices, sharp swings in yields across the curve, hotter-than-expected inflation data, dovish tones from central bankers, and renewed concerns about the AI infrastructure buildout, its use of credit, and the timing of when or if there will be a return on investment. Q3 earnings started in earnest, with several large banks reporting. JP Morgan, Morgan Stanley, Goldman Sachs, and Citi Bank reported solid results, while Bank of America and Wells Fargo reported disappointing results. Equity trading drove bank outperformance this quarter, while fixed income results lagged. Solid results from Taiwan Semiconductor were met with selling as the Semiconductor sector continued to come under pressure. The Philadelphia Semiconductor index has declined eight consecutive days, a setup not seen since 2008. Part of the losses were attributed to an advancement in memory technology out of China that catalyzed a selloff in Micron Technology, SK Hynix, Samsung, and Western Digital- some of the best-performing stocks this year. Weakness in Technology also came from the reemergence of concerns about Capex spending, how it has been and will be funded, and scrutiny over when these expenditures will return value to shareholders. Coreweave and Nebius, Neo Cloud AI infrastructure names, were throttled as their bonds came under significant pressure. Credit Default Swap prices also ticked up for several AI names, including Oracle. Oil prices spiked amid increased tensions in the Middle East as Saudi Arabia faced several lethal attacks. Tensions rose as a ceasefire between Russia and Ukraine proved short-lived. Increased oil prices, along with a hotter-than-expected CPI print, sent yields higher, but dovish comments from New York Fed President Williams and Fed Governor Waller tempered the move. Additionally, the sharp sell-off in Technology induced a flight to safe havens, which drove yields down across the curve, most notably at the longer end.

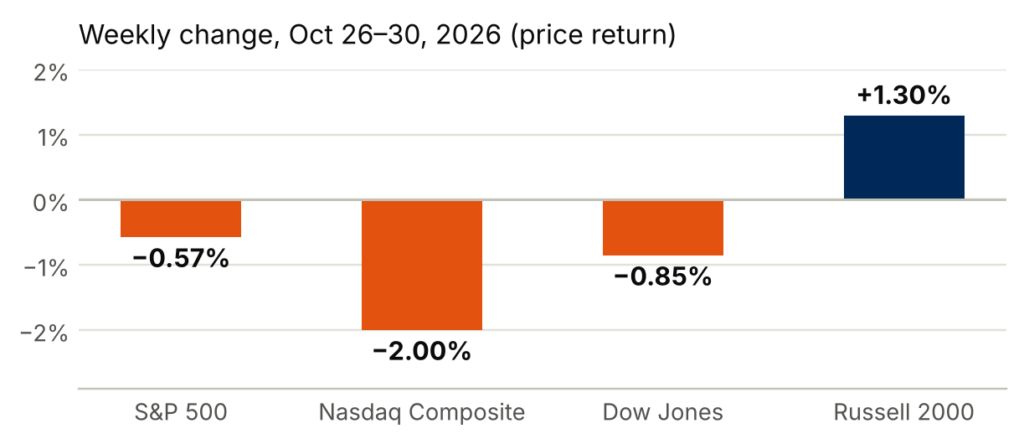
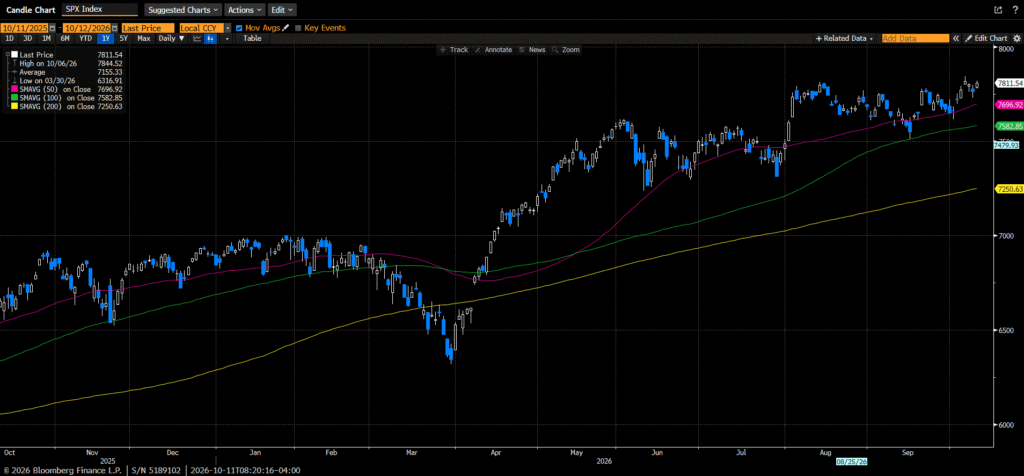
The S&P 500 is up 120% from the lows of 2022 but fell nearly 2% this week. The Dow bucked the trend, gaining 0.67% as investors rotated out of Technology and into other sectors. The NASDAQ composite declined 4.48%, while the NASDAQ 100 saw its worst week since April of last year. The Russell 2000 shed 3.04% on the week despite yields moving lower. US Treasuries were higher by week’s end, but fixed income traders had quite a ride. The 2-year yield fell five basis points to 4.74%, while the 10-year yield fell fourteen basis points to 5.10%. Oil prices spiked higher by 10.31% to close at $101.40 a barrel. Gold prices declined by $35.30 to $4,180.90 per ounce. Silver prices plunged 6.12% to $57.31 per ounce. Copper prices declined by twelve cents to $6.57 per Lb. Bitcoin’s price fell by $1300 to $81,500. The VIX, an equity measure of volatility, rose 34%. The US Dollar index declined by 0.4% to 101.83.

The economic calendar featured Consumer Price Index and Producer Price Index inflation prints. September headline CPI rose 0.6% versus the estimate of 0.5% to 3.7% from 3.4% on a year-over-year basis. The Core reading, which excludes food and energy, rose by 0.3% versus the consensus estimate of 0.2%. Year-over-year, the Core reading rose to 2.6% from 2.4% in August. September headline PPI increased by 1.3%, well above the consensus of 0.5%. Year-over-year, the figure jumped to 6.3% from 5.6% in August. Core PPI rose by 0.7%, above the estimated 0.3%. Year-over-year, Core PPI rose 5% from 4.8% in August. Energy prices clearly influenced the headline readings, with the Energy Index up 5.2% in the CPI figure. Retail sales rose 0.8% versus the 0.3% estimate, with much of the increase coming from higher gasoline prices. The Ex-Auto reading rose 0.9%, better than the 0.3% estimate. Initial Jobless Claims increased by 1k to 199k, while Continuing Claims decreased by 4k to 1710k. Existing Home Sales came in at 3.99m versus the previous 3.93m
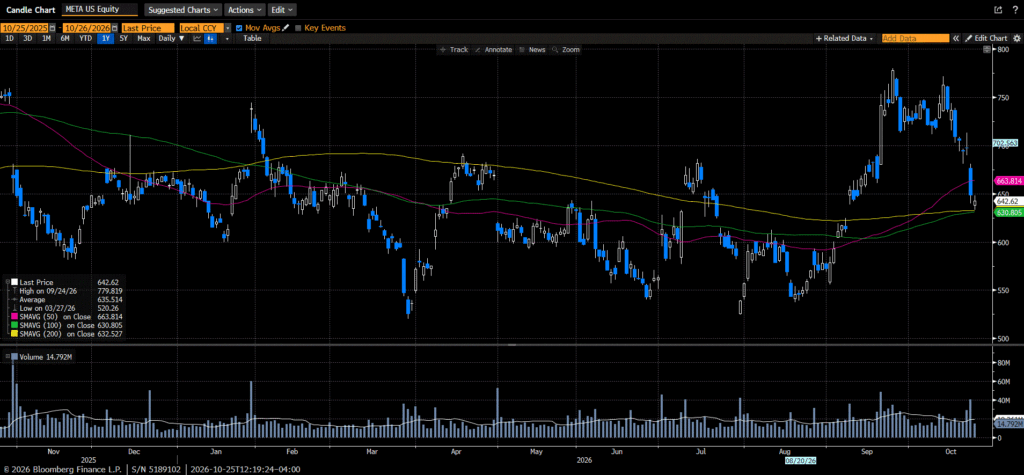
Q3 earnings continue this week with Meta, Netflix, Tesla, and IBM as highlights. We will also receive more U.S. housing data and hear from Treasury Secretary Scott Bessent and Nvidia CEO Jensen Huang.

Investment advisory services offered through Foundations Investment Advisors, LLC (“FIA”), an SEC registered investment adviser. FIA’s Darren Leavitt authors this commentary which may include information and statistical data obtained from and/or prepared by third party sources that FIA deems reliable but in no way does FIA guarantee the accuracy or completeness. All such third party information and statistical data contained herein is subject to change without notice. Nothing herein constitutes legal, tax or investment advice or any recommendation that any security, portfolio of securities, or investment strategy is suitable for any specific person. Personal investment advice can only be rendered after the engagement of FIA for services, execution of required documentation, including receipt of required disclosures. All investments involve risk and past performance is no guarantee of future results. For registration information on FIA, please go to https://adviserinfo.sec.gov/ and search by our firm name or by our CRD #175083. Advisory services are only offered to clients or prospective clients where FIA and its representatives are properly licensed or exempted.