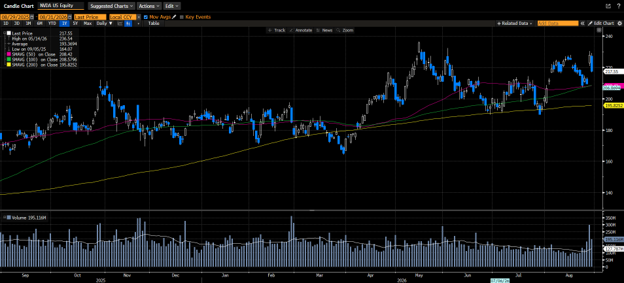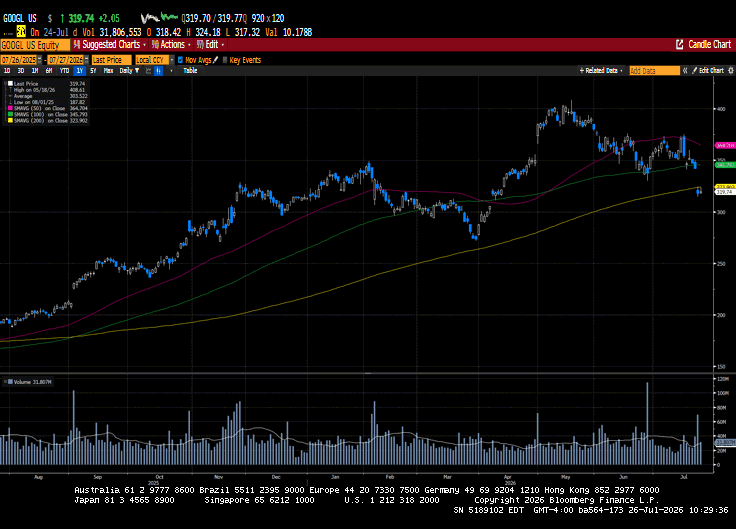
US equity indices declined for a second consecutive week despite a strong start to second-quarter earnings. With just over 25% of the S&P 500 reporting, top- and bottom-line growth rates have been better than anticipated. Results this week from Google, Intel, and Tesla beat expectations but led to weakness amid concerns about capital expenditure increases, margin pressures, and negative free cash flow. Escalating tensions in the Middle East pushed up energy prices and, in turn, inflation expectations. The Houthis struck two Saudi tanker ships transiting the Red Sea’s Bab El Mandeb Strait, threatening another passageway for global shipments. On Friday, the market rallied on news that China had intervened and asked the warring parties to return to the negotiating table. This weekend, attacks from both sides have subsided, with sources citing concerns over munitions supplies. Notably, the European Central Bank made no change to its monetary policy rate. Additionally, the market had to contend with a fresh round of tariffs replacing the 10% universal tariff that was expiring. The new tariffs range from 10% to 12.5% and were levied on 60 countries, including Australia, Canada, Brazil, and several European nations.

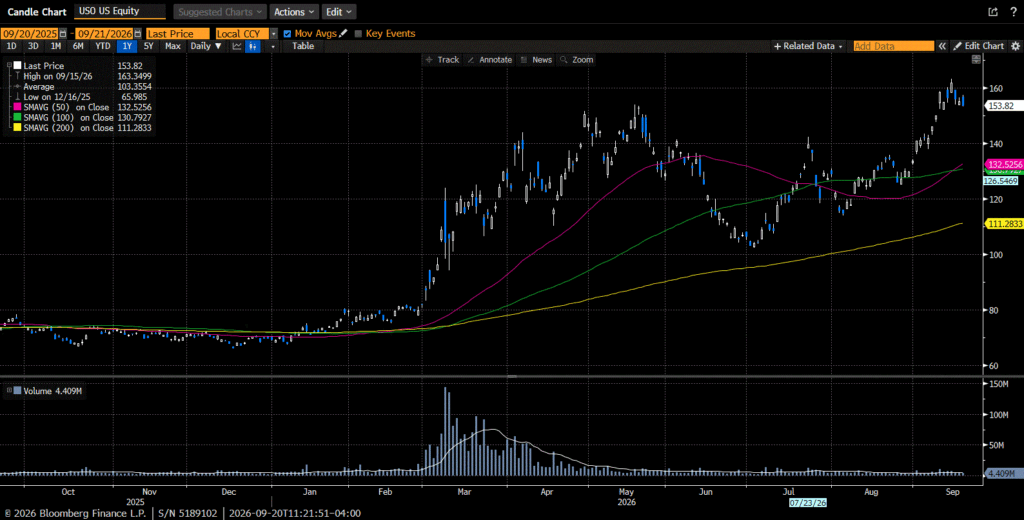
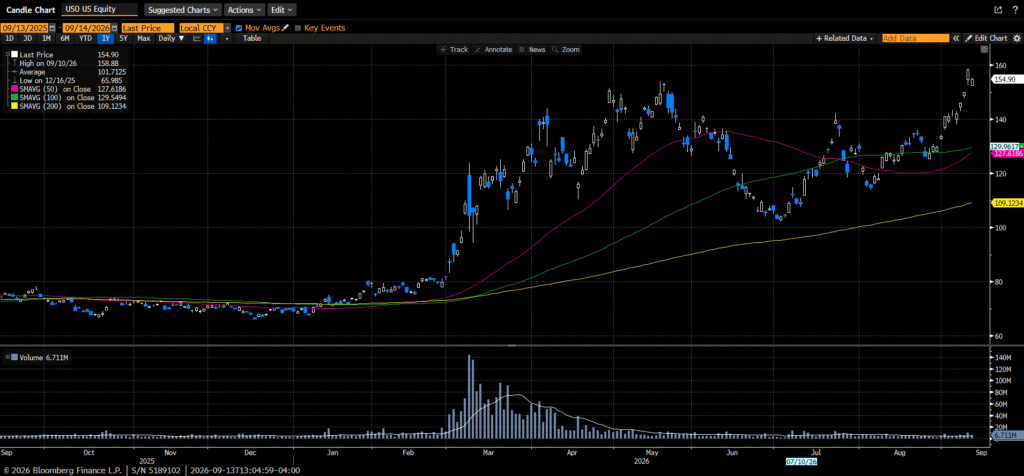
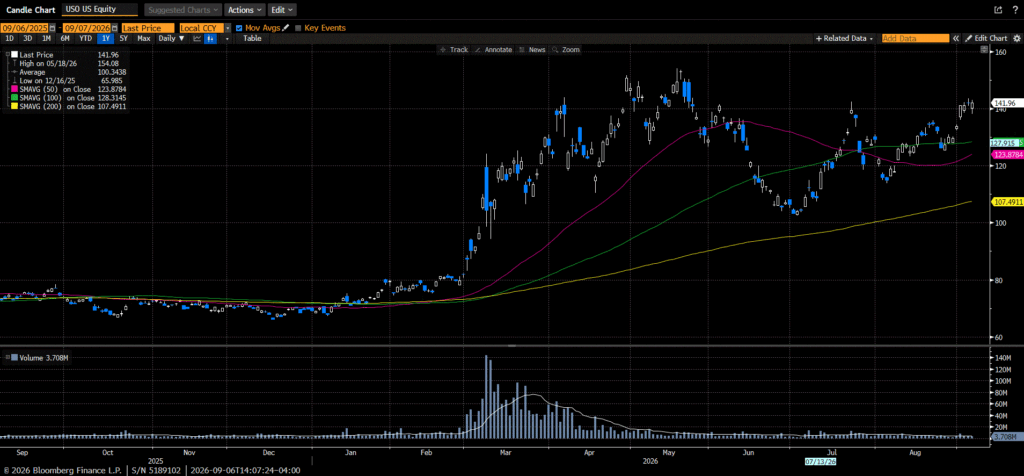
The S&P 500 shed 0.61%, the Dow lost 0.38%, the NASDAQ declined 2.13%, and the Russell 2000 gave back 1.09%. US Treasuries continued to struggle amid heightened inflation fears. The curve shifted higher again in a symmetrical fashion, with the 2-year yield up sixteen basis points to 4.33% and the 10-year yield up fourteen basis points to close the week at 4.68%. Both tenors’ yields closed near their year-to-date highs. Oil prices jumped 9.39% to close the week at $89.34 a barrel. Gold prices increased by $52.60 to $4,071.30 per ounce. Silver prices were up 4.78%, closing at $58.91 per ounce. Copper prices rose by nine cents to $6.36 per lb. Bitcoin’s price was unchanged on the week at $64,000. The US Dollar index was up 0.7% to 101.44.

The economic calendar was quiet last week. Initial Claims fell by 22k to 187k, the lowest level since the 1980s. Continuing Claims fell by 2k to 1796k. The S&P Global Manufacturing PMI decreased to 53.8 from 53.9, while the Services PMI rose to 53.6 from 51.2. New Home sales came in higher than expected at 628k versus the consensus of 605k.
In the coming week, several central banks will make policy decisions, including the Federal Reserve, Bank of Japan, and Bank of England. We will also receive a deluge of corporate earnings announcements, including Apple, Meta, Amazon, Samsung, SK Hynix, and Microsoft. Markets will also digest the Fed’s preferred measure of inflation, the PCE. We will get a second estimate of Q2 GDP, Consumer Confidence and Sentiment, Initial and Continuing Claims, and the Employment Cost Index.

Investment advisory services offered through Foundations Investment Advisors, LLC (“FIA”), an SEC registered investment adviser. FIA’s Darren Leavitt authors this commentary which may include information and statistical data obtained from and/or prepared by third party sources that FIA deems reliable but in no way does FIA guarantee the accuracy or completeness. All such third party information and statistical data contained herein is subject to change without notice. Nothing herein constitutes legal, tax or investment advice or any recommendation that any security, portfolio of securities, or investment strategy is suitable for any specific person. Personal investment advice can only be rendered after the engagement of FIA for services, execution of required documentation, including receipt of required disclosures. All investments involve risk and past performance is no guarantee of future results. For registration information on FIA, please go to https://adviserinfo.sec.gov/ and search by our firm name or by our CRD #175083. Advisory services are only offered to clients or prospective clients where FIA and its representatives are properly licensed or exempted.