Markets finished the week mixed as investors assessed the escalation of tensions between the US and Iran and recalibrated expectations of Federal Reserve monetary policy. The week started with sharp declines after the US hit targets on an island in the Strait of Hormuz that were ready to launch mines into the strait. Iran then countered with drone attacks on Jordan and the UAE. On Saturday, there were reports that the US had hit three Iranian cargo ships after Iran fired ballistic missiles at two US Navy ships. The news sent oil prices higher, which in turn raised inflation concerns. Markets settled down mid-week after Dell reported a solid quarter and after dovish comments made by Fed Bank of New York President John Williams. Markets moved higher on Thursday after Fed Governor Waller said he would be willing to hold rates steady if price pressures continue to ease and noted that the upcoming inflation data would be key to his decision. The Federal Reserve will meet September 15-16 to decide on monetary policy. Before Waller spoke on Thursday, Fed Funds futures assigned nearly a 70 percent chance of a 25-basis-point hike; that probability fell to 45 percent after his comments. The stronger-than-anticipated report on Friday recalibrated rate expectations again to nearly a 60% chance of a rate hike. US Treasuries were all over the place this week and ended the week with losses across the curve.

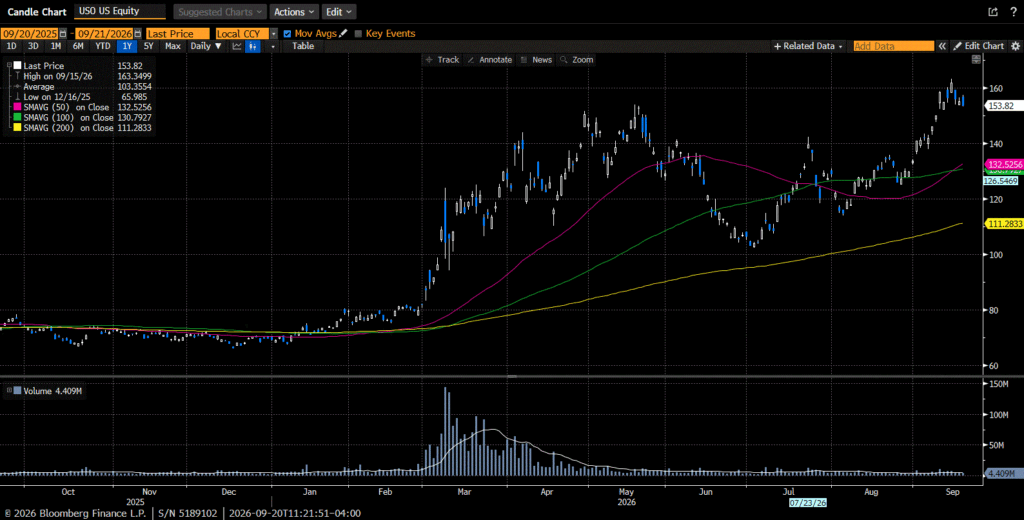
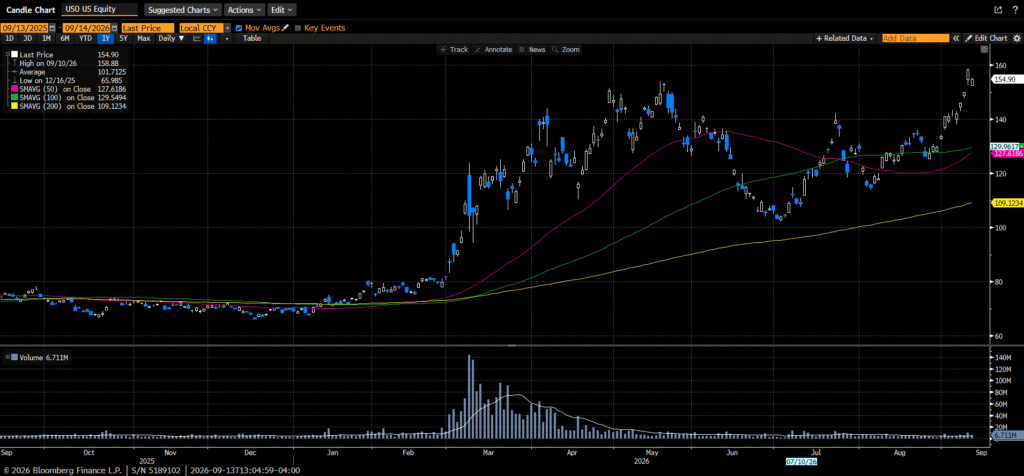
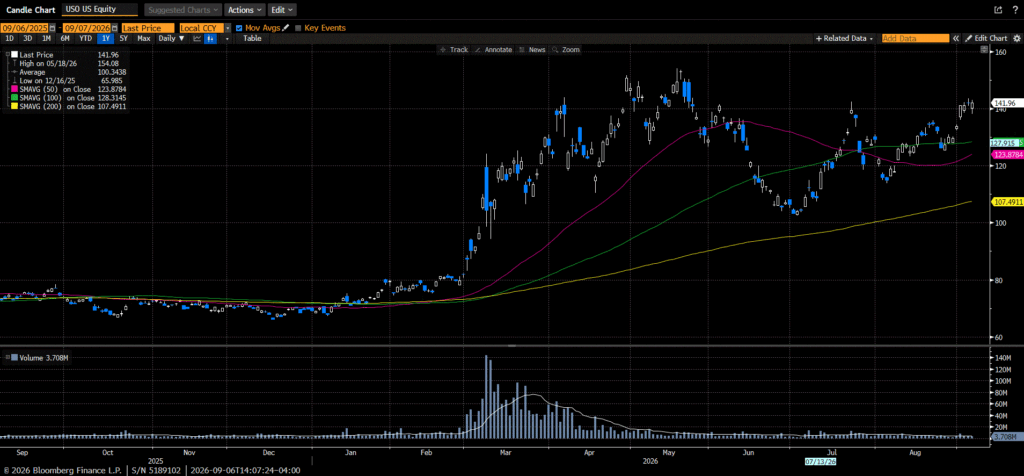
The S&P 500 gained 0.13%, the Dow fell 0.16%, the NASDAQ added 0.42%, and the Russell 2000 increased by 0.15%. The 2-year US Treasury yield increased by three basis points to 4.38%, while the 10-year yield increased by six basis points to 4.78%. Oil prices surged 10% amid heightened geopolitical tensions, reaching $91.50 a barrel. Gold prices fell by 1.15% to $4.476 per ounce. Silver prices declined by 1.53% to $66.75 per ounce. Copper prices increased by two cents to $6.68 per Lb. Bitcoin’s price increased by 2.7% to close the week at $79,800. Notably, the Japanese Yen had a huge move higher against the US Dollar, almost a 2% move, which is massive for a G10 currency. No intervention was announced; however, hawkish comments from the Bank of Japan, relative to dovish comments from Williams and Waller, may have contributed to the move. The US Dollar index fell 0.5%.

The economic calendar featured a better-than-expected BLS Employment Situation Report. Non-Farm Payrolls increased by 162k, well above the 55k consensus estimate. Private Payrolls also beat the consensus estimate, coming in at 127k. The Unemployment Rate declined to 4.1% from 4.2%. Average Hourly Earnings increased by 0.3% versus the estimate of 0.2%. The Average Work week ticked up to 34.4 hours from 34.3 hours. Initial Jobless Claims increased by 2k to 206k, while Continuing Claims increased by 8k to 1779k. JOLTS data showed an increase in job openings to 7.271m, while ADP payrolls came in at 38k versus the consensus estimate of 47k. All in, the labor market appears to be in good shape. The ISM Manufacturing PMI declined to 54.6 from 55.6 but remains in expansion. The ISM Services PMI increased to 55.4 from 54.1.

Investment advisory services offered through Foundations Investment Advisors, LLC (“FIA”), an SEC registered investment adviser. FIA’s Darren Leavitt authors this commentary which may include information and statistical data obtained from and/or prepared by third party sources that FIA deems reliable but in no way does FIA guarantee the accuracy or completeness. All such third party information and statistical data contained herein is subject to change without notice. Nothing herein constitutes legal, tax or investment advice or any recommendation that any security, portfolio of securities, or investment strategy is suitable for any specific person. Personal investment advice can only be rendered after the engagement of FIA for services, execution of required documentation, including receipt of required disclosures. All investments involve risk and past performance is no guarantee of future results. For registration information on FIA, please go to https://adviserinfo.sec.gov/ and search by our firm name or by our CRD #175083. Advisory services are only offered to clients or prospective clients where FIA and its representatives are properly licensed or exempted.