

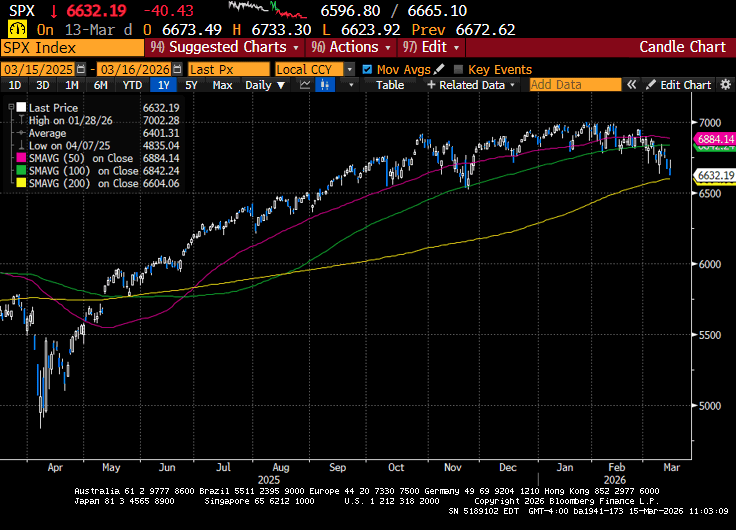
Markets remained volatile, driven by headlines related to the Iran war. Whipsaw action was prominent across multiple asset classes, while several historically safe-haven assets offered no cover for investors. Questions about the duration of the war and the closure of the Strait of Hormuz sent Brent Oil’s price to $120 a barrel, closing the week at just over $100 a barrel. Iran began targeting energy infrastructure, causing several facilities to curtail production. On Friday, the US and Israel “obliterated” Iran’s Kharg Island, one of Iran’s most significant energy hubs. The damage to any energy infrastructure extends the duration of supply disruption and is likely to lead to higher oil prices. These higher prices have pushed out the likelihood of a Federal Reserve cut to its monetary policy rate. Currently, the market has priced in one cut this year, most likely coming in September. The Federal Reserve will meet this week to discuss monetary policy and will provide its most recent Summary of Economic Projections. The Fed is not expected to change its policy rate; however, a significant shift to a more hawkish stance would likely be a negative catalyst for the market. Of note, a federal judge has thrown out a couple of subpoenas in the DOJ’s criminal probe into the Federal Reserve’s renovation of its office buildings.

The S&P 500 lost 1.6%, the Dow gave back 1.9%, the NASDAQ fell 1.2%, and the Russell 2000 sank by 1.9%. All these indices are now in negative territory for the year. US Treasuries were hammered for the second week in a row amid war-related inflation fears. The 2-year yield increased by seventeen basis points to 3.73%, while the 10-year yield increased by sixteen basis points to 4.29%. West Texas Intermediate crude price increased by 8.4%, closing at $98.56 a barrel. Gold prices retreated by 1% to close the week at $5061.70 per ounce. Silver prices fell by 4.4% to close at $80.56 per ounce. Copper prices fell by five cents to $5.76 per Lb. Bitcoin’s price increased by 6.6% to close the week at $71,400. The US Dollar index increased by 1.4%, closing at 100.36. The Japanese Yen fell against the greenback to 159.63, prompting jawboning by the Bank of Japan.

There was a full slate of economic data on the calendar that showed a mixed picture of the economy. The Fed’s preferred measure of inflation, the PCE, came in line with expectations on both the headline and core readings. On a year-over-year basis, the Core reading was a touch higher than the reading in December. The bottom line is that inflation remains above the Fed’s 2% target, and with oil prices surging, this will likely keep the Fed on hold. The Consumer Price Index also came in line with expectations on both the headline and core readings. The year-over-year figures were unchanged from the prior month. Personal Income was up 0.4% in line with the consensus estimate, while Personal Spending was higher than expected at 0.4%. The second look at 4th-quarter GDP fell to 0.7% from 1.4%, with most of the decline due to the government shutdown; however, there were some indications that consumer spending regressed. The University of Michigan’s Consumer Sentiment reading fell to a three-month low at 55.5 on inflation and labor concerns. Initial Jobless Claims fell by 1k to 213k, while Continuing Claims fell by 21k to 1850k. Finally, Existing Home Sales and Housing Starts came in better than expected, while Building Permits were below expectations.

Investment advisory services offered through Foundations Investment Advisors, LLC (“FIA”), an SEC registered investment adviser. FIA’s Darren Leavitt authors this commentary which may include information and statistical data obtained from and/or prepared by third party sources that FIA deems reliable but in no way does FIA guarantee the accuracy or completeness. All such third party information and statistical data contained herein is subject to change without notice. Nothing herein constitutes legal, tax or investment advice or any recommendation that any security, portfolio of securities, or investment strategy is suitable for any specific person. Personal investment advice can only be rendered after the engagement of FIA for services, execution of required documentation, including receipt of required disclosures. All investments involve risk and past performance is no guarantee of future results. For registration information on FIA, please go to https://adviserinfo.sec.gov/ and search by our firm name or by our CRD #175083. Advisory services are only offered to clients or prospective clients where FIA and its representatives are properly licensed or exempted.



