-Darren Leavitt, CFA
The final week of August was all about NVidia’s second-quarter earnings results and the Fed’s preferred measure of inflation, the PCE.
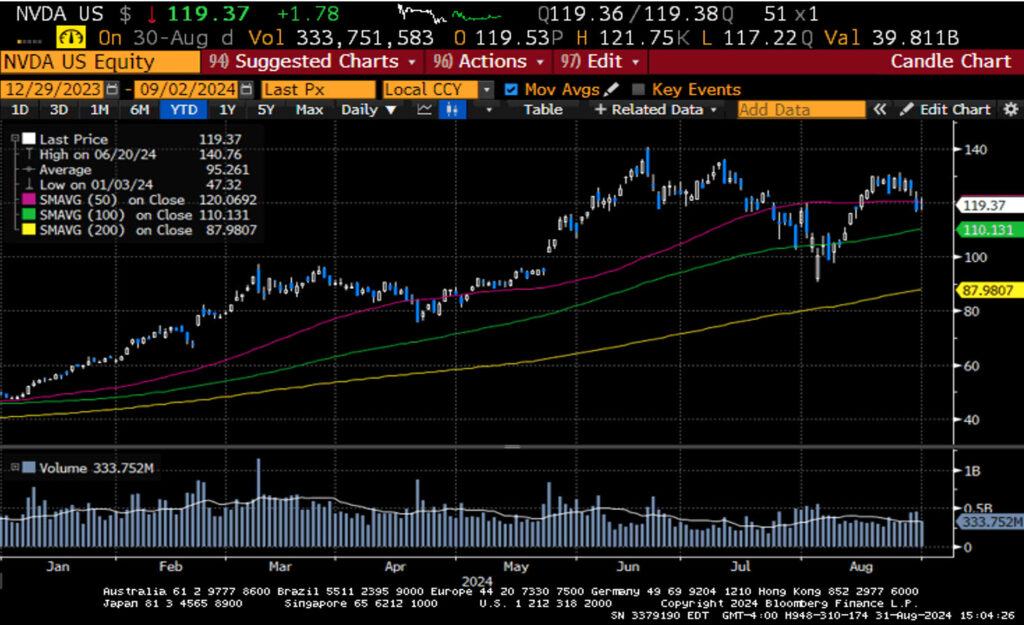
Expectations for NVidia’s earnings were so high that some decided to throw pre/post-earnings parties to celebrate the company’s results and its meteoric rise and influential position within the secular trend of artificial intelligence. NVidia posted 122% in revenue growth, or $32.5 billion, surpassing the consensus estimate of $31.9 billion. This revenue growth was down from prior quarters but still is quite impressive. Margins in the quarter were also down from previous quarters as the company builds out its newest technology, Blackwell, which has been delayed as partners adjust their systems for the latest chipset. The company seemed optimistic that the Blackwell initiative would be up and running soon and added that supplies would be ample for the product. NVidia also announced an astonishing $50 billion share buyback. The results were met with selling; however, the pressure on the stock seemed healthy, given the over 25% advance in the eight trading sessions preceding its earnings results.

Other second-quarter earnings highlights this week included BestBuy’s better-than-expected results, Dell’s continued success in selling its servers earmarked for AI, Salesforce.com’s solid quarter results, a significant miss by Dollar General, and mixed results from retailer Lululemon. Other corporate news included the announcement that Goldman Sachs would be cutting staff, an annual endeavor to weed out the company’s underperformers, and the news that Open AI was doing another funding round that estimates the company’s valuation at $100 billion.
The economic calendar showcased several different global inflation data sets that continued to show progress on inflation. Weaker European CPI data opens the door for the European Central Bank and the Bank of England to cut rates at their September meetings. Here in the US, the PCE showed modest growth but was in line with expectations, coming in at 0.2% and up 2.5% on a year-over-year basis, unchanged from June. Core PCE came in at 0.1%, which was higher than the consensus estimate of 0.1%, but again, it was unchanged on a year-over-year basis at 2.6%. Personal Income showed an increase of 0.3%, in line with the street, while Personal Spending was also in line with expectations at 0.5%. The spending number continued to support the idea that the consumer is still engaged. The second look at Q2 GDP showed a revision higher to 3% and increased due to consumer spending. Initial Claims fell by 2k to 231k, while Continuing Claims increased by 13k to 1868K. Consumer Confidence and Consumer Sentiment both came in better than expected and showed consumers applauding inflation slowing and encouraged by the Federal Reserve’s expectation to cut rates that they see as ultimately benefiting their finances. Data reported this week continued to support the narrative of a soft landing and give the Fed cover for a rate cut in September. The magnitude of the cut may still depend on what the August Payrolls report shows next Friday; an increase in the unemployment rate north of the current 4.3% may ignite a call for a 50 basis point cut while a considerable fall off in payrolls very well could have the same effect.

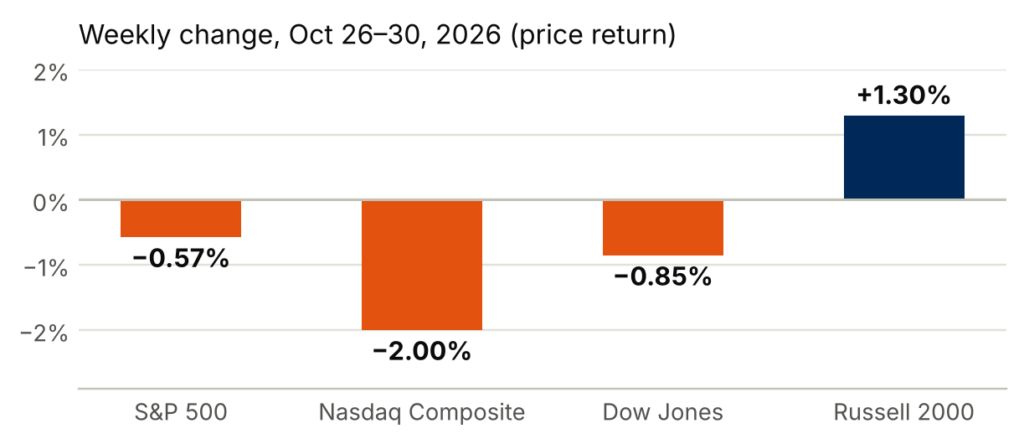
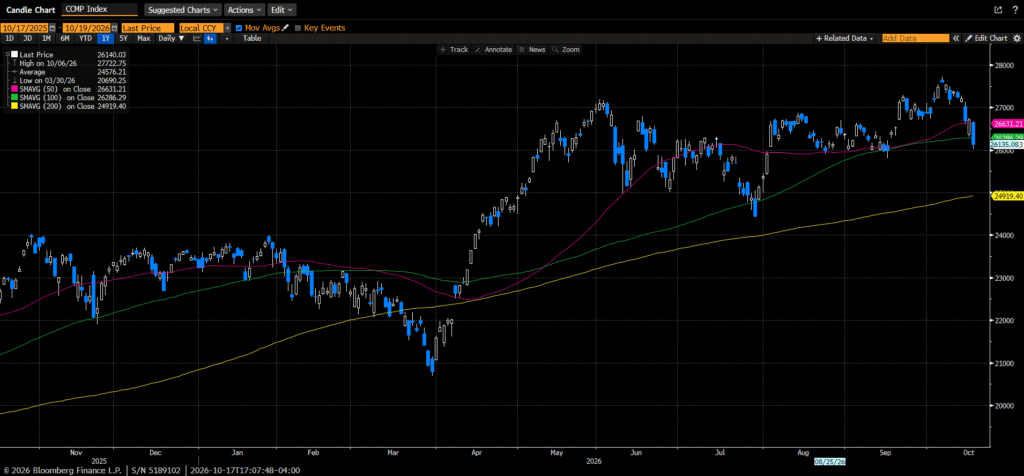
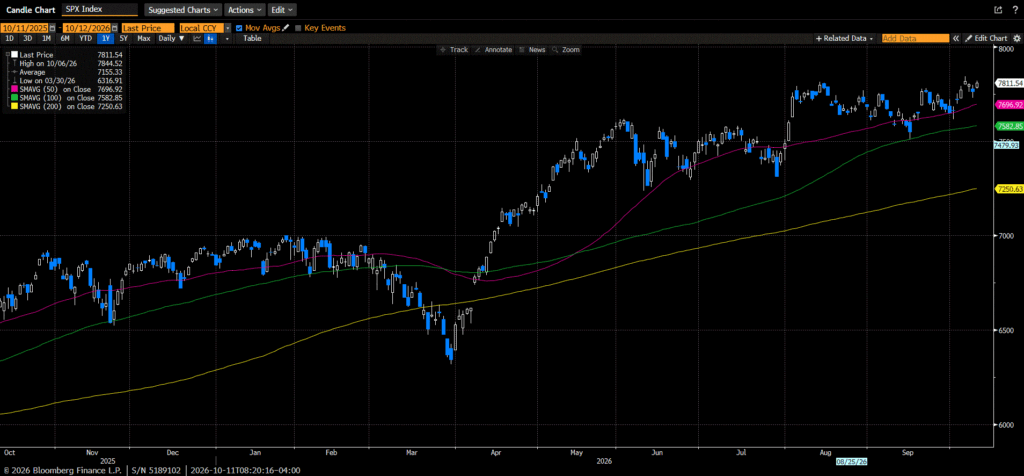
The S&P 500 advanced by 0.2% on the week- just missing a new all-time high, and increased 2.4% in August. The Dow outperformed this week with a gain of 0.9% and increased 1.8% in August. Notably, the Dow forged a new all-time high this week. The NASDAQ fell by 0.9%, hindered by weakness in NVidia, which has accounted for nearly a third of the composite’s performance this year. The NASDAQ increased 0.8% over August. The Russell 2000 closed just below the flat line for the week and gained 1.8% in August.
US Treasuries were on their heels this week as auctions in 2-year, 5-year, and 7-year were okay but not great. The yield curve continued its steepening trend as the 2-10 spread decreased to -2 basis points. The 2-year yield increased by two basis points for the week to 3.93% but was off forty-one basis points in August. The 10-year yield increased by ten basis point basis points to 3.91% and was off twenty basis points for the month.
Oil prices fell by $1.35 to $73.52 on reports that OPEC+ may increase production in the coming months. Gold prices fell by $18.80 to $2528.20. Copper prices increased a penny to $4.21 per Lb. Bitcoin traded below 60k to close at $5,874 Friday afternoon. The dollar index gained 0.1% on the week but gave back 2.2% in August, the worst monthly showing for the dollar this year.
Investment advisory services offered through Foundations Investment Advisors, LLC (“FIA”), an SEC registered investment adviser. FIA’s Darren Leavitt authors this commentary which may include information and statistical data obtained from and/or prepared by third party sources that FIA deems reliable but in no way does FIA guarantee the accuracy or completeness. All such third party information and statistical data contained herein is subject to change without notice. Nothing herein constitutes legal, tax or investment advice or any recommendation that any security, portfolio of securities, or investment strategy is suitable for any specific person. Personal investment advice can only be rendered after the engagement of FIA for services, execution of required documentation, including receipt of required disclosures. All investments involve risk and past performance is no guarantee of future results. For registration information on FIA, please go to https://adviserinfo.sec.gov/ and search by our firm name or by our CRD #175083. Advisory services are only offered to clients or prospective clients where FIA and its representatives are properly licensed or exempted.