

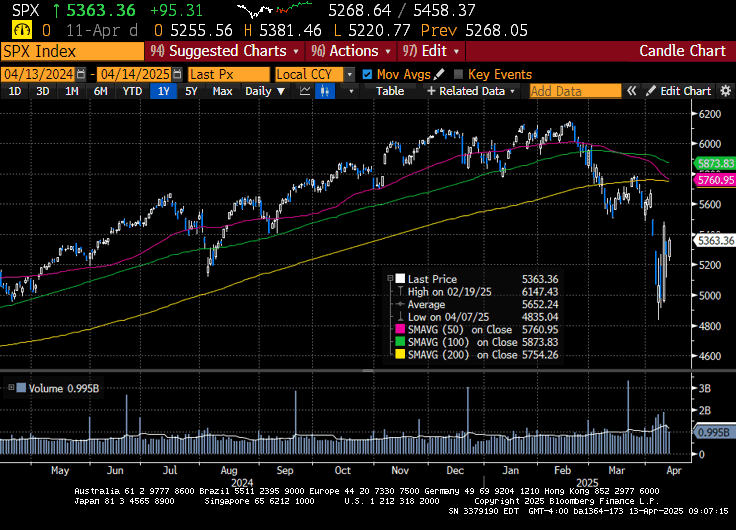
Wow, what a week on Wall Street. Continued uncertainty regarding trade policy induced massive swings in the equity, bond, commodity, and currency markets. A 7% intraday swing in the S&P 500 on Monday was superseded by a 10.8% intraday move on Wednesday, the largest since 1982. The move came on President Donald Trump’s announcement of a 90-day pause on most new tariffs, excluding those imposed on China. China’s retaliatory measures on tariffs escalated the situation as both sides increased tariffs- 125% imposed on US imports and 145% on Chinese imports. The policy uncertainty increased fears of a recession, which has prompted several Wall Street strategists to lower their market forecasts. Oppenheimer, which had been the most bullish on the street, slashed their year-end estimates on the S&P 500 to 5950 from 7100, while JP Morgan cut their estimate from 6500 to 5700. A significant sell-off in US Treasuries alongside a sell-off in the US dollar brought concerns that foreign institutions are selling US assets and repatriating that capital. Trump categorized the bond market as “tricky” and acknowledged the White House was watching it and noted that “people were getting a little ‘queasy” from its sell-off. Notably, the fifty-basis-point increase in rates on the 10-year was the largest weekly move since 1982. JP Morgan’s CEO Jamie Diamond told investors on the bank’s earnings call that he was worried about a possible kerfuffle in the US Treasury market. We are watching the bond market closely as it holds the key to so many aspects of the overall market. If it gets into more trouble, there will be more trouble to come in other markets. The Federal Reserve Open Market Committee minutes revealed Fed Officials concerned about stagflation. At the same time, Fed rhetoric throughout the week suggested ample reason to wait on cutting rates given the state of inflation. Boston Fed President, Susan Collins, gave the market a boost on Friday after saying the Federal Reserve is “absolutely” ready to help stabilize the market if needed. First quarter earnings started with some of the largest financial institutions reporting results. Morgan Stanley, JP Morgan, and Blackrock had solid quarters while Wells Fargo’s results missed estimates.

The S&P 500 posted a gain of 5.7%, the Dow rose by 5%, the NASDAQ climbed by 7.3%, and the Russell 2000 was higher by 1.8%. US Treasuries were hammered across the curve but more so on longer tenured paper. The 2-year yield increased by twenty-eight basis points to 3.95% while the 10-year yield increased by fifty basis points to 4.49%. Oil prices fell by $0.47 to close the week at $61.55 but had traded as low as $55.40. Gold prices surged as the precious metal was sought for its safe-haven quality. Gold prices increased by $211.30 and closed the week at new record highs at $3245.90 per ounce. Copper prices increased by $0.12 to close at $4.51 per Lb. Bitcoin’s price increased by ~$700 to close at $83,427. The US Dollar index fell by 2.7% to 100.14, the lowest since April 2022.

The economic calendar featured inflation data with the Consumer Price Index and the Producer Price Index. Headline CPI fell by 0.1% in March and increased by 2.4% year-over-year, down from 2.8% in February. The Core reading increased by 0.1%, up 2.8% year-over-year versus 3.1% in February. Headline PPI decreased by 0.4% versus an estimated increase of 0.1% and was up 2.7% year-over-year versus 3.2% in February. Core PPI declined by 0.1% versus the consensus estimate of 0.3% and was up 3.3% versus 3.5% in February on a year-over-year basis. Initial Claims increased by 4k to 223k, while Continuing Claims decreased by 43k to 1.850 M. A preliminary look at the University of Michigan’s Consumer sentiment showed another decline to 53.5, the prior reading came in at 57.

Investment advisory services offered through Foundations Investment Advisors, LLC (“FIA”), an SEC registered investment adviser. FIA’s Darren Leavitt authors this commentary which may include information and statistical data obtained from and/or prepared by third party sources that FIA deems reliable but in no way does FIA guarantee the accuracy or completeness. All such third party information and statistical data contained herein is subject to change without notice. Nothing herein constitutes legal, tax or investment advice or any recommendation that any security, portfolio of securities, or investment strategy is suitable for any specific person. Personal investment advice can only be rendered after the engagement of FIA for services, execution of required documentation, including receipt of required disclosures. All investments involve risk and past performance is no guarantee of future results. For registration information on FIA, please go to https://adviserinfo.sec.gov/ and search by our firm name or by our CRD #175083. Advisory services are only offered to clients or prospective clients where FIA and its representatives are properly licensed or exempted.



