


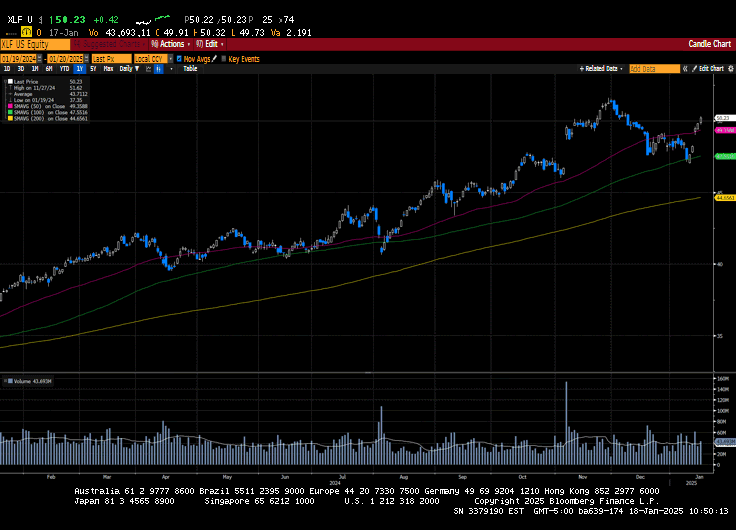
Financial markets advanced this week as a solid start to the fourth-quarter earnings season, and some better-than-feared inflation data gave investors a reason to buy the most recent dip. The financial sector gained 6.1% on the week as bank earnings rolled in with solid results. JP Morgan, Goldman Sachs, Morgan Stanley, Blackrock, and Citibank were some of the top performers in the group. The Producer Price Index (PPI) and the Consumer Price Index (CPI) showed sticky inflation. Still, the numbers were not as robust as some expected, which gave investors some relief on the inflation front. US Treasuries advanced significantly across the curve on the benign data. However, this sense of relief may be short-lived as the world awaits Trump 2.0 and the agenda that is poised to unfold next week after Trump is inaugurated on Monday as the 47th President of the United States. We expect Trump to announce tariffs shortly after taking office, although we did expect these tariffs to be titrated higher over time, as several reports have suggested. We also expect that the current immigration policy will materially change in the first days in office. A cease-fire has been agreed upon by Israel and Hamas, which is a situation that is also likely to be addressed by the President on his first day in office.
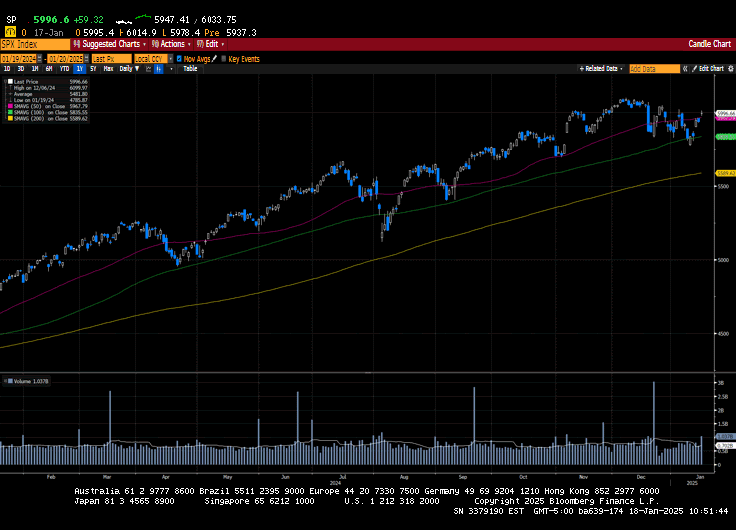
The S&P 500 gained 2.9% and retook its 50-day moving average. The Dow rose 3.7%, the NASDAQ climbed by 2.4%, and the Russell 2000 advanced 4%. US Treasuries rallied across the curve, with the 2-year yield decreasing by thirteen basis points to 4.27% and the 10-year yield falling by seventeen basis points to 4.61%. As yields fall, bond prices increase. Oil prices continued to trend higher, adding $0.69 to close at $77.52 a barrel. Gold price rose by 1.2% or $34.80 to $2748.50 an Oz. Copper prices increased by six cents to $4.36 per Lb. Bitcoin soared by nearly $10,000 to close above $105,000. The US Dollar index gave up 0.3% to 109.34.
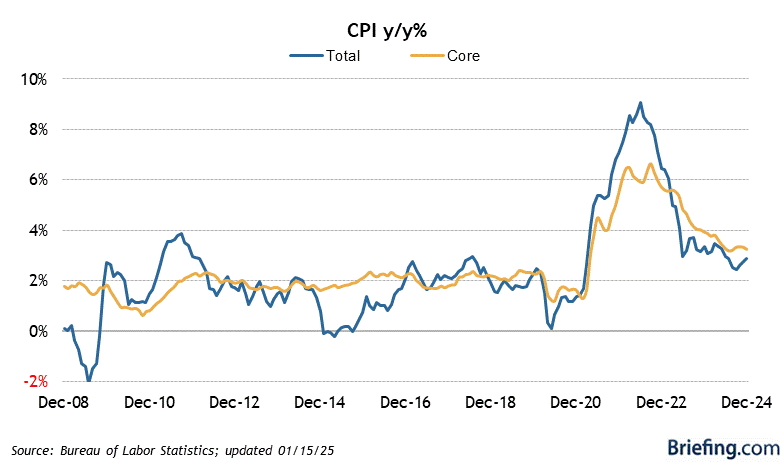
The PPI and CPI headlined the Economic calendar. The Producer Price Index (PPI) increased by 0.2% in December, lower than the consensus estimate of 0.3%. The reading was up 3.3% on a year-over-year basis, up from 3% in November. The core reading that excludes food and energy was flat in December versus an expected uptick of 0.3%. The core reading rose 3.5% annually, which was in line with the November figure. The Consumer Price Index (CPI) increased by 0.4%, slightly higher than the anticipated 0.3%. On a year-over-year basis, the figure increased by 2.9%, above the 2.7% reported in November. Core CPI was flat versus an expected increase of 0.3%. The Core reading on an annual basis came in at 3.2% in December, down from 3.3% in November. December Retail Sales increased by 0.4% versus the consensus estimate of 0.6%. The Ex-Auto metric also came in at 0.4%. Initial Jobless Claims increased by 14k to 217k, while Continuing Claims fell by 18k to 1.859M.
Investment advisory services offered through Foundations Investment Advisors, LLC (“FIA”), an SEC registered investment adviser. FIA’s Darren Leavitt authors this commentary which may include information and statistical data obtained from and/or prepared by third party sources that FIA deems reliable but in no way does FIA guarantee the accuracy or completeness. All such third party information and statistical data contained herein is subject to change without notice. Nothing herein constitutes legal, tax or investment advice or any recommendation that any security, portfolio of securities, or investment strategy is suitable for any specific person. Personal investment advice can only be rendered after the engagement of FIA for services, execution of required documentation, including receipt of required disclosures. All investments involve risk and past performance is no guarantee of future results. For registration information on FIA, please go to https://adviserinfo.sec.gov/ and search by our firm name or by our CRD #175083. Advisory services are only offered to clients or prospective clients where FIA and its representatives are properly licensed or exempted.



