


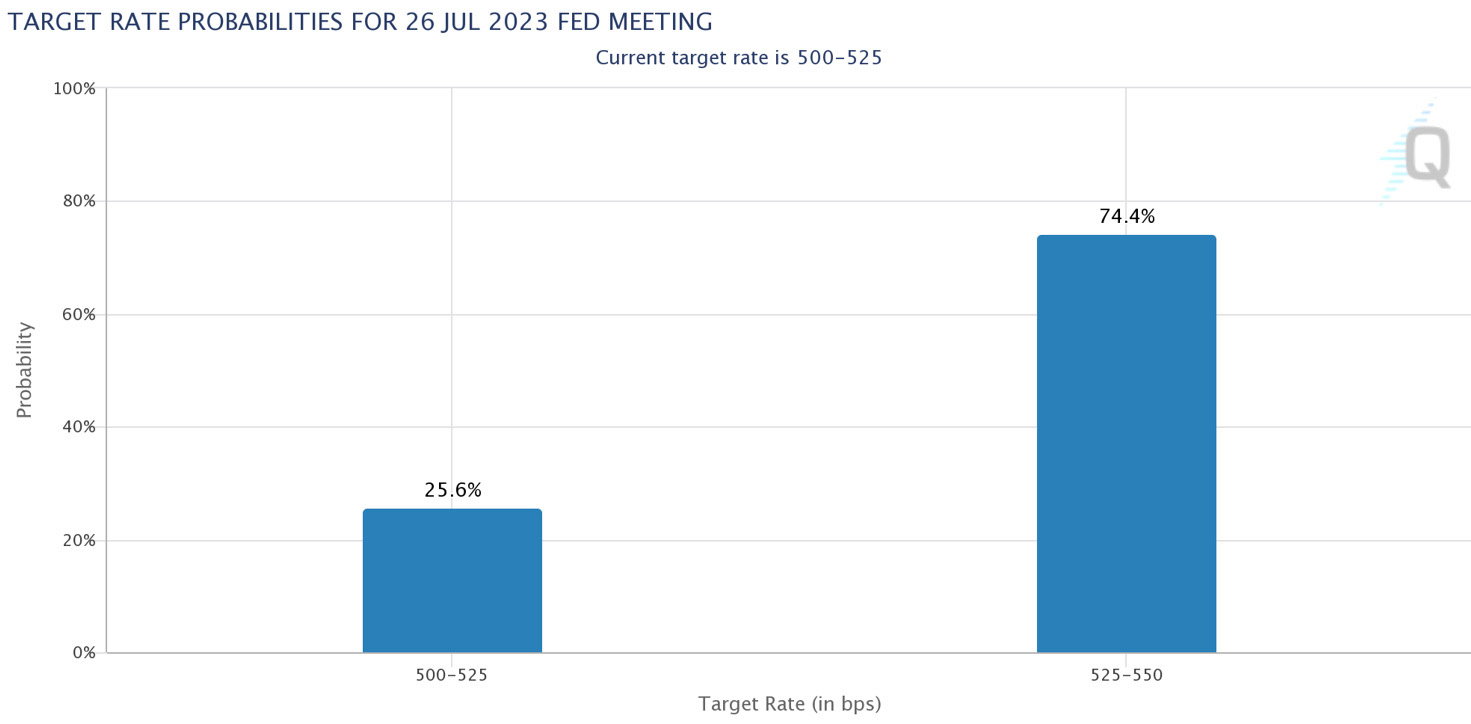
US equity markets continued to impress with another set of weekly gains. The mega-cap issues retook the lead, while small-cap issues lagged. Global central bank policy was top of mind for investors who received a full dose of economic data. The US Federal Reserve unanimously decided to hold its monetary policy rate at 5%-5.25% but indicated in its Summary of Economic Projections that the terminal rate is expected to top out at 5.6%. Chairman J. Powell was also relatively hawkish in his post-announcement Q&A, saying July is a live meeting. The European Central Bank raised its policy rate by 25 basis points, indicating that more rate hikes were probable. The Bank of Japan left its policy rate unchanged at -0.1%, while the Bank of England also decided to keep its rate intact. The Peoples Bank of China (PBOC) lowered its 1-year medium-term rate by ten basis points as China continues to stimulate its economy.
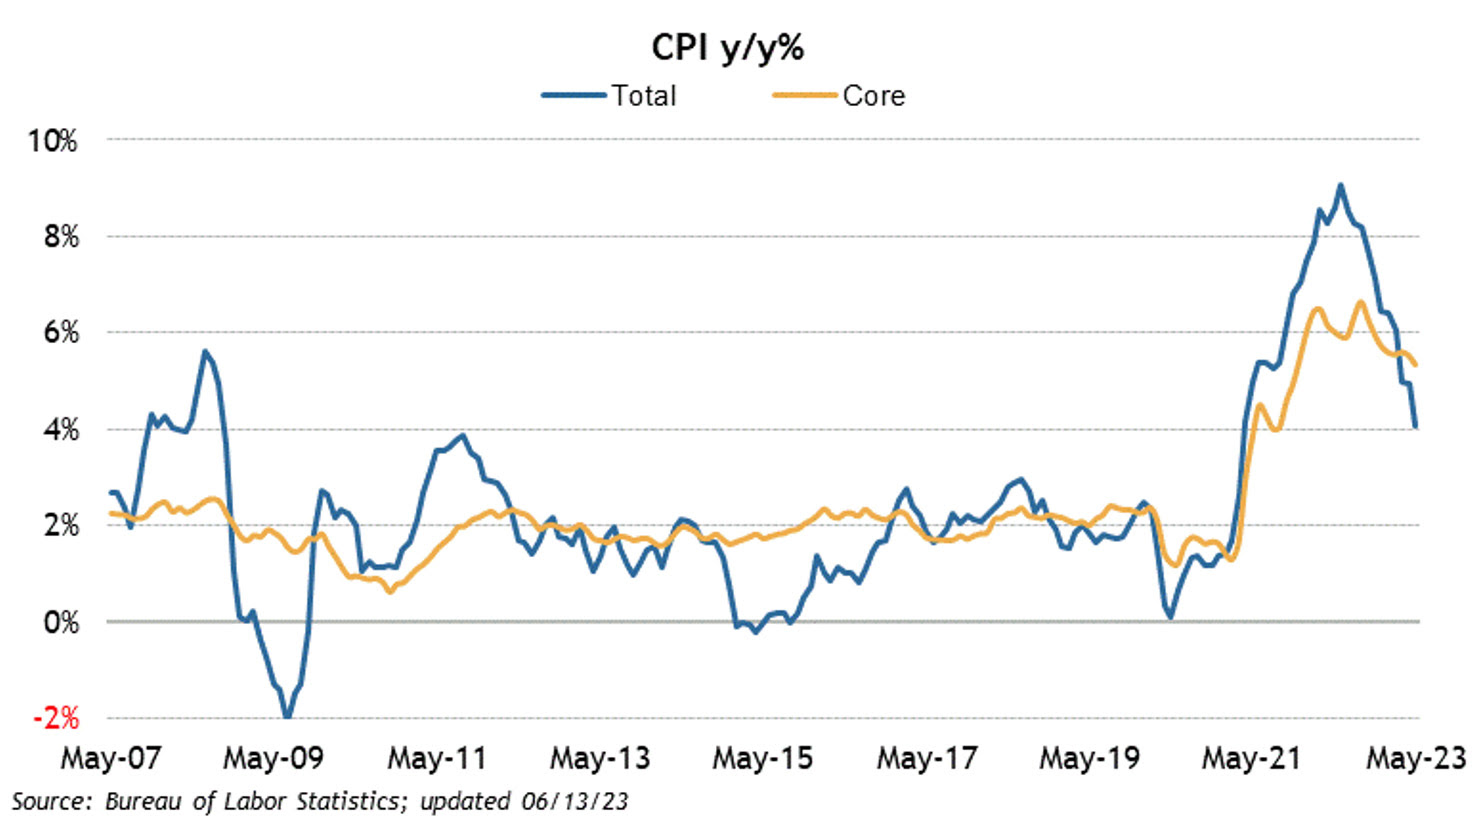
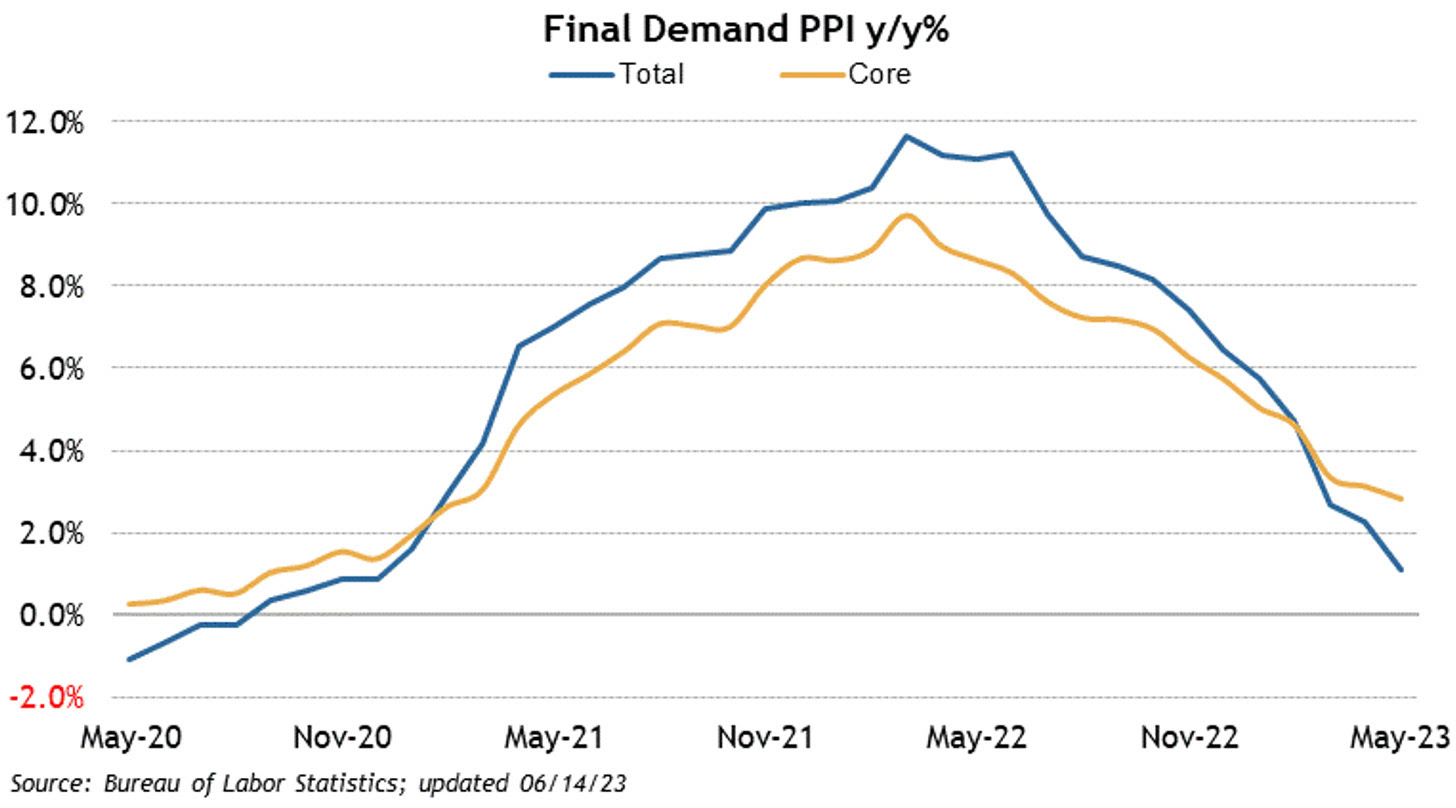
Economic data in the US showed continued moderation in prices. The Consumer Price Index came in line with expectations of an increase of 0.1%, while the core reading that excludes food and energy also came at 0.4%. On a year-over-year basis, the headline number came in at 4%, down from 4.9% in April. The core reading fell to 5% from 5.5% in April. Similarly, Producer Prices also fell in May. Headline PPI fell by 0.3% more than the consensus estimate of 0%. The Core reading increased by 0.2%, slightly above the expected increase of 01%. Both figures fell on a year-over-year basis from the prior month’s reading. While Core CPI on a year-over-year basis remains elevated, the street cheered the fact that prices continue to move in the right direction. The shelter component of the CPI continues to be elevated at 8% and makes up 60% of the CPI’s advance. Retail Sales increased by 0.3% in May, slightly more than the consensus estimate of 0.2%. Ex-Auto’s retail sales increased by 0.1% less than the 0.3% expected. Initial Claims came in north of 260K for the third week in a row, while Continuing Claims increased to 1775k from 1755k in the prior week.
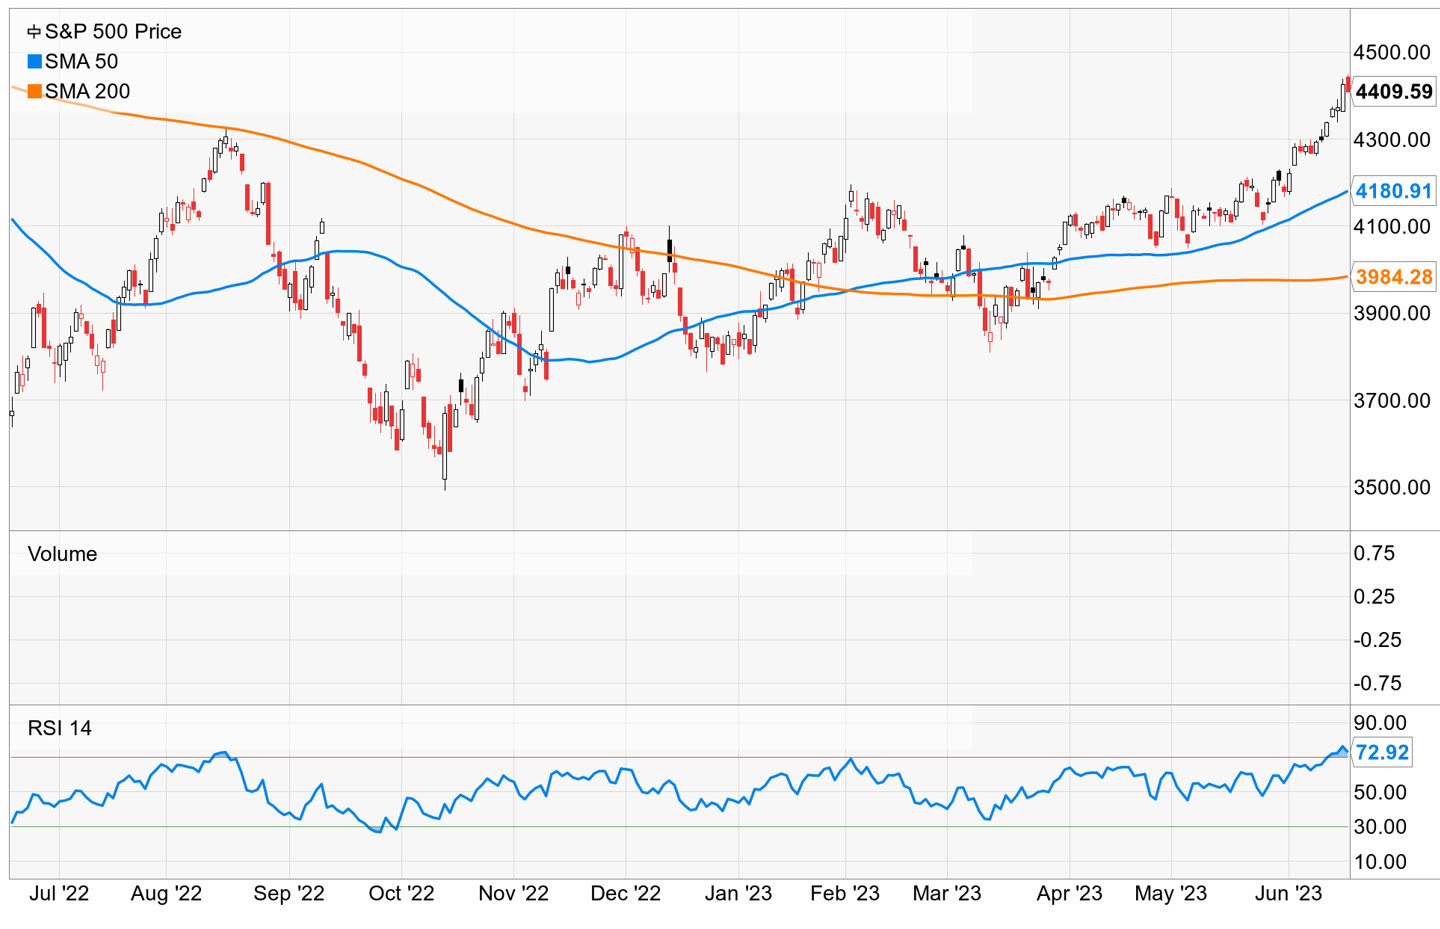
The S&P 500 inked a gain of 2.6% on the week and traded north of 4400. Goldman Sachs increased its year-end price target on the S&P 500 from 4000 to 4500. The Dow rose by 1.2%; the NASDAQ outperformed with a 3.2% gain from strong Information Technology Mega Caps and a strong showing from Semiconductors. The Russell 2000 lagged but added 0.5%.
US Treasuries continued to sell off, with yields moving higher across the curve. The 2-year yield increased by nine basis points to 4.71%, while the 10-year yield increased by two basis points to 3.77%. Oil prices rose by $1.62 to $71.92, but the energy sector lost ground on the week despite the move. Gold prices fell by $5.8 to close at $1971.30 an oz. Copper prices rebounded with a $0.11 gain to close at $3.89 an Lb. This week, the US Dollar index lost ground on significant weakness to the Euro and British Pound.
Investment advisory services offered through Foundations Investment Advisors, LLC (“FIA”), an SEC registered investment adviser. FIA’s Darren Leavitt authors this commentary which may include information and statistical data obtained from and/or prepared by third party sources that FIA deems reliable but in no way does FIA guarantee the accuracy or completeness. All such third party information and statistical data contained herein is subject to change without notice. Nothing herein constitutes legal, tax or investment advice or any recommendation that any security, portfolio of securities, or investment strategy is suitable for any specific person. Personal investment advice can only be rendered after the engagement of FIA for services, execution of required documentation, including receipt of required disclosures. All investments involve risk and past performance is no guarantee of future results. For registration information on FIA, please go to https://adviserinfo.sec.gov/ and search by our firm name or by our CRD #175083. Advisory services are only offered to clients or prospective clients where FIA and its representatives are properly licensed or exempted.



