

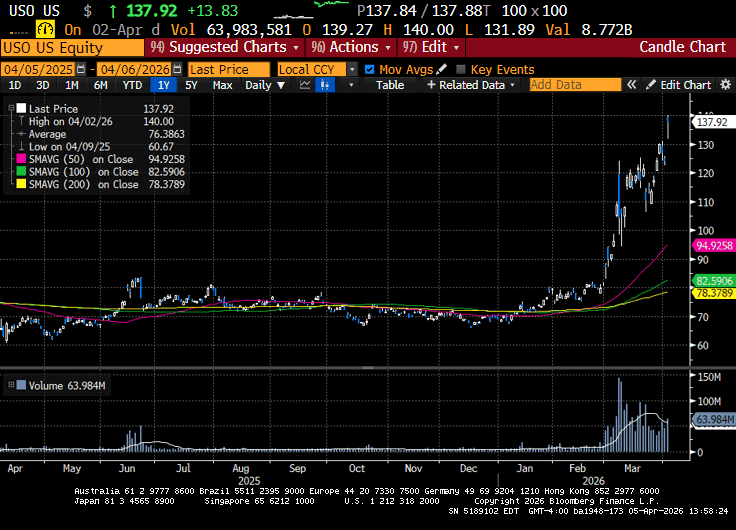
The holiday-shortened week saw US equities advance even as oil prices surged amid uncertainty about the duration of the Iranian conflict. Early in the week, investors bid up risk assets on hopes of a ceasefire. President Trump’s assessment of the ongoing negotiations with Iran on a ceasefire was completely dismissed by Iran’s leadership. News that Iran was working with Oman to allow tankers to transit through the Strait of Hormuz for a toll to the Islamic Republic was, at first glance, met with optimism, but the idea that Iran would charge a toll on passage through international waters prompted several Gulf nations to consider joining the war. President Trump addressed the nation on Wednesday evening, citing severe consequences for Iran if the Strait of Hormuz is not reopened, which ignited further concerns about the war’s duration. This weekend, this message was reiterated with a deadline set for Monday evening. The message comes as Iran continues to fire missiles and drones at Gulf nations’ energy infrastructure. Concerns about economic growth and inflation persist and will only become more acute as the conflict continues.

The S&P 500 gained 3.38%, the Dow rose 2.98%, the NASDAQ advanced 4.46%, and the Russell 2000 increased by 3.34%. US Treasuries also advanced for the week, with the 2-year yield declining by twelve basis points to 3.80% and the 10-year yield falling by thirteen basis points to 4.31%. West Texas Intermediate crude prices increased by 12%, closing at $111.48 per barrel. Gold prices advanced by 4.1% to close the week at $4,679.20 per ounce. Silver prices increased by 5.2% to $73.17 per ounce. Copper prices were up eight cents on the week to $5.58 per Lb. Bitcoin’s price increased by 1.5% to close at $67,300. The US Dollar index declined by 0.2% to 100.10.

The economic calendar produced strong expected data for the week. The Employment Situation report came out on Friday, even though the equity market was closed. Non-Farm Payrolls increased by 63k, more than the consensus estimate of 51K. Private Payrolls also topped estimates at 60k. The Unemployment Rate remained at 4.4%, while Average Hourly Earnings ticked down to 0.3% from 0.4% in the prior reading. The average workweek remained at 34.3 hours. All in, the better report took some bid out of US Treasuries over the abbreviated session on Friday. Initial Claims fell by 9k to 202k, while Continuing Claims increased by 25k to 1816k. Consumer Confidence inched higher to 91.8 from 91 in the prior reading. Retail Sales increased by 0.6%, better than the consensus estimate of 0.4%, while the Ex-Auto figure advanced by 0.5%, also topping expectations. ISM Manufacturing remained in expansion at 52.7, which was also higher than the previous reading.

Investment advisory services offered through Foundations Investment Advisors, LLC (“FIA”), an SEC registered investment adviser. FIA’s Darren Leavitt authors this commentary which may include information and statistical data obtained from and/or prepared by third party sources that FIA deems reliable but in no way does FIA guarantee the accuracy or completeness. All such third party information and statistical data contained herein is subject to change without notice. Nothing herein constitutes legal, tax or investment advice or any recommendation that any security, portfolio of securities, or investment strategy is suitable for any specific person. Personal investment advice can only be rendered after the engagement of FIA for services, execution of required documentation, including receipt of required disclosures. All investments involve risk and past performance is no guarantee of future results. For registration information on FIA, please go to https://adviserinfo.sec.gov/ and search by our firm name or by our CRD #175083. Advisory services are only offered to clients or prospective clients where FIA and its representatives are properly licensed or exempted.



