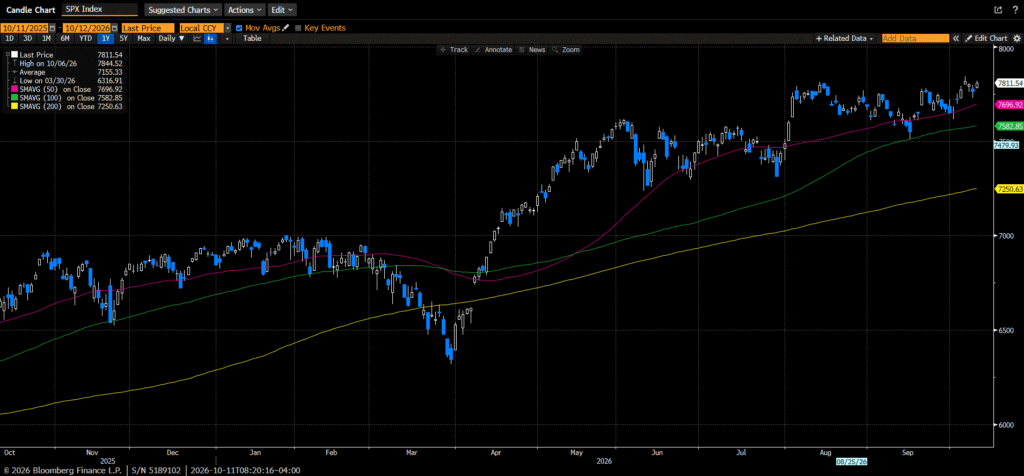
US markets finished the week mixed, with a late-week rally in technology mitigating early-week losses. Micron Technology’s third-quarter results were excellent and helped propel technology stocks after the announcement. Western Digital, Seagate, and Sandisk, other names in memory, traded higher in sympathy. The announcement that Oracle, Silver Lake, and MGX had finalized a deal to own 45% of TikTok sent Oracle’s shares materially higher after the company had been under pressure from debt concerns and delayed data center buildouts. As expected, the European Central Bank left its policy rate in place. At the same time, the Bank of England voted 5 to 4 to cut its policy rate by 25 basis points, and the Bank of Japan voted to raise its policy rate by 25 basis points to the highest level in 30 years. The Trump Administration was quite busy this week, meeting with several candidates for the Federal Reserve Chairmanship, and announcing changes to pharmaceutical pricing, the reclassification of cannabis, a year-end bonus for active military personnel, and granting federal workers Christmas Eve and the day after Christmas off.

The S&P 500 inched up 0.1%, the Dow lost 0.7%, the NASDAQ gained 0.5%, and the Russell 2000 fell 0.9%. U.S. Treasuries were bid higher across the curve, except at the long end. The 2-year yield fell by four basis points to 3.53%, while the 10-year yield fell by the same amount to 4.19%. Oil prices continued to struggle amid concerns about additional supply entering the market if the Russia-Ukraine war ends. WTI prices fell $0.93 to $56.53, while Brent fell below $60 a barrel. Gold prices increased by $59.50 to close the week at $4,387.10 per ounce. Silver prices continue to hit record highs, rising by 9.8% or $6.02 to $67.38 per ounce. Copper prices increased by fifteen cents to $5.51 per Lb. Bitcoin’s price fell by $2,400 to $87,800. The US Dollar index increased by 0.2% to 98.61.

A much-anticipated economic calendar did little to alter rate-cut expectations for January, which currently stand at a 22.1% chance of a cut. The Employment Situation report showed better-than-expected Non-Farm and Private Payrolls, which came in at 60k and 64k, respectively. The Unemployment Rate ticked to 4.6%, 0.2% higher than expected. Average Hourly earnings increased by 0.1%, less than the 0.2% consensus estimate. The Average Workweek increased to 34.3 hours versus the prior reading of 34.2. Initial Claims for the week fell by 13k to 224k, while Continuing Claims increased by 67k to 1897k. Headline October Retail Sales were flat versus an expected increase of 0.2%. The Ex-auto figure increased by 0.4%, better than the expected 0.2%. The Consumer Price Index (CPI) and Core CPI readings both came in at 0.2% month over month, in line with expectations. On a year-over-year basis, the headline number was up 2.7% versus 3% in the prior month, while the Core reading increased by 2.6% down from 3%. Note that this data is likely noisy due to the government shutdown, and the markets were relatively subdued by the mixed results.

Investment advisory services offered through Foundations Investment Advisors, LLC (“FIA”), an SEC registered investment adviser. FIA’s Darren Leavitt authors this commentary which may include information and statistical data obtained from and/or prepared by third party sources that FIA deems reliable but in no way does FIA guarantee the accuracy or completeness. All such third party information and statistical data contained herein is subject to change without notice. Nothing herein constitutes legal, tax or investment advice or any recommendation that any security, portfolio of securities, or investment strategy is suitable for any specific person. Personal investment advice can only be rendered after the engagement of FIA for services, execution of required documentation, including receipt of required disclosures. All investments involve risk and past performance is no guarantee of future results. For registration information on FIA, please go to https://adviserinfo.sec.gov/ and search by our firm name or by our CRD #175083. Advisory services are only offered to clients or prospective clients where FIA and its representatives are properly licensed or exempted.