

Markets bounced back as investors reengaged the pro-growth Trump 2.0 trade. President-elect Trump continued to fill out his cabinet and, late Friday announced Scott Bessent as his nominee for Treasury Secretary. Wall Street has endorsed Bessent, who is seen as a fiscal hawk who will support Trump’s tariffs and trade policies. Matt Gaetz removed himself as the nominee for Attorney General amid allegations of sexual misconduct, which prompted Trump to nominate Pam Bondi for the position. Current SEC Chairman Gary Gensler announced he would step down in January, which led to more discussions on deregulation, with much attention placed on the Cryptocurrency markets. Notably, Bitcoin approached $100k in Friday’s session.

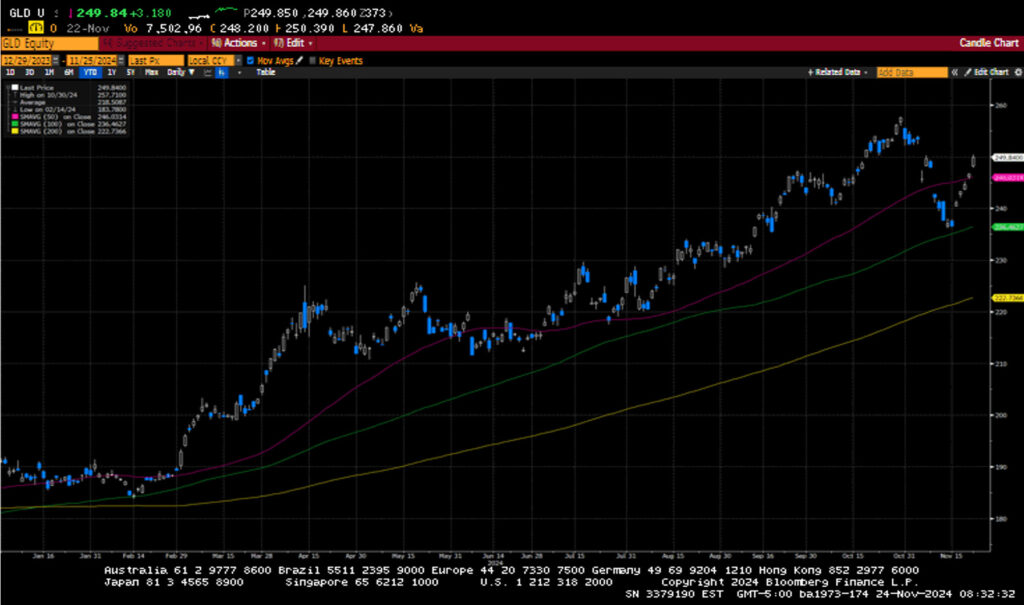
An escalation of tensions in the Russia-Ukraine war sent investors to safe-haven assets such as gold, the US Dollar, and US Treasuries. The use of US and British-made missiles by Ukraine on Russian assets prompted the Kremlin to update its nuclear doctrine and to use an intercontinental ballistic missile in a subsequent attack on Ukraine.
All eyes were on NVidia and its third-quarter earnings results. The company did not disappoint, posting better-than-expected results and raising guidance for the coming quarter. The stock ended the week flat, which is kind of crazy, given the market expectations for a sizeable move in either direction post-earnings. Other notable earnings included solid results from Walmart, Ross, and Snowflake. Target’s results were a disaster, sending shares lower by more than 20%.

The S&P 500 gained 1.2%, the Dow jumped 2%, the NASDAQ advanced 1.7%, and the Russell 2000 increased by 4.5%. Despite an early week’s bid into Treasuries, the yield curve saw selling at the front end of the curve. The 2-year yield increased by seven basis points to 4.37%, while the 10-year yield fell by two basis points to 4.41%. The 2-10 spread compressed to just four basis points.
Oil prices advanced by 6.3% or $4.26 to close at $71.28 a barrel. Gold prices increased by 5.5% to $2713.10, the largest weekly move since May 2023. Copper prices rose by $0.02 to $4.09 per Lb. Bitcoin rose by $6300 to $97,455, falling just short of 100k on Friday. The US Dollar index rose for the eighth consecutive week, gaining 0.8% and closing at 107.55. The Euro fell to 1.0410, while the Japanese Yen closed the week just under 155.

The economic calendar was relatively quiet. Housing Starts and Permits were weaker than expected as Existing Home Sales topped estimates. S&P Global Manufacturing and Services PMI data were weak globally, but Eurozone data was materially weaker than anticipated. In the US, Services data indicated further expansion, coming in at 57 versus 55 in October. Manufacturing in the US remained in contraction, but the pace of contraction was less than in October. Initial Jobless Claims fell by 6k to 213k, while Continuing Claims increased by 36k to 1908k. The final reading of the University of Michigan’s Consumer Sentiment Index came in at 71 versus the consensus estimate of 73.
Investment advisory services offered through Foundations Investment Advisors, LLC (“FIA”), an SEC registered investment adviser. FIA’s Darren Leavitt authors this commentary which may include information and statistical data obtained from and/or prepared by third party sources that FIA deems reliable but in no way does FIA guarantee the accuracy or completeness. All such third party information and statistical data contained herein is subject to change without notice. Nothing herein constitutes legal, tax or investment advice or any recommendation that any security, portfolio of securities, or investment strategy is suitable for any specific person. Personal investment advice can only be rendered after the engagement of FIA for services, execution of required documentation, including receipt of required disclosures. All investments involve risk and past performance is no guarantee of future results. For registration information on FIA, please go to https://adviserinfo.sec.gov/ and search by our firm name or by our CRD #175083. Advisory services are only offered to clients or prospective clients where FIA and its representatives are properly licensed or exempted.



