

-Darren Leavitt, CFA
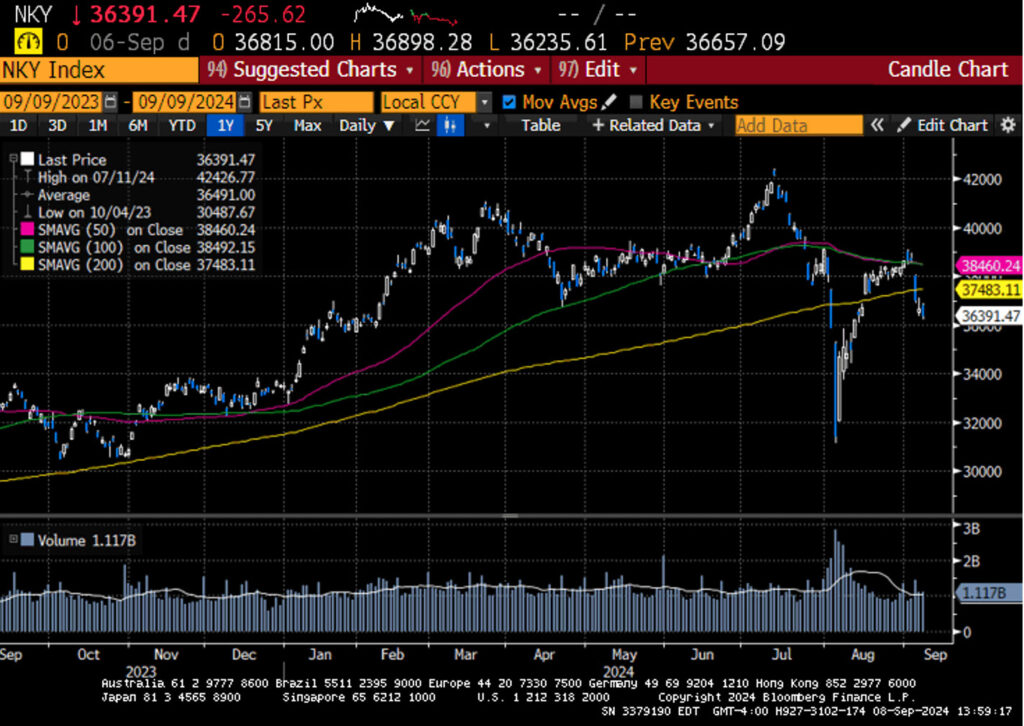
Global equity markets tumbled due to economic growth concerns as the US Treasuries extended their gains from August. The holiday-shortened week started with weaker-than-anticipated manufacturing data out of China, which highlighted just how weak the second-largest economy in the world has become. This influenced the commodity complex and economies that are more sensitive to China’s growth, such as Germany, where, coincidently, Volkswagen announced plans to close several manufacturing facilities. Markets were focused on a packed economic calendar, with most of the attention placed on the US labor markets. The data came in mixed and provided the markets with no clear evidence to make a call on how much the Federal Reserve is likely to cut in their upcoming meeting. Currently, the market is pricing in a 70% chance of a twenty-five basis point cut and a 30% of a fifty basis point cut. The market is also pricing in one hundred basis points of cuts in 2024 and two hundred over the next 12 months. I believe the Fed will cut by twenty-five in the coming meeting and that 100 this year and 200 over the next 12 months is slightly too aggressive. Interestingly, similar to what we saw at the beginning of August, the US Dollar/Yen cross weakened on a more Hawkish BOJ, sending the Nikkei 225 down nearly 5%.

A continued sell-off in the Semiconductor sector questioned market leadership within the mega-caps. NVidia shares tumbled almost 12% in two days, wiping out $275 billion in market cap on news that the company received a subpoena from the Department of Justice related to anti-competitive sales practices. Broadcom shares were hammered on weaker-than-expected guidance. Tesla shares saw a nice bid on news that the company would receive approval to use its self-driving technology in China and Europe. Dollar Tree’s shares plummeted on weaker-than-expected earnings and reiterated what we heard last week from Dollar General- that some parts of the US consumer market are deteriorating.

The S&P 500 fell 4.2% and posted its worst weekly performance since March 2023. September is known to be a seasonally weak time of year for equities for various reasons and has posted an average monthly loss of 4.2%. The Dow shed 2.9%, the NASDAQ plunged 5.8%, and the Russell 2000 decreased by 5.7%.
US Treasuries were well bid across the yield curve. The 2-year yield fell 28 basis points to 3.65%, while the 10-year yield decreased by 20 basis points to 3.71%. Of note, the yield curve’s inversion, present over the last several years, was reversed this week.

Oil prices cratered on the weaker economic outlook and uncertainty surrounding OPEC+ and Libyan production. WTI fell by 8%, or $5.84, to $67.68 a barrel. Gold prices were little changed, losing $3.00 to $2525.30 an Oz. Copper prices fell by $0.15, or 3.5%, to $4.07 per Lb. Bitcoin saw a significant pullback, closing the week at $54,210. The US dollar index continued to slide, closing down by 0.5% to 101.21.

As I mentioned, the economic calendar was stacked and headlined by the US Employment Situation report. Non-farm payrolls increased by 142K, less than the anticipated 165k. Notably, the Non-Farm payroll figures from June and July were revised lower to 118k and 89k, respectively. Private Payrolls increased by 118k but came in light of the street’s estimate of 142k. Average hourly earnings increased by 0.4%, 0.1% higher than the consensus estimate and up 3.8% in August from 3.6% in July. The Average workweek increased to 34.3 hours from 34.2 hours in July. All in a pretty good set of numbers- at least better than what we saw in July. The revisions are critical here and provide another layer of uncertainty. The markets sold off on the numbers, and interestingly, at the same time, the probability of a 50 basis point cut fell. Continuing Claims decreased by 5k to 227k, while Continuing Claims fell by 22k to 1.838M. JOLTS data showed job openings at their lowest level since 2021.
ISM Manufacturing continued to show contraction with a reading of 47.2, but the reading improved from the prior reading of 46.8. ISM Services continued to show expansion and came in better than expected at 51.5, just above the previous reading of 51.4.
Investment advisory services offered through Foundations Investment Advisors, LLC (“FIA”), an SEC registered investment adviser. FIA’s Darren Leavitt authors this commentary which may include information and statistical data obtained from and/or prepared by third party sources that FIA deems reliable but in no way does FIA guarantee the accuracy or completeness. All such third party information and statistical data contained herein is subject to change without notice. Nothing herein constitutes legal, tax or investment advice or any recommendation that any security, portfolio of securities, or investment strategy is suitable for any specific person. Personal investment advice can only be rendered after the engagement of FIA for services, execution of required documentation, including receipt of required disclosures. All investments involve risk and past performance is no guarantee of future results. For registration information on FIA, please go to https://adviserinfo.sec.gov/ and search by our firm name or by our CRD #175083. Advisory services are only offered to clients or prospective clients where FIA and its representatives are properly licensed or exempted.



