

Weekly Market Commentary

The holiday-shortened week saw the S&P 500 eclipse 5500 and hit its 31st all-time high of the year.  Volumes were relatively light until Friday, when $5.5 trillion in derivatives expired and rolled in the next contract month.  Several investment banks increased their year-end price targets for the S&P 500 even as hedge funds moved to a more cautious stance.  Narrowing market breadth was also notable this week, as were lackluster results from about 21 billion in corporate bond sales.  However, a 20-year US Treasury auction saw strong demand.  Central bank policy and rhetoric came throughout the week.  The BOE left its policy rate unchanged but signaled a cut in August.  The Swiss National Bank surprised the street with a 25 basis point cut.  NVidia’s market cap surpassed Microsoft’s but regressed on volatile trade in the second half of the week.  Investors will pay attention to end-of-the-quarter rebalancing as they look to the second half of the year.  We expect an uptick of volatility as investors recalibrate expectations for global monetary policy and corporate earnings while assessing the ramifications of this year’s Presidential election.
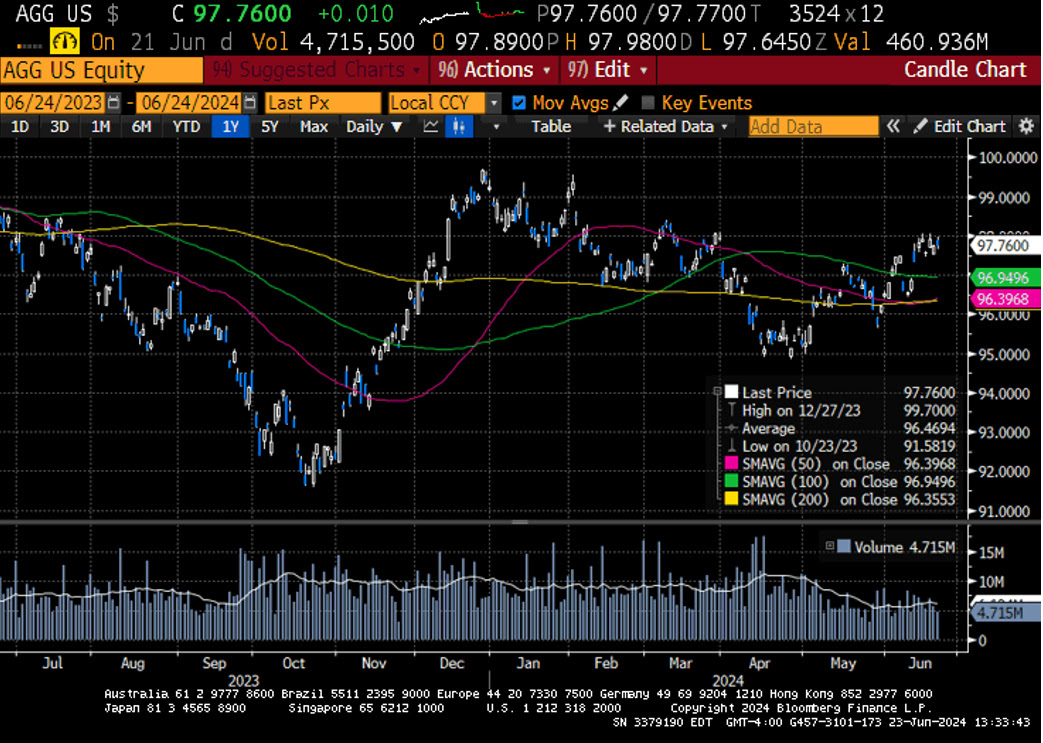
The S&P 500 gained 0.8%, the Dow outperformed with a 1.5% advance, the NASDAQ added 0.2%, and the Russell 2000 rose 0.7%.  Notably, the Bloomberg Aggregate Bond Index is now flat for the year.  US Treasuries came off a bit this week.  The 2-year yield increased by five basis points to 4.73%, while the 10-year yield rose by five basis points to close at 4.26%.  The US Dollar index traded 0.3% higher.  The Dollar/Yen cross closed the week at 159.53 as the Euro/Dollar cross fell to 1.0695.  Oil prices gained $2.63 to close at $80.70 a barrel.  Gold prices fell by $18 to $2331.60 an Oz.  Copper prices fell by $0.06 to $4.44 per Lb.  Of note, Bitcoin was sold over the week to close at $64,250.
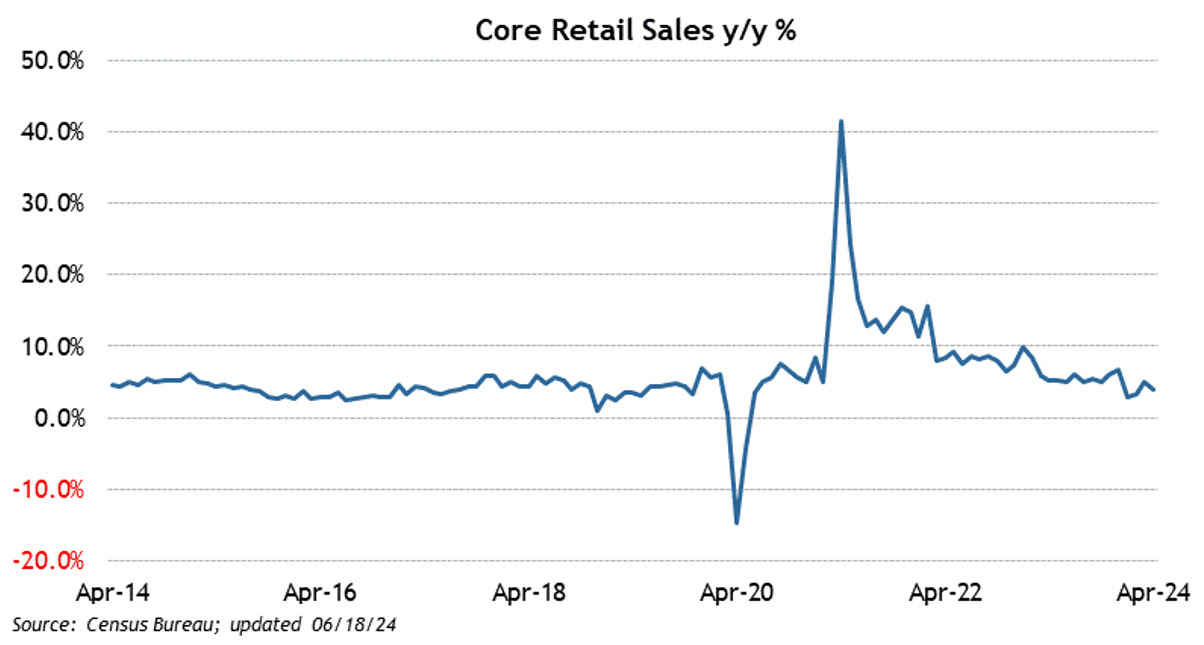
The economic calendar was quite busy.  May retail sales were weaker than anticipated and the prior month’s data was revised lower.  The headline number was 0.1% versus the expectation of 0.3%.  The Ex-autos figure came in at -0.1% versus the estimate of 0.2%.  Housing data showed continued weakness.  Housing Starts came in at 1277k versus the consensus estimate of 1375k.  Building Permits came in at 1386k, while the street was looking for 1445k.  May Existing Home Sales came in at 4.11m, just shy of the 4.14m expected.  Global Manufacturing PMIs generally were weaker than expected, especially in Europe.  However, US Manufacturing data was stronger than expected, and services showed the fastest pace of expansion in 2 years. Initial claims fell by 5k to 238k, while Continuing claims increased by 15k to 1.828M.

Investment advisory services offered through Foundations Investment Advisors, LLC (“FIA”), an SEC registered investment adviser. FIA’s Darren Leavitt authors this commentary which may include information and statistical data obtained from and/or prepared by third party sources that FIA deems reliable but in no way does FIA guarantee the accuracy or completeness.  All such third party information and statistical data contained herein is subject to change without notice.  Nothing herein constitutes legal, tax or investment advice or any recommendation that any security, portfolio of securities, or investment strategy is suitable for any specific person.  Personal investment advice can only be rendered after the engagement of FIA for services, execution of required documentation, including receipt of required disclosures.  All investments involve risk and past performance is no guarantee of future results. For registration information on FIA, please go to https://adviserinfo.sec.gov/ and search by our firm name or by our CRD #175083. Advisory services are only offered to clients or prospective clients where FIA and its representatives are properly licensed or exempted.


Share:

View the Latest Commentaries:

Weekly Market Commentary

U.S. financial markets logged weekly gains as Wall Street shook off tech sector volatility and focused on stabilizing energy prices. Despite severe global bond market pressure, the S&P 500 rose 1.15% and hit an all-time high this week; the Dow Jones Industrial Average added 0.93%, and the Nasdaq Composite climbed 0.64%, hovering near all-time records.  The Russell 2000 fell by 0.9%.  Yields across the US yield curve fell after forging new highs for the year.  The 2-year note fell three basis points to 4.79%, while the 10-year yield fell four basis points to close at 5.24%.  Oil prices increased by just under 1% to close the week at $91.92 a barrel.  Gold prices rose 1.3%, or $53.60, to $4216.20 per ounce.  Silver prices increased 1% to $61.05 per ounce.  Copper rose fourteen cents to $6.69 per Lb.  Bitcoin’s price fell 2.35% to $82,800.  VIX, a volatility measure, fell 3% to

Weekly Market Commentary

As we move from the third quarter into the fourth, investors have a lot to consider in this crazy market.  US equities finished the week mixed in volatile trade.  A standstill in negotiations between the US and Iran pushed oil prices higher early in the week, but the realization that oil moving through the Strait of Hormuz is now at pre-war levels, along with news that the G7 would release 100 million gallons of oil and diesel from reserves, pushed oil prices lower.  This comes as the Pentagon is considering deploying 10,000 more troops and an additional aircraft carrier to the Gulf.  Elevated oil prices have kept inflation concerns front and center, but a cooler-than-expected PCE report, a weaker-than-anticipated Employment Situation report, and dovish remarks from Fed President Williams and Vice Chair Jefferson moved the probability of a rate hike in October from over 70% to less than 25%.  Interestingly,

Weekly Market Commentary

Markets finished the week mixed as interest rates increased across the yield curve.  Oil prices swung significantly during the week as reports suggested the US and Iran were close to a deal to reopen the Strait of Hormuz.  This weekend, President Trump rejected the proposed deal, with reports suggesting the US will resume more aggressive military operations after the Midterms.  This is likely to send oil prices higher on Monday and, with it, increase inflation expectations.  President Trump’s meeting with Chinese leader Xi offered little change to the current political stance.  The two countries delayed increasing tariffs until January 2027, and the two leaders are scheduled to meet two more times before year-end.   Additionally, the two leaders appear to be on the same page on AI development and pushed back on slowing it but agreed that safeguards should be put in place.  Debate continues over AI development and its safeguards. 

Weekly Market Commentary

It was a volatile week on Wall Street as traders assessed monetary policy decisions from several central banks, including the Federal Reserve.  The Fed did, as expected, raise its policy rate by 25 basis points to 3.75%-4.00%, but Fed Chairman Warsh’s very hawkish tone increased the likelihood of three more rate hikes starting later this year and in the first half of 2027.  The Fed Chair offered no forward guidance but did provide the dot plot from the other committee members.  The yield curve flattened on the announcement, with the front end of the curve selling off more than longer-duration Treasuries. Notably, the Bank of England kept its policy rate in place while the Bank of Japan raised its policy rate by 25 basis points.  A more dovish signal from the BOJ’s president sent the Yen lower.  Bottom line: the US economy is strong, employment looks stable, and inflation remains

