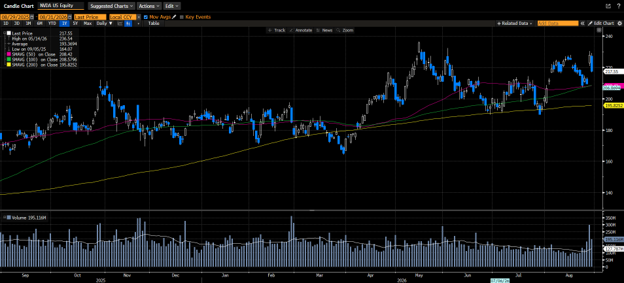

The holiday-shortened week on Wall Street was volatile. The last of first-quarter earnings continued to influence the markets. Earning results from the retailers were mixed as BestBuy, Footlocker, Nordstrom’s, and Costco’s shares increased on better-than-expected results, while Kohl’s and Dollar General’s results produced sharp sell-offs. Investors continue to keenly watch consumer spending behaviors for clues on the health of the economy. Key economic data released over the week suggested the consumer may be starting to tighten their purse strings. Large Technology issues came under pressure as Salesforce’s sales growth projections were well below the street’s estimates and from disappointing guidance from Dell and MongoDB. A visible rebalance throughout the week from growth to value was evident and given the outperformance of growth over value year to date makes some sense to us. Similarly, a move away from mega caps and into other areas of the market could be seen in the divergence in the market cap-weighted S&P 500 index performance relative to the equal cap-weighted S&P 500 index. Other significant news on the tape included the merger agreement between ConocoPhillips and Marathon for a value of $22.5 billion, the government funding of a bird-flu vaccine produced by Moderna, and former President Donald Trump being found guilty on all 34 charges by a Manhattan jury.

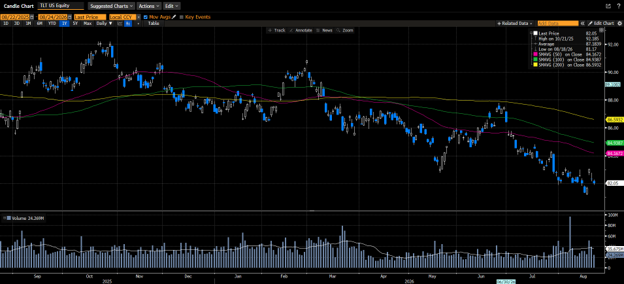
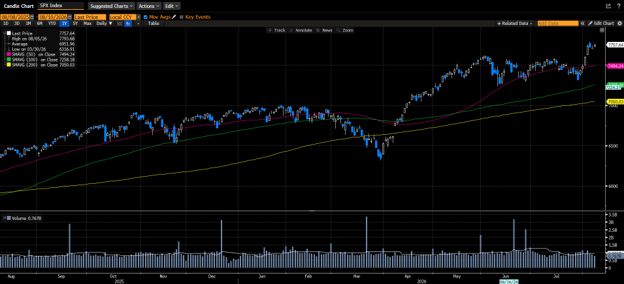
The S&P 500 lost 0.5% for the week but was up 5% in May and 10.6% year-to-date. The Dow gave back 1%, was up 2.4% in May and 2.6% year-to-date. The NASDAQ shed 1.1% over the week but gained 7.3% in May and has gained 11.5% for the year. The Russell 2000 was unchanged on the week, was up 4.7% in May, and 2.1% for the year. US Treasuries endured another volatile week as auctions in 2-year, 5-year, and 7-year notes saw tepid demand. However, the mixed economic data released in the back half of the week put a bid into Treasuries. The 2-year yield fell by four basis points on the week and fell by sixteen in May, ending the month at 4.89%. The 10-year yield decreased by four basis points to 4.51%, and was down eighteen basis points in May.
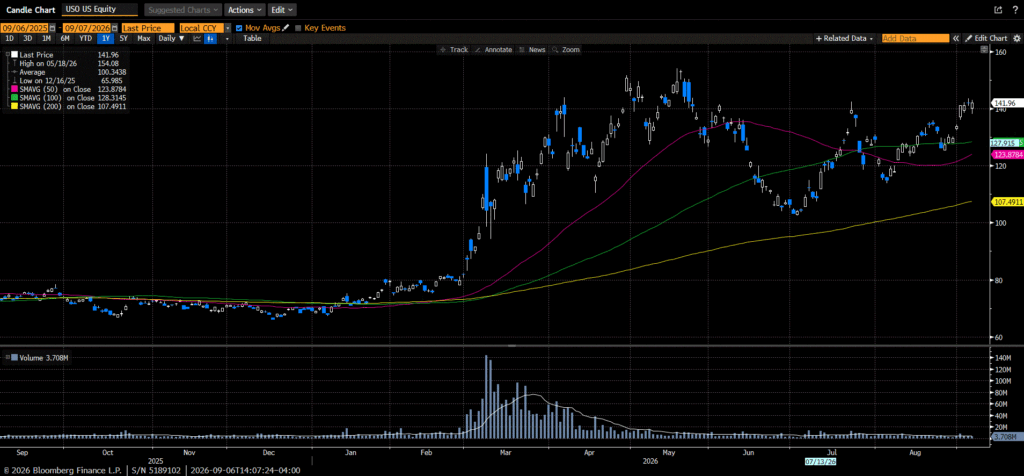
Oil prices fell nearly 1% on the week and closed off 5.5% or $4.47 in May to $77.08 a barrel. Gold prices fell by $10.80 on the week to close at $2345.60 an Oz. Copper continued to come off its most recent highs, losing $0.15 and closing at $4.60 per Lb. The Dollar index lost 1.6% in May and closed the week at 104.65.

The Fed’s preferred measure of inflation, the PCE, was the highlight in a busy economic data calendar. The headline reading showed an increase of 0.3%, which was in line with estimates. On a year-over-year basis, it came in at 2.7%, unchanged from the March figure. The Core reading that excludes food and energy rose 0.2%, slightly less than the expected 0.3%. The Core reading came in at 2.8% year-over-year and has been stuck at that level for the last three months. Personal Income rose by 0.3%, in line with expectations, while Personal Spending was a bit lighter than expected at 0.2% versus 0.3%. The 2nd look at Q1 GDP came in at 1.3%, down from the first look, of 1.6%. A deceleration of consumer spending was the culprit for the majority of the downtick, coming in at 2% versus 2.5%, causing some additional concerns about the health of the consumer. The GDP deflator came in at 3%, down from 3.1% in the prior reading. May Consumer Confidence came in much stronger than expected on good feelings about the labor market. The reading came in at 102, up from the prior reading of 97. Initial Claims increased by 3k to 219k, while Continuing Claims increased by 4k to 1.791 million.
Investment advisory services offered through Foundations Investment Advisors, LLC (“FIA”), an SEC registered investment adviser. FIA’s Darren Leavitt authors this commentary which may include information and statistical data obtained from and/or prepared by third party sources that FIA deems reliable but in no way does FIA guarantee the accuracy or completeness. All such third party information and statistical data contained herein is subject to change without notice. Nothing herein constitutes legal, tax or investment advice or any recommendation that any security, portfolio of securities, or investment strategy is suitable for any specific person. Personal investment advice can only be rendered after the engagement of FIA for services, execution of required documentation, including receipt of required disclosures. All investments involve risk and past performance is no guarantee of future results. For registration information on FIA, please go to https://adviserinfo.sec.gov/ and search by our firm name or by our CRD #175083. Advisory services are only offered to clients or prospective clients where FIA and its representatives are properly licensed or exempted.