Weekly Market Commentary

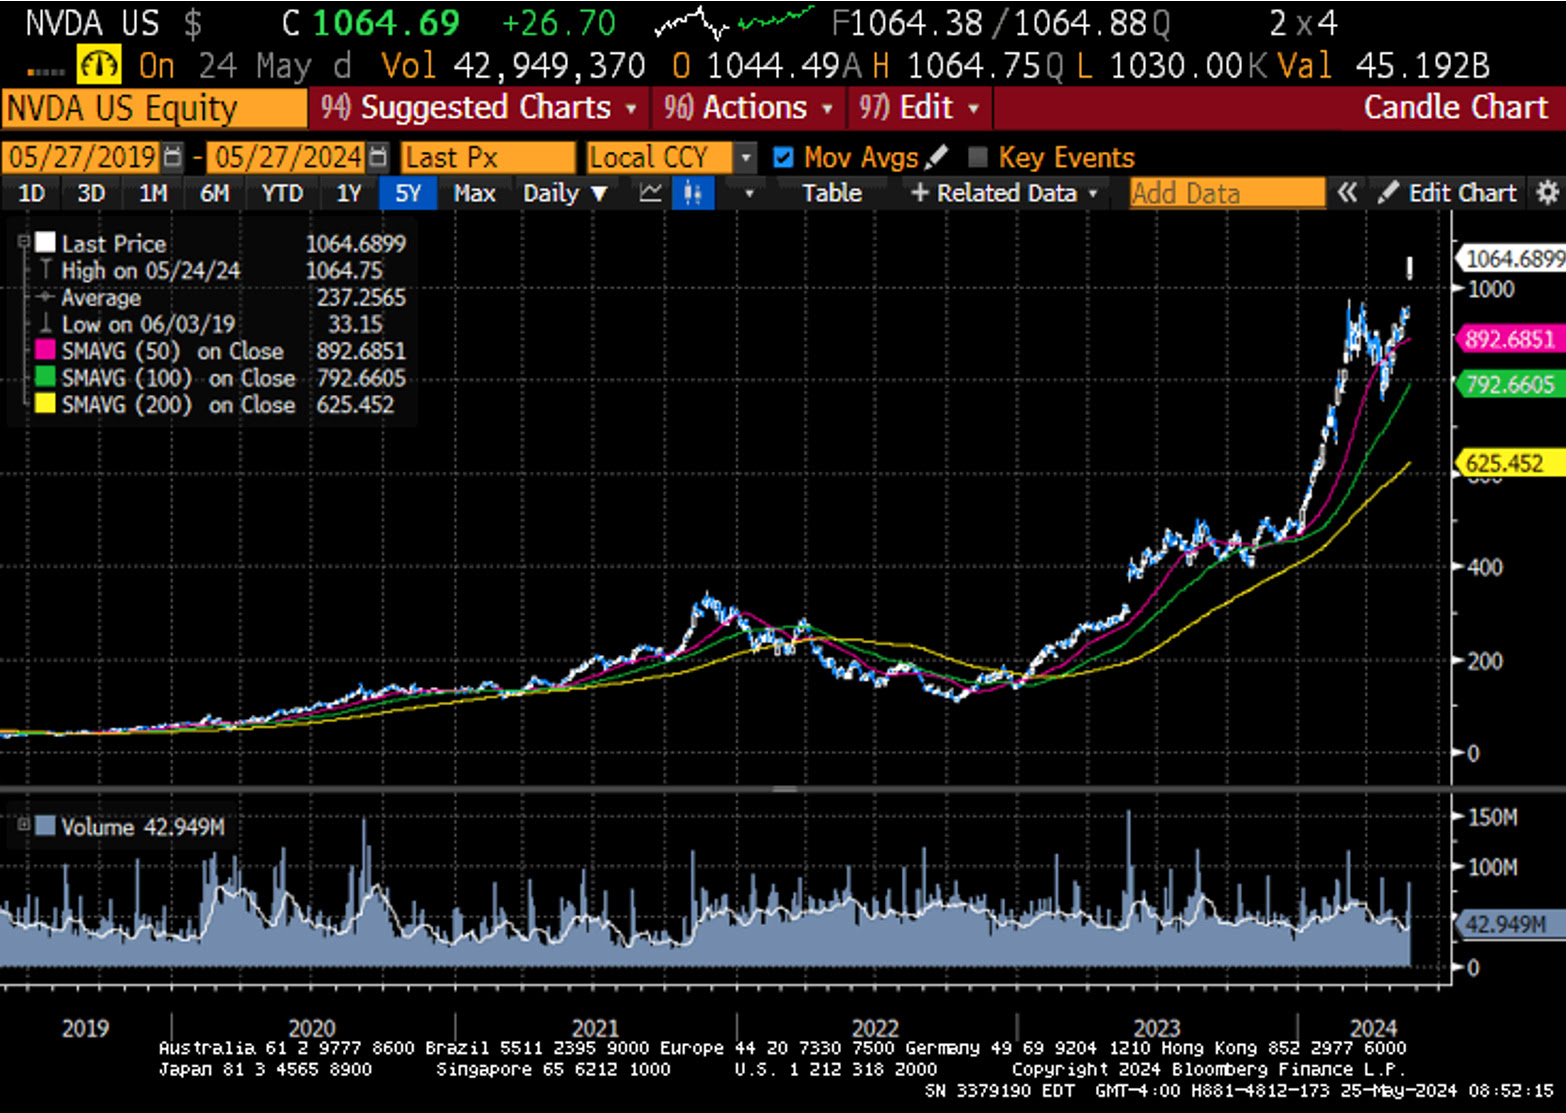
Financial markets ended the week with mixed results. All eyes this week were on AI darling NVidia, which posted better-than-expected Q1 results and provided guidance above the consensus estimates. The company also increased its dividend by 150% and announced a ten-for-one stock split, sending shares higher by 9%.   Arguably, NVidia’s results were the most important Q1 earnings report of this earnings season and confirmed that the AI trend is still intact, which portends continued capital expenditures on AI by global corporations.  Markets also took cues from the FOMC minutes that reinforced the notion of higher for longer but noted that most on the committee thought that current monetary policy was sufficiently restrictive.  Next week, investors will get a look at the Fed’s preferred measure of inflation, the PCE, which is likely to show continued moderation in inflation.
The S&P 500 closed the week unchanged, while the NASDAQ gained 1.5% and established a new all-time high.  The Dow lost 2.4%, and the Russell 2000 shed 1.3%. US Treasuries sold off across the curve, with shorter-tenured paper taking the bulk of the losses.  The 2-year yield increased by thirteen basis points to 4.95%, while the 10-year yield rose by four basis points to 4.46%.  The 2-10 spread compressed to -49 basis points.  Commodities were weak across the board as some of the most recent sizeable gains in precious metals regressed.  West Texas Intermediate crude prices declined by $1.73 or 2.2% to close at $77.81 a barrel.  Gold prices fell by $83.30 to close at $2334.80 an Oz.  Copper prices lost $0.30 or 5.4% to $4.75 per Lb.  The US Dollar index added 0.3% to close at 104.69.
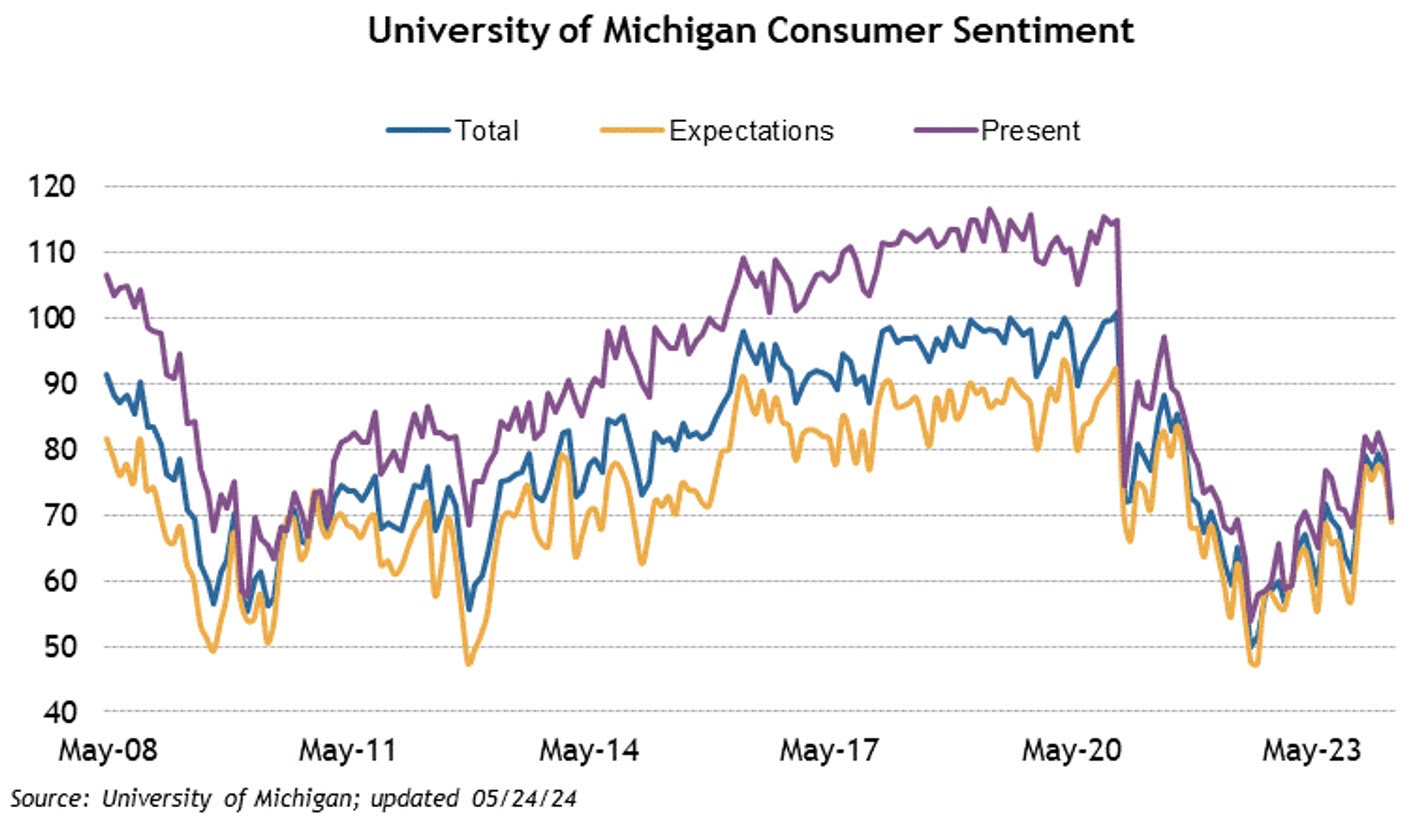
The economic calendar was relatively quiet this week, but there were a couple of notable data sets. The preliminary S&P Global Manufacturing and Services PMIs showed increased expansion.  The manufacturing PMI came in at 50.09 versus an expected 50 print, while the services PMI came in at 54.8 versus the expected reading of 51.3.  This increased activity bolstered the idea that the Fed will continue to hold rates higher for longer and pushed out expectations of a rate cut.  There is currently a 49.4% probability assigned to a rate cut in September, a 61.6% chance in November, and an 81.6% probability for a December rate cut.  The final reading of the University of Michigan’s Consumer Sentiment index came in at 69.1 versus an expected 67.6.  This was the lowest reading in 5 months but showed consumer’s inflation expectations moderating over the next year and in the long run.

Investment advisory services offered through Foundations Investment Advisors, LLC (“FIA”), an SEC registered investment adviser. FIA’s Darren Leavitt authors this commentary which may include information and statistical data obtained from and/or prepared by third party sources that FIA deems reliable but in no way does FIA guarantee the accuracy or completeness.  All such third party information and statistical data contained herein is subject to change without notice.  Nothing herein constitutes legal, tax or investment advice or any recommendation that any security, portfolio of securities, or investment strategy is suitable for any specific person.  Personal investment advice can only be rendered after the engagement of FIA for services, execution of required documentation, including receipt of required disclosures.  All investments involve risk and past performance is no guarantee of future results. For registration information on FIA, please go to https://adviserinfo.sec.gov/ and search by our firm name or by our CRD #175083. Advisory services are only offered to clients or prospective clients where FIA and its representatives are properly licensed or exempted.
Share:

View the Latest Commentaries:

Weekly Market Commentary

Markets finished the week mixed as investors assessed the escalation of tensions between the US and Iran and recalibrated expectations of Federal Reserve monetary policy.  The week started with sharp declines after the US hit targets on an island in the Strait of Hormuz that were ready to launch mines into the strait.  Iran then countered with drone attacks on Jordan and the UAE.  On Saturday, there were reports that the US had hit three Iranian cargo ships after Iran fired ballistic missiles at two US Navy ships.  The news sent oil prices higher, which in turn raised inflation concerns.   Markets settled down mid-week after Dell reported a solid quarter and after dovish comments made by Fed Bank of New York President John Williams.  Markets moved higher on Thursday after Fed Governor Waller said he would be willing to hold rates steady if price pressures continue to ease and noted

Weekly Market Commentary

Markets ended the week mixed as investors assessed the implications of the US economic isolation of Iran, the fallout of increased tariffs on Canada, Nvidia Q2 earnings results, and the Fed Chairman’s speech at the Kansas City Federal Reserve’s Economic Symposium in Jackson Hole. Oh yeah, we were also treated to a slightly hotter print of the Fed’s preferred inflation measure, the PCE. On Monday, Treasury Secretary Bessent laid out a plan to isolate economic activity with Iran.  The plan, dubbed Economic D-day, promised economic punishment to any country doing business with Iran and suggested that, in the coming days, there will be announcements and actions taken against several entities that have worked alongside Iran to evade economic sanctions.  The US and Iran both said they would not return to the MOU signed in June, as negotiations have stalled.  Oil traded lower this week on reports that 10 million barrels

Weekly Market Commentary

US equity markets took a step back last week in what turned out to be a very busy week.  Increased yields on the long end of the curve prompted Treasury Secretary Scott Bessent to double buybacks of 10- to 30-year US Treasuries in an effort to temper the rise in rates.  The move was met with a rally in both bonds and stocks; however, it was short-lived, with much of the gains being given back within a day of the announcement.  A global debasement narrative has emerged as the US deficit topped $40 trillion.  The US Dollar sold off to levels not seen since May, while precious metals and Bitcoin prices soared.  Interestingly, the correlation between Gold and Bitcoin is the highest since Covid, following massive liquidity injections by global governments.  It’s notable that several other developed markets are facing similar pressure on their sovereign debt, including Japan, the UK,

Weekly Market Commentary

The S&P 500 forged a new all-time high as investors recalibrated interest-rate-hike expectations after an in-line print of the Consumer Price Index and a cooler-than-expected print of the Producer Price Index.  The probability of a rate hike in September fell to 32% from 55% a week ago. Interestingly, the short end of the US curve advanced while longer-dated Treasuries declined over the week amid concerns about the widening US deficit.  Treasury auctions this week were met with tepid demand and saw the 10-year and 30-year priced at yields not seen since 2007 and 2001, respectively. Oil prices rose as the US-Iran war continues while negotiations appear to be at an impasse.   The US signaled it would continue its blockade of Iranian ports to inflict economic pressure while Iran and the Houthis continued to attack cargo ships in the Strait of Hormuz and the Red Sea.  Second-quarter earnings continued to roll