

Weekly Market Commentary

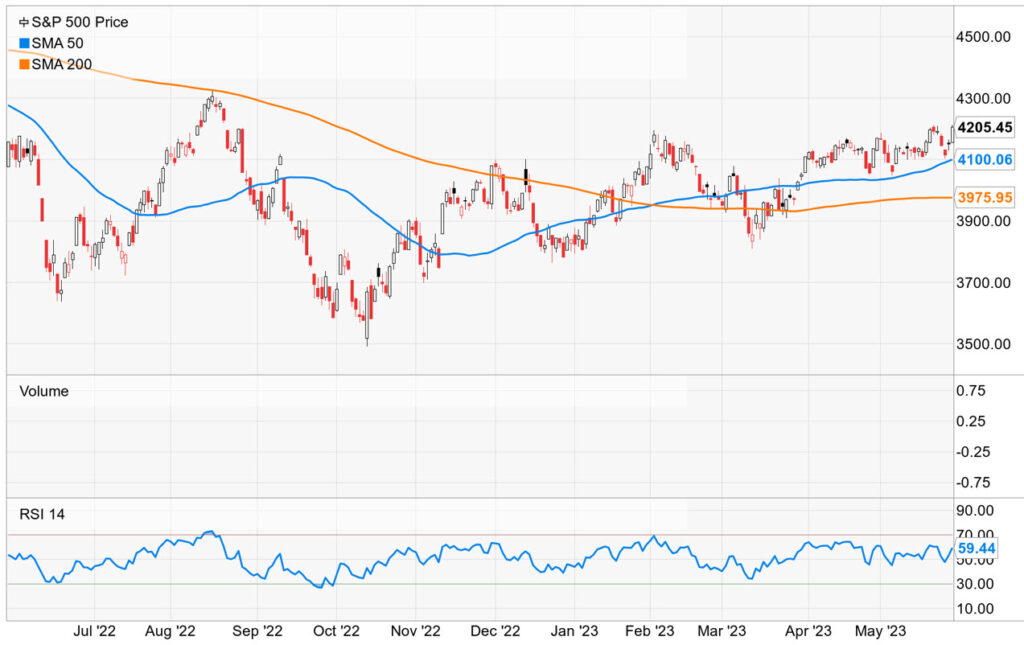
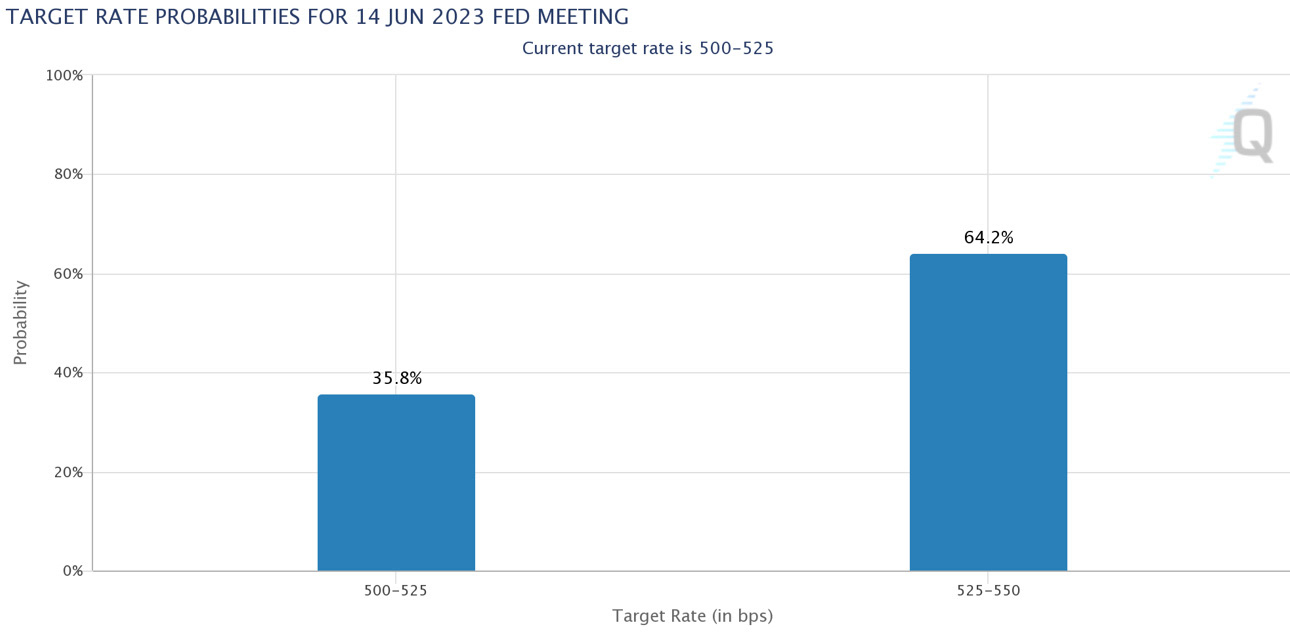
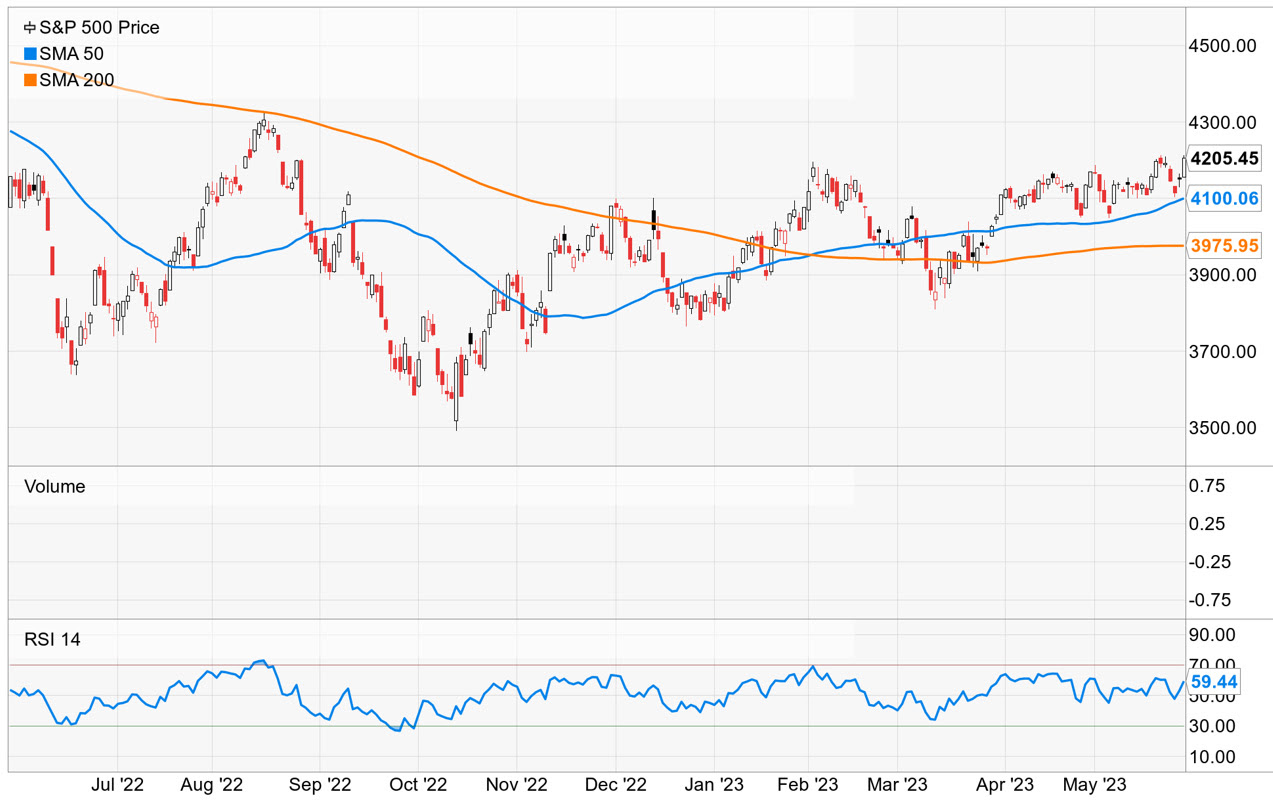
As investors awaited news from the debt ceiling negotiations, markets continued to ebb and flow.  The S&P 500 continued to trade range-bound, oscillating between 4100 and 4200.  Fed rhetoric continued to open the door for another set of interest rate hikes and hammered the front end of the yield curve.   Economic data reported during the week seemed to substantiate the need for more rate hikes as Fed Fund Futures saw the probability of a June rate hike move to 64.2% from nearly zero three weeks ago.   A blowout quarter and an optimistic outlook from semiconductor chip designer NVidia highlighted the last stint of first-quarter earnings.  The stellar report prompted another rally in mega-cap technology issues that have accounted for most of this year’s market returns.
The S&P 500 gained 0.3%, the Dow lost 1%, the NASDAQ increased by 2.5%, and the Russell 2000 traded unchanged. US Treasuries endured another steep selloff as yields across the curve rose—bond price fall when their yields increase.  The 2-year yield increased by twenty-nine basis points to 4.56% while the 10-year yield rose by eleven to 3.8%.

Oil prices increased by 1.1% or $0.79 to close at $72.55 a barrel.  Gold prices fell 1.9% or $38.40 to $1943.4. Copper prices continued to struggle, closing down $0.06 to $3.67 an Lb.

The dollar strengthened against the Yen, Euro, British Pound, and Yuan.  China voiced concern over the recent appreciation of the US Dollar relative to its currency.
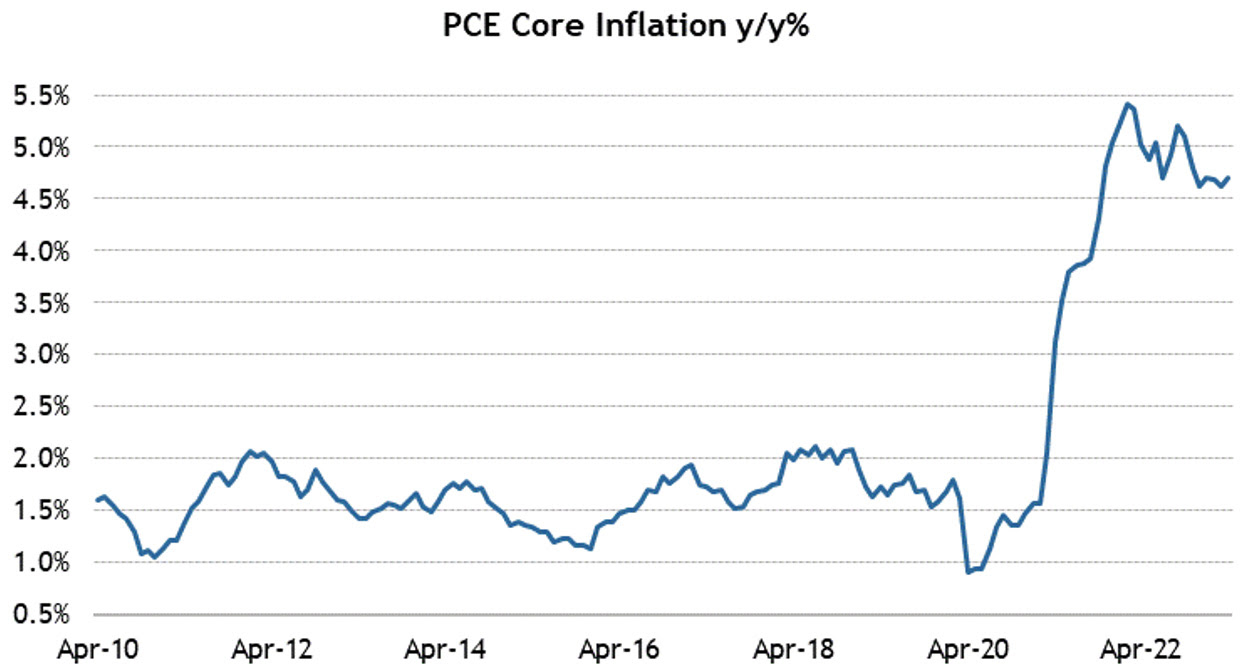
US economic data reported for the week showed a resilient economy.  First quarter GDP figures came in strong than expected at 1.3% growth versus the expectation of 1.1%.  German GDP contracted for the second quarter in a row, putting the country into a technical recession defined as two consecutive quarters of negative growth.  The US labor market only showed 229k initial jobless claims; the street was looking for 250k.  Continuing Claims also fell to 1794k from 1799k in the prior week.  Personal Spending increased to 0.8% in April, higher than the anticipated 0.4%, highlighting the strength of the consumer. Personal income increased to 0.4%. The Fed’s preferred measure of inflation, PCE, came in hotter than expected.  The headline number came in at 0.4% versus the estimated 0.3% month-over-month and was up 4.4% year-over-year from March’s 4.2%.  The Core reading was also up 0.4% over March and increased 4.7% annually. New Home Sales increased to 683K, better than the expected 670.  Consumer Sentiment also ticked a bit higher in May, with the University of Michigan’s data showing a reading of 59.2, up from the last preliminary reading of 58.
Investment advisory services offered through Foundations Investment Advisors, LLC (“FIA”), an SEC registered investment adviser. FIA’s Darren Leavitt authors this commentary which may include information and statistical data obtained from and/or prepared by third party sources that FIA deems reliable but in no way does FIA guarantee the accuracy or completeness.  All such third party information and statistical data contained herein is subject to change without notice.  Nothing herein constitutes legal, tax or investment advice or any recommendation that any security, portfolio of securities, or investment strategy is suitable for any specific person.  Personal investment advice can only be rendered after the engagement of FIA for services, execution of required documentation, including receipt of required disclosures.  All investments involve risk and past performance is no guarantee of future results. For registration information on FIA, please go to https://adviserinfo.sec.gov/ and search by our firm name or by our CRD #175083. Advisory services are only offered to clients or prospective clients where FIA and its representatives are properly licensed or exempted.


Share:

View the Latest Commentaries:

Weekly Market Commentary

As we move from the third quarter into the fourth, investors have a lot to consider in this crazy market.  US equities finished the week mixed in volatile trade.  A standstill in negotiations between the US and Iran pushed oil prices higher early in the week, but the realization that oil moving through the Strait of Hormuz is now at pre-war levels, along with news that the G7 would release 100 million gallons of oil and diesel from reserves, pushed oil prices lower.  This comes as the Pentagon is considering deploying 10,000 more troops and an additional aircraft carrier to the Gulf.  Elevated oil prices have kept inflation concerns front and center, but a cooler-than-expected PCE report, a weaker-than-anticipated Employment Situation report, and dovish remarks from Fed President Williams and Vice Chair Jefferson moved the probability of a rate hike in October from over 70% to less than 25%.  Interestingly,

Weekly Market Commentary

Markets finished the week mixed as interest rates increased across the yield curve.  Oil prices swung significantly during the week as reports suggested the US and Iran were close to a deal to reopen the Strait of Hormuz.  This weekend, President Trump rejected the proposed deal, with reports suggesting the US will resume more aggressive military operations after the Midterms.  This is likely to send oil prices higher on Monday and, with it, increase inflation expectations.  President Trump’s meeting with Chinese leader Xi offered little change to the current political stance.  The two countries delayed increasing tariffs until January 2027, and the two leaders are scheduled to meet two more times before year-end.   Additionally, the two leaders appear to be on the same page on AI development and pushed back on slowing it but agreed that safeguards should be put in place.  Debate continues over AI development and its safeguards. 

Weekly Market Commentary

It was a volatile week on Wall Street as traders assessed monetary policy decisions from several central banks, including the Federal Reserve.  The Fed did, as expected, raise its policy rate by 25 basis points to 3.75%-4.00%, but Fed Chairman Warsh’s very hawkish tone increased the likelihood of three more rate hikes starting later this year and in the first half of 2027.  The Fed Chair offered no forward guidance but did provide the dot plot from the other committee members.  The yield curve flattened on the announcement, with the front end of the curve selling off more than longer-duration Treasuries. Notably, the Bank of England kept its policy rate in place while the Bank of Japan raised its policy rate by 25 basis points.  A more dovish signal from the BOJ’s president sent the Yen lower.  Bottom line: the US economy is strong, employment looks stable, and inflation remains

Weekly Market Commentary

US equity markets fell in the holiday-shortened week as oil prices surpassed $100 a barrel, raising inflation concerns and pushing interest rates higher.  Additionally, elevated inflation data announced during the week increased the likelihood that the Federal Reserve would raise its policy rate by 25 basis points.  Several Gulf nations announced Friday that they would meet with Iranian officials this weekend to ease tensions, and on Sunday Tehran announced it would decide whether to open part of the Strait of Hormuz, but details of the opening were limited.  This followed Saudi Arabia’s announcement that it had shut down the oil pipeline used to circumvent the Strait. The S&P 500 fell 0.78%, the Dow gave back 1.56%, the NASDAQ declined 0.64%, and the Russell 2000 decreased by 2.39%.  US Treasuries suffered losses across the curve, with the front end of the curve getting hit hardest.  The 2-year yield increased by twenty-six

