Weekly Market Commentary

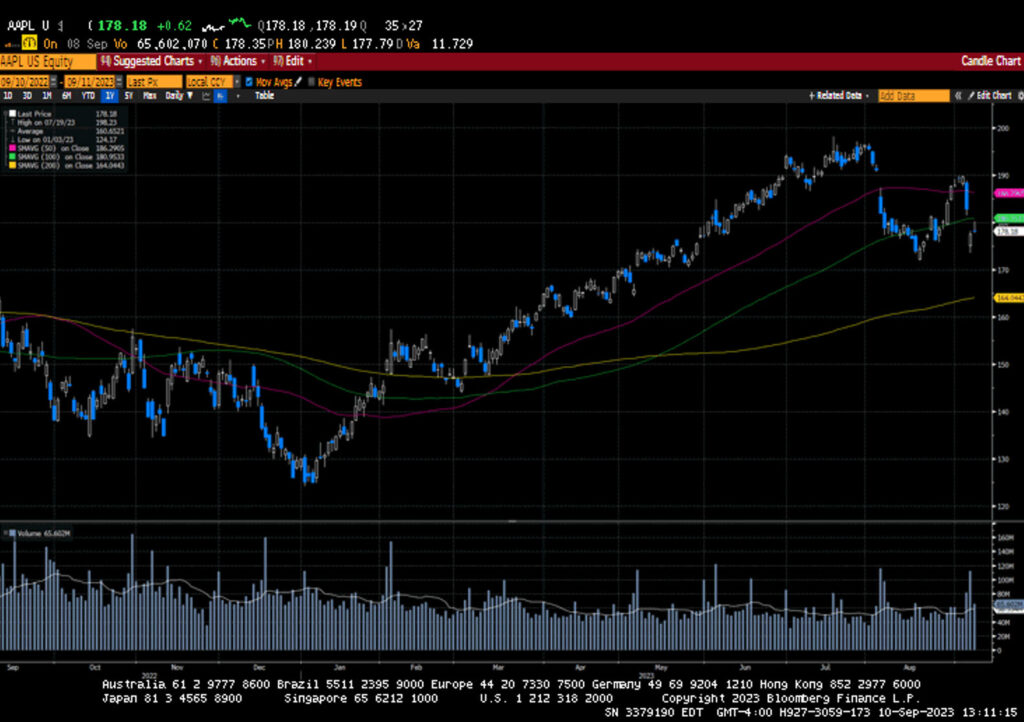
The holiday-shortened week ended with losses for both US equities and Treasuries.  Apple shares tumbled on the news that the Chinese government would ban the use of the iPhone at government agencies at all levels of government.  The news comes in front of Apple’s new product release scheduled for September 12th.   Shares of Apple fell 6% on the week and other large-cap technology issues fell in tandem.  The ban on exporting technology to China may well have entered into a new phase with China taking similar measures against other multinational companies.  The consequences of protectionism and on shoring were prominent themes for investors last week and will likely be another variable for investors to consider.
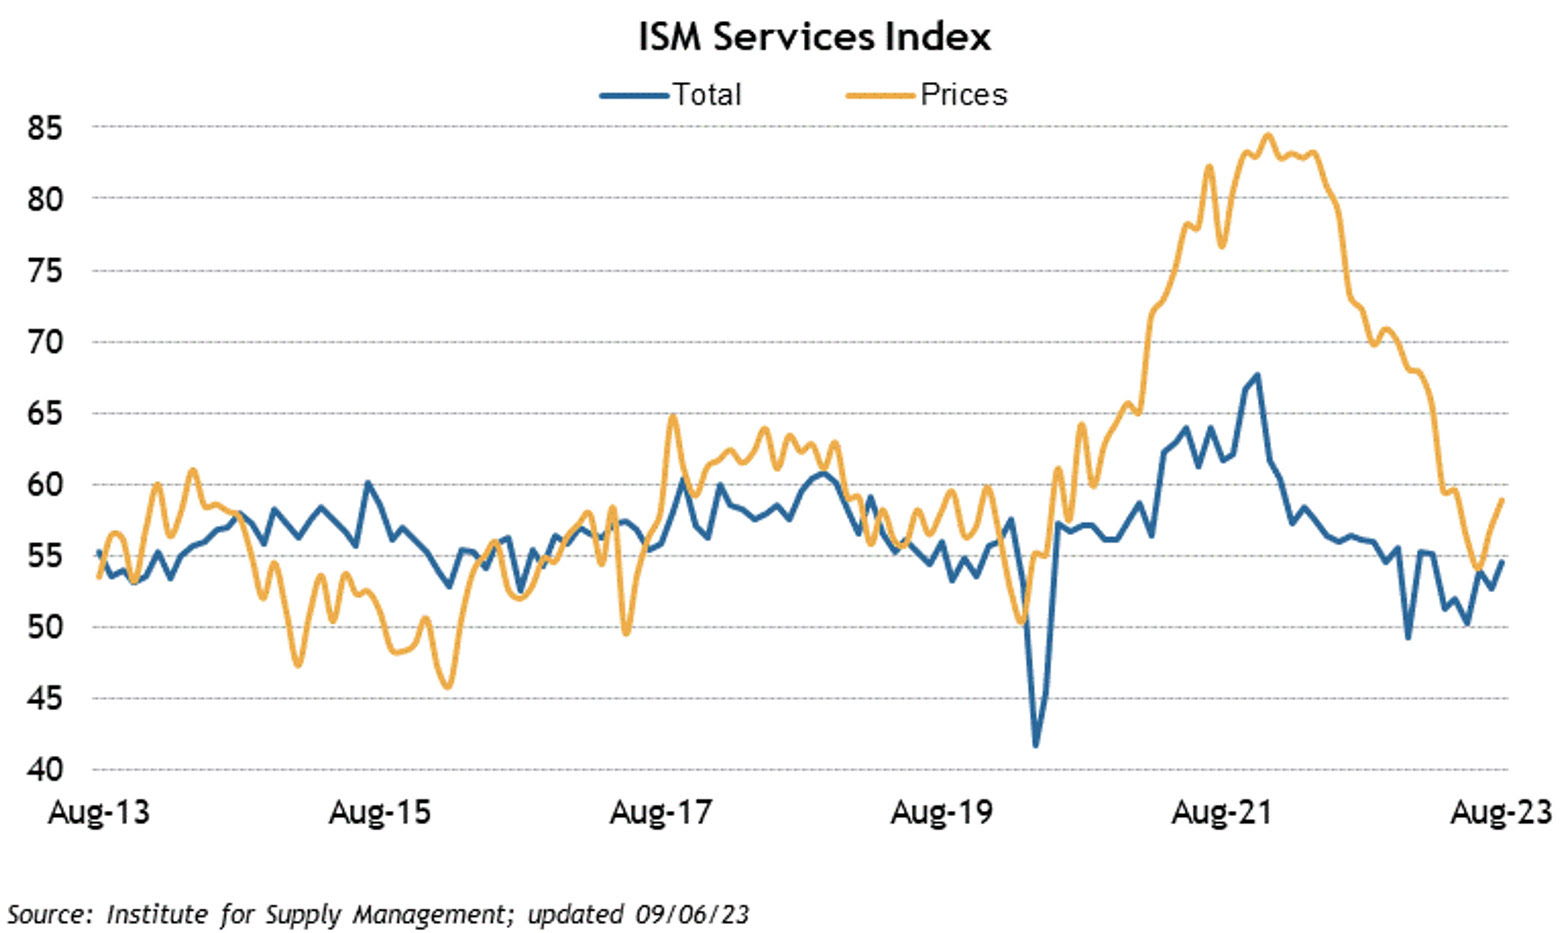
Oil prices advanced again on the news that Russia and Saudi would continue to curtail their production of Crude through at least the end of the year.  The higher level of fuel costs has caused concern on the inflation front.  The US Consumer Price Index will be released this week and it’s widely expected that the headline number will tick higher from the prior reading due to elevated oil prices.  ISM Services reported during the week also showed that the services sector of the economy expanded at a higher rate and the prices in services ticked higher as well.  Sticky inflation data and an increase in the supply of debt coming to the market from the Treasury and Corporate America pushed yields higher across the curve.  This week the Treasury will auction off nearly 100 Billion in 3-year, 10-year, and 30-year paper.
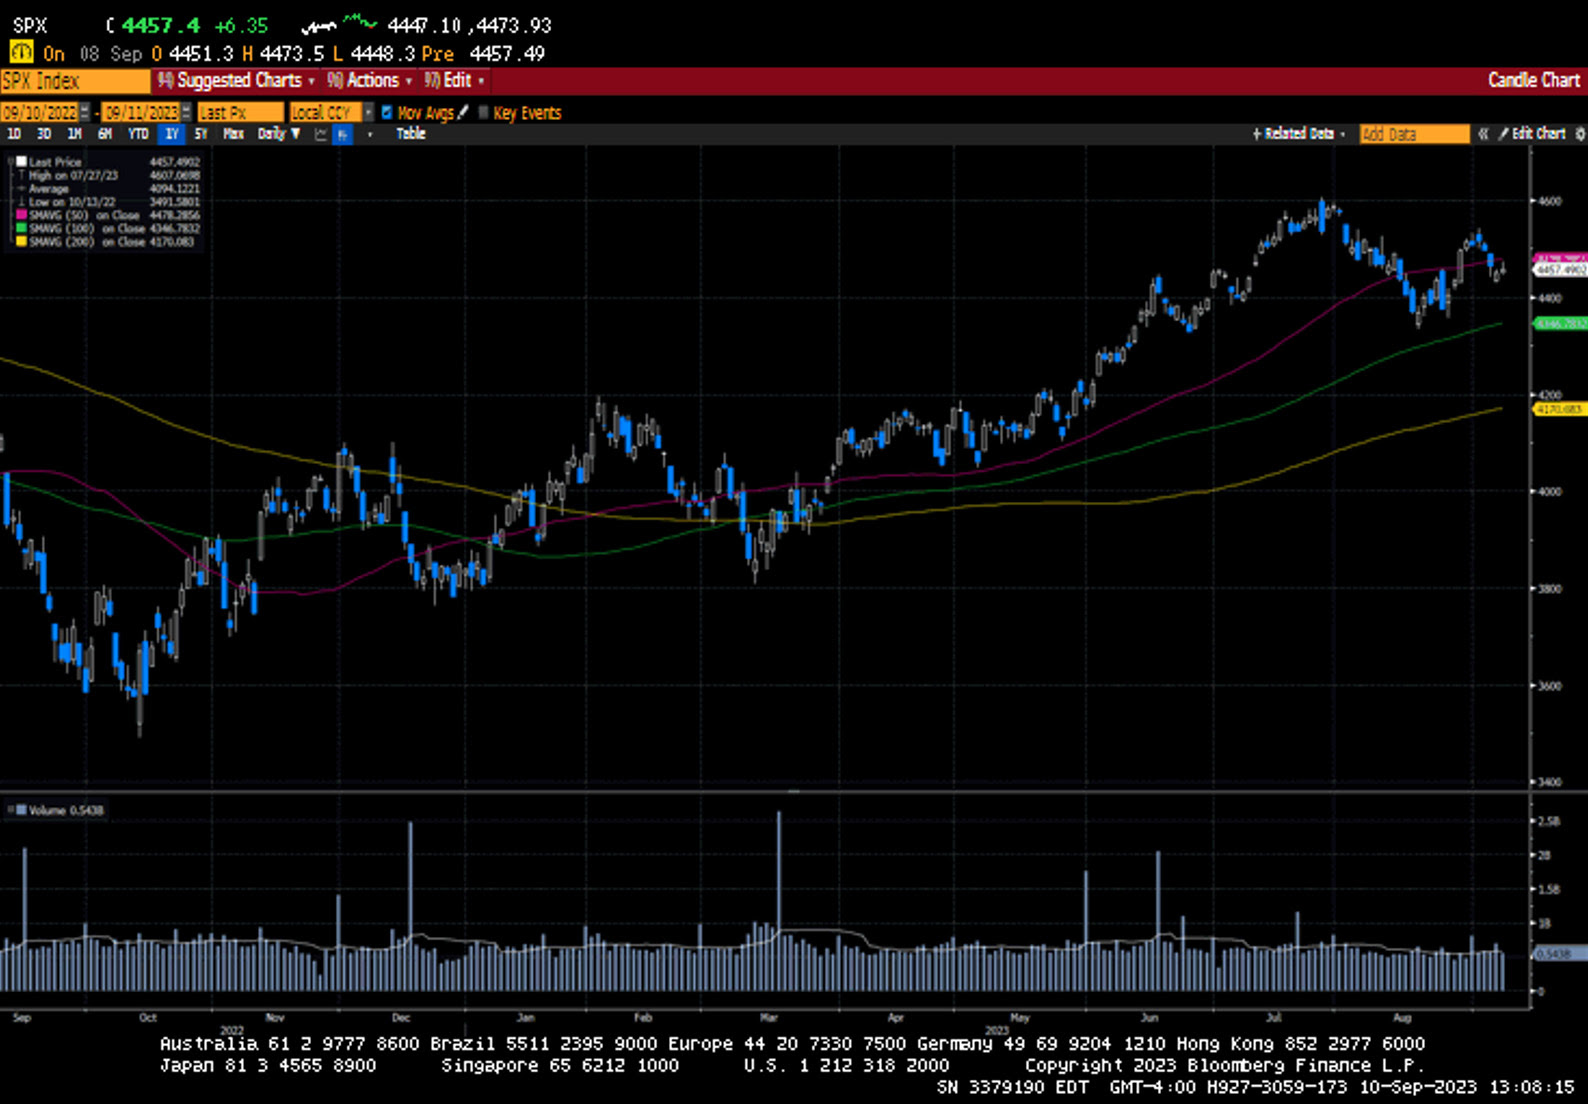
The S&P 500 lost 1.3%, the Dow gave up 0.7%, the NASDAQ fell 1.9%, and the Russell 2000 led declines with a loss of 3.6%.  Of note, the S&P 500 fell below its 50-day moving average but was able to hold 4400 a key level that investors will continue to watch.  The yield curve shifted higher across the curve.  The 2-year yield increased by nine basis points to 4.97%, as the 10-year yield rose by the same amount to 4.26%.  Oil prices increased by $1.92 or 2.2%, closing at $87.47 a barrel.  Gold prices fell by $23.80 to close at $1943.30 an Oz. Copper prices fell 3.3% to 3.72 a Lb.  The US Dollar continued to be strong despite intervention measures from the Bank of Japan and the People’s Bank of China.  The Dollar/Yen closed at 147.87, the Euro/Dollar closed the week below 1.07, and the Dollar/Yuan closed at 1.3667.

Investment advisory services offered through Foundations Investment Advisors, LLC (“FIA”), an SEC registered investment adviser. FIA’s Darren Leavitt authors this commentary which may include information and statistical data obtained from and/or prepared by third party sources that FIA deems reliable but in no way does FIA guarantee the accuracy or completeness.  All such third party information and statistical data contained herein is subject to change without notice.  Nothing herein constitutes legal, tax or investment advice or any recommendation that any security, portfolio of securities, or investment strategy is suitable for any specific person.  Personal investment advice can only be rendered after the engagement of FIA for services, execution of required documentation, including receipt of required disclosures.  All investments involve risk and past performance is no guarantee of future results. For registration information on FIA, please go to https://adviserinfo.sec.gov/ and search by our firm name or by our CRD #175083. Advisory services are only offered to clients or prospective clients where FIA and its representatives are properly licensed or exempted.
Share:

View the Latest Commentaries:

Weekly Market Commentary

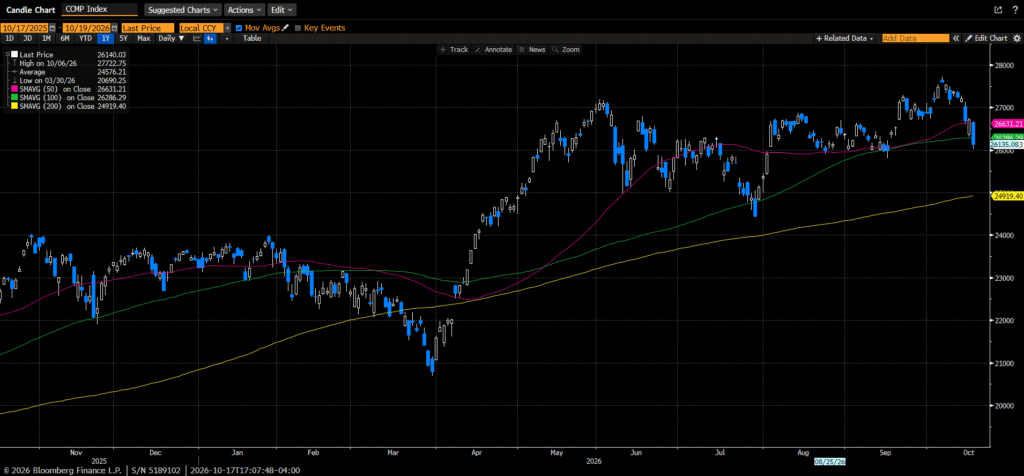
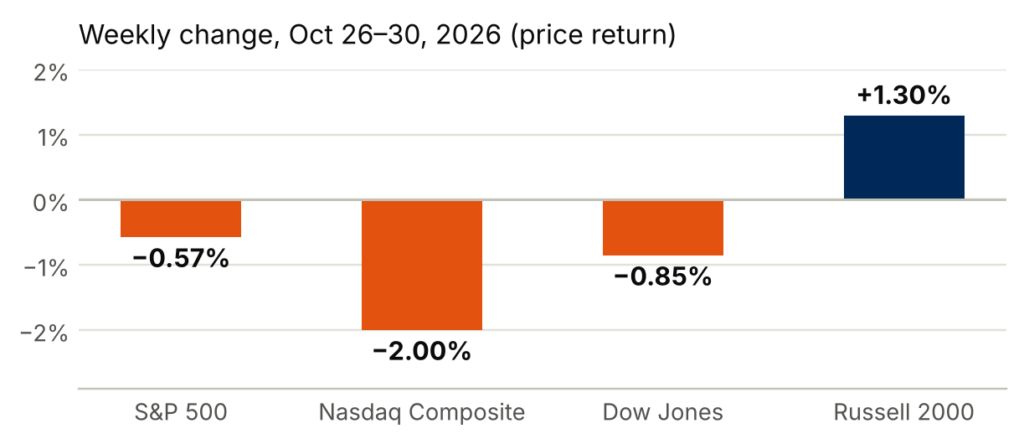
U.S. stocks climbed through Wednesday, then gave it all back. The S&P 500 slipped 0.6% and the Nasdaq fell 2.0%, each for a third straight weekly decline, and the Dow lost 0.9%. Small caps held up, with the Russell 2000 up 1.3%. The turn came after Alphabet and Amazon reported results that renewed doubts about the payoff from AI spending, and Intel’s warning sent its shares down nearly 29% on Friday. The Nasdaq fell 2.9% on Friday, its worst day since June 5. The Fed held, with two dissents for a hike. The policy rate stays at 3.75%–4.00% (10–2 vote). Traders price roughly a 76%–85% chance of a quarter-point hike on December 9. Big Tech spending drew a harsh verdict. Alphabet had its worst day in more than 20 years; Amazon’s trailing free cash flow turned to a record $42.4 billion outflow. Microsoft, helped by 48% Azure growth, held up.

Weekly Market Commentary

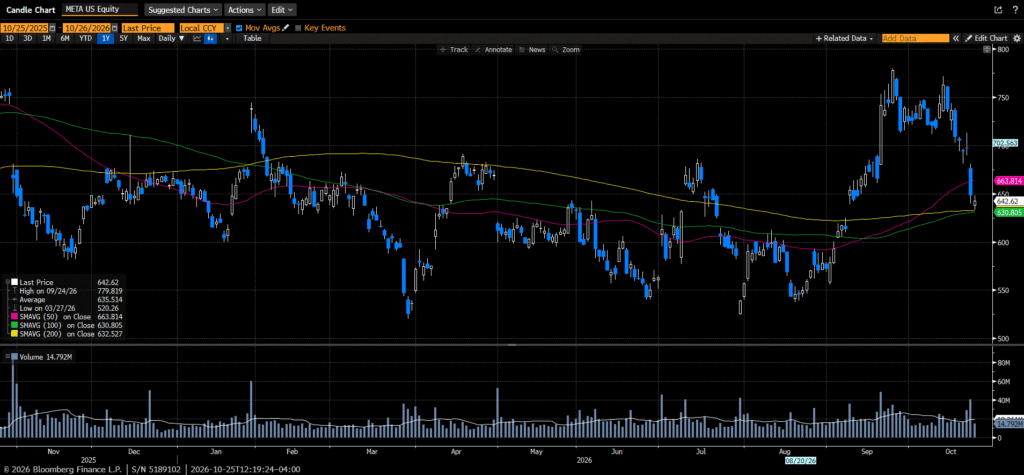
It was another volatile week on Wall Street, with US indices ending the week with mixed results.  Ongoing concerns about AI financing and its return on investment continued after Meta announced its 3rd-quarter results.  The company beat estimates and offered solid guidance.  However, its higher AI capital expenditures, lower margins, and negative free cash flow fueled a sell-off in AI infrastructure names.   Investors rotated into energy, staples, healthcare, and interest rate-sensitive sectors such as small-caps, real estate, and utilities.  According to FactSet, we are about a quarter of the way through 3rd-quarter earnings.  83% of the companies that reported have beaten earnings expectations, while 66% have beaten revenue expectations.  Earnings Per Share growth for the quarter is currently an impressive 29%.  Microsoft, Google, and Amazon are set to report earnings this week. Increased hostilities between the Houthis and Saudi Arabia, along with what appears to be an inevitable escalation in

Weekly Market Commentary

It was a chaotic week on Wall Street as investors tried to interpret mixed Q3 financial results, a spike in oil prices, sharp swings in yields across the curve, hotter-than-expected inflation data, dovish tones from central bankers, and renewed concerns about the AI infrastructure buildout, its use of credit, and the timing of when or if there will be a return on investment.  Q3 earnings started in earnest, with several large banks reporting.  JP Morgan, Morgan Stanley, Goldman Sachs, and Citi Bank reported solid results, while Bank of America and Wells Fargo reported disappointing results.  Equity trading drove bank outperformance this quarter, while fixed income results lagged.  Solid results from Taiwan Semiconductor were met with selling as the Semiconductor sector continued to come under pressure.  The Philadelphia Semiconductor index has declined eight consecutive days, a setup not seen since 2008.  Part of the losses were attributed to an advancement in

Weekly Market Commentary

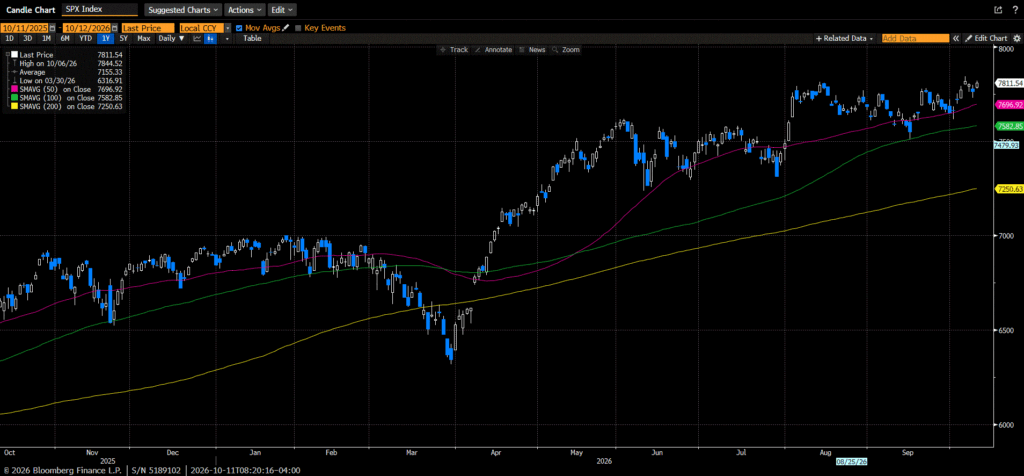
U.S. financial markets logged weekly gains as Wall Street shook off tech sector volatility and focused on stabilizing energy prices. Despite severe global bond market pressure, the S&P 500 rose 1.15% and hit an all-time high this week; the Dow Jones Industrial Average added 0.93%, and the Nasdaq Composite climbed 0.64%, hovering near all-time records.  The Russell 2000 fell by 0.9%.  Yields across the US yield curve fell after forging new highs for the year.  The 2-year note fell three basis points to 4.79%, while the 10-year yield fell four basis points to close at 5.24%.  Oil prices increased by just under 1% to close the week at $91.92 a barrel.  Gold prices rose 1.3%, or $53.60, to $4216.20 per ounce.  Silver prices increased 1% to $61.05 per ounce.  Copper rose fourteen cents to $6.69 per Lb.  Bitcoin’s price fell 2.35% to $82,800.  VIX, a volatility measure, fell 3% to