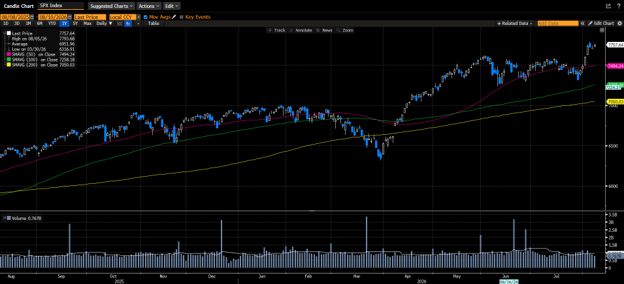
Equity markets faced another wave of selling as the S&P 500 went into correction territory, down 10.13% from the end of July. Investors saw some relief from the bond market, but trade in Sovereign debt continued to lack a safe-haven bid quality and instead traded as rates would continue to be higher for longer. That sentiment was reinforced by the European Central Bank when they left their policy rate unchanged but telegraphed that restrictive policy would be in tack for the foreseeable future. Goldman Sachs came out after the policy meeting and suggested that the ECB is done tightening but cuts will not be coming until the third quarter of 2024.
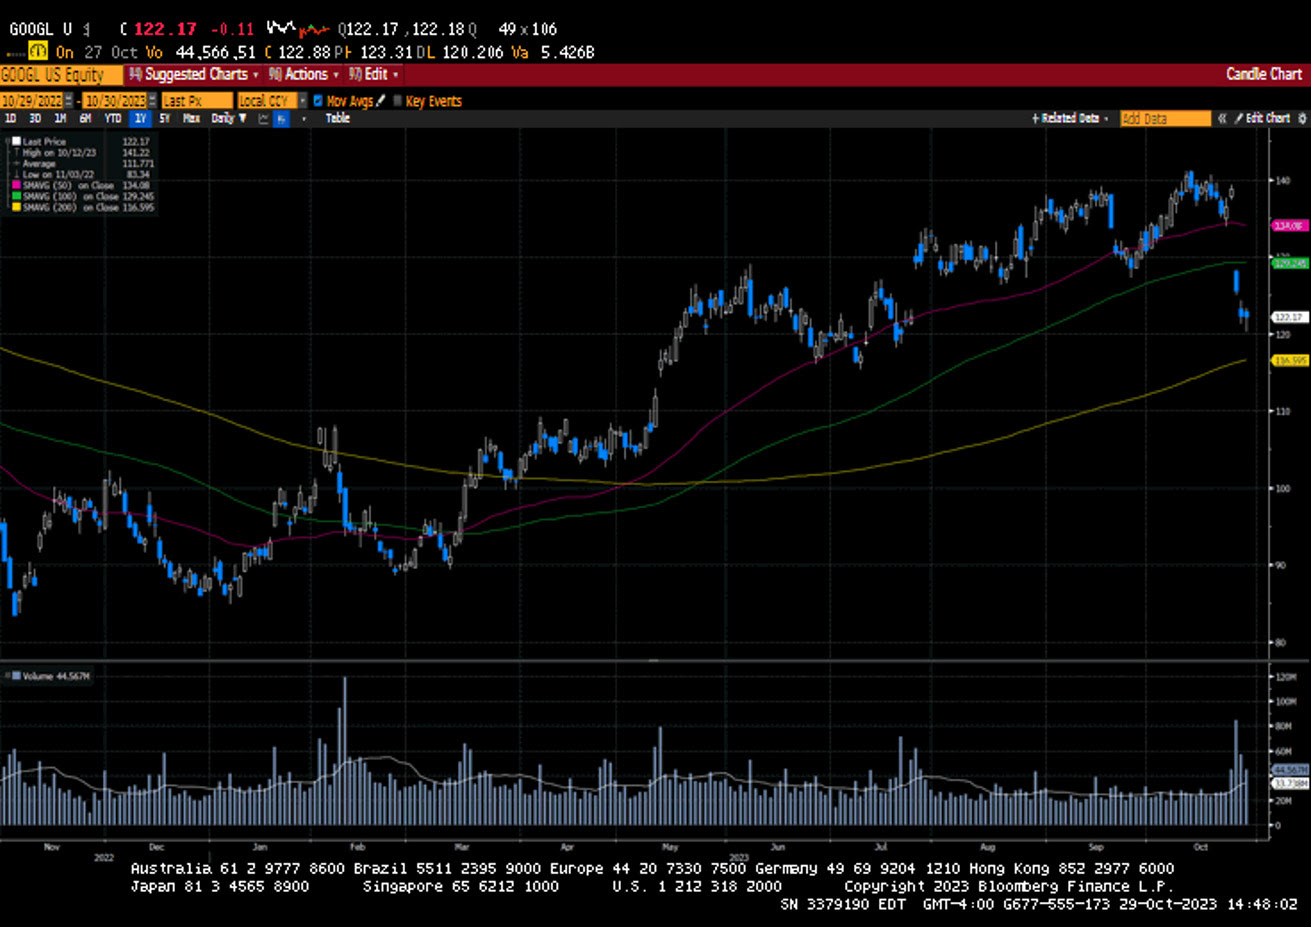
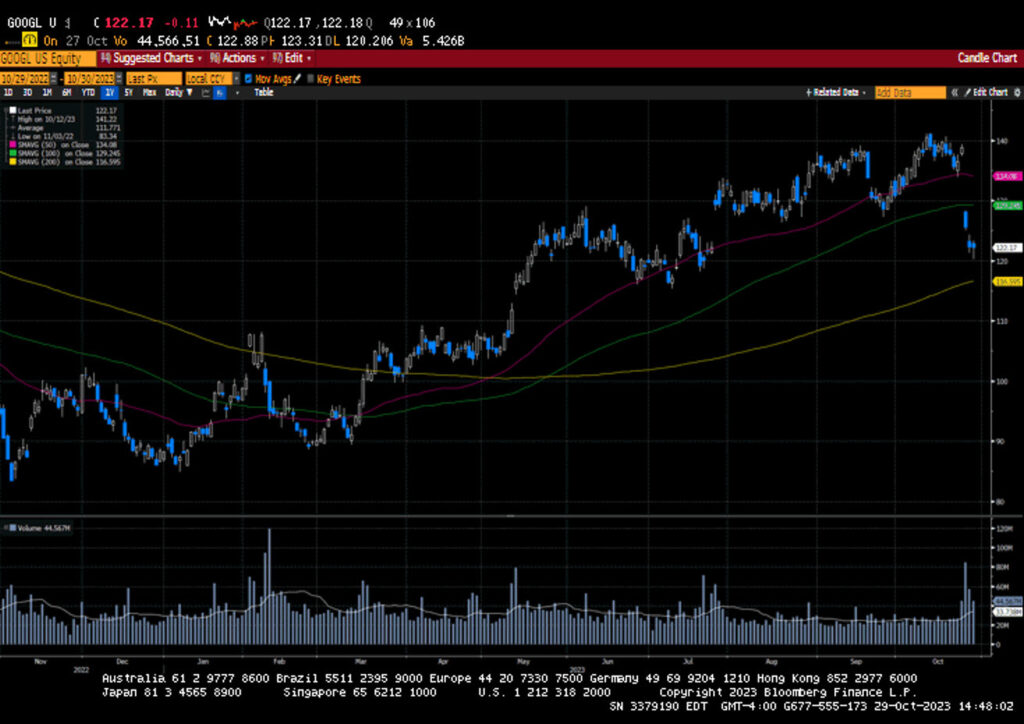
The Federal Reserve will meet this week, where it is widely expected that they will keep rates unchanged at 5.25%-5.50%. Currently, there is only a 19.2% chance that the Fed will raise rates again this year. Again, that safe-haven bid was not present in the bond market this week, even as tensions in the Middle East ramped up. The US destroyed two Iranian targets in Syria as Israel sent tactical troops into Gaza, seemingly to prepare for a much larger ground campaign. The conflict continues to be top of mind for investors as politicians search for a solution. The US House of Representatives elected a new Speaker of the House. Representative Mike Johnson from the State of Louisiana won the Speakership and has started working on a Stop-Gap measure to keep the government running through the end of the year and also proposed a bill to provide support to Israel. Currently, funding for Ukraine has been sidelined. Q3 earnings were mixed and seemed to garner more attention this week than in the prior few weeks. Google’s cloud numbers were disappointing and sent the stock lower by 9.8% despite the rest of their business showing solid results. Microsoft and Amazon had solid quarters and did much better with their cloud service offerings. Intel surprised the street and helped propel the Semiconductor sector with solid results from a significant increase in margins. Verizon, Coca-Cola, and Raytheon posted solid numbers, while Meta, Exxon Mobil, and Chevron earnings results were disappointing.
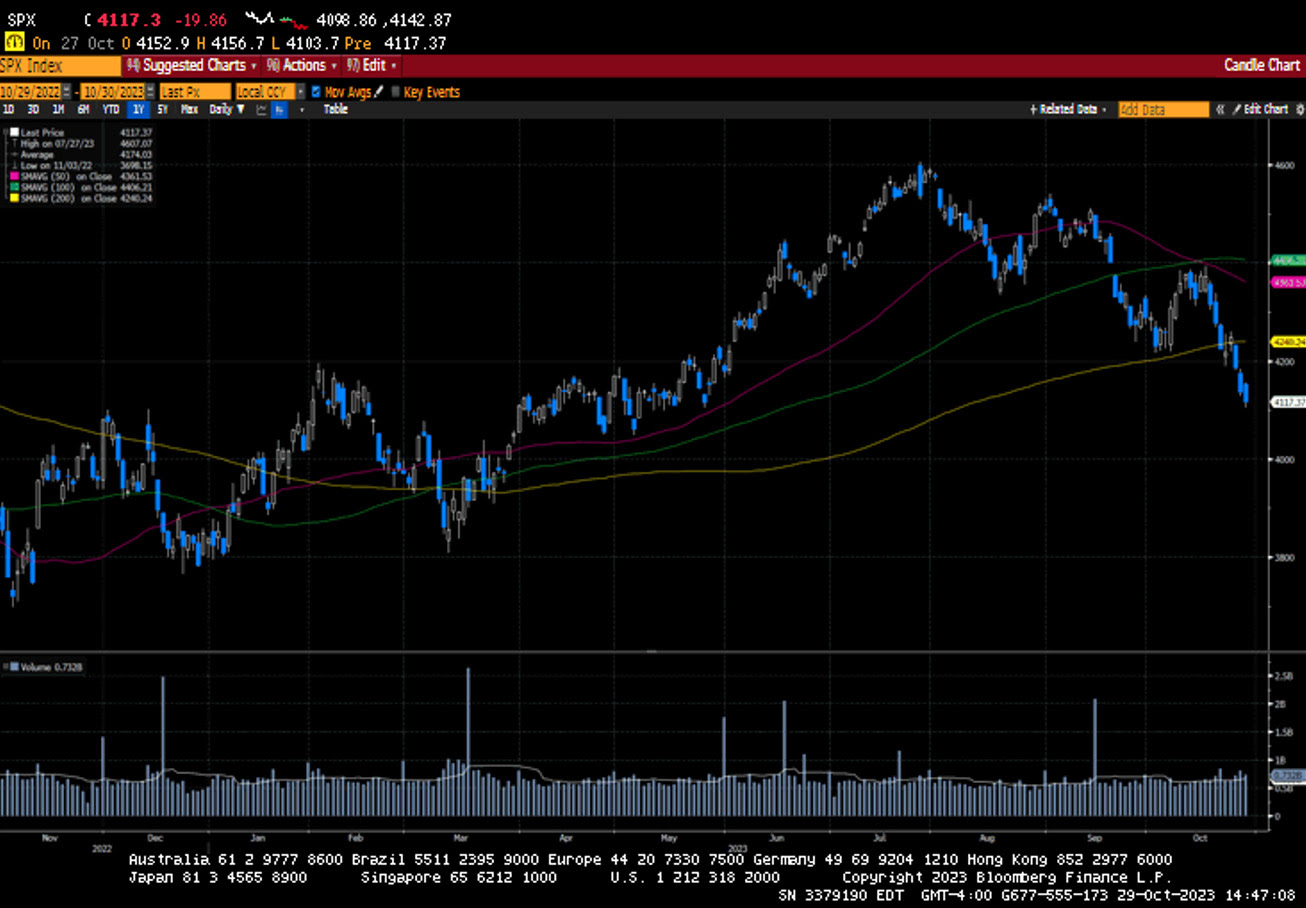
The S&P 500 lost 2.5%, the Dow gave up 2.1%, the NASDAQ fell 2.6%, and the Russell 2000 shed 2.6%. The S&P 500 equal weight, and market cap indices fell in tandem. US Treasury yields were consistently lower across the curve. The 2-year yield fell by six basis points to 5.03%, while the 10-year yield fell by seven basis points to 4.85%. Oil prices fell $2.52 or 2.8% to $85.53 a barrel. Gold prices were little changed, closing just below $2000 an Oz at $1998.70. Copper prices increased by $0.06 to 3.64 a Lb.
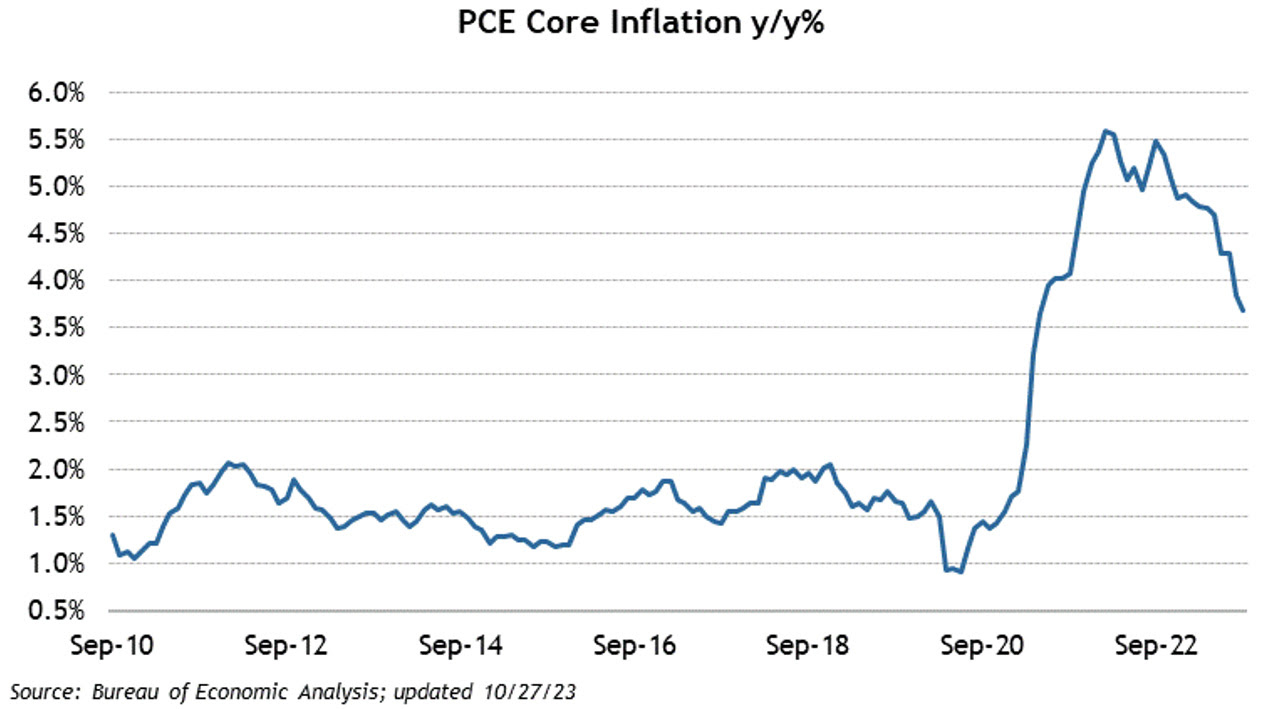
Economic data for the week included headline PCE, a little hotter than expected at 0.4% versus the estimated 0.3%. The headline number increased 3.4%, unchanged from August. Core PCE came in at 0.3%, in line with expectations, and ticked slightly lower on a year-over-year basis to 3.7% from 3.8%. Personal Income was a little shy of estimates at 0.3%, but Personal Spending came in at a robust 0.7% versus the expected 0.5%. Perhaps the most interesting reading of the week came from the first assessment of 3rd quarter GDP. The data showed the US economy growing at a 4.9% rate. Initial Jobless Claims came in at 210k, while Continuing Claims increased by 63k to 1790k.
Investment advisory services offered through Foundations Investment Advisors, LLC (“FIA”), an SEC registered investment adviser. FIA’s Darren Leavitt authors this commentary which may include information and statistical data obtained from and/or prepared by third party sources that FIA deems reliable but in no way does FIA guarantee the accuracy or completeness. All such third party information and statistical data contained herein is subject to change without notice. Nothing herein constitutes legal, tax or investment advice or any recommendation that any security, portfolio of securities, or investment strategy is suitable for any specific person. Personal investment advice can only be rendered after the engagement of FIA for services, execution of required documentation, including receipt of required disclosures. All investments involve risk and past performance is no guarantee of future results. For registration information on FIA, please go to https://adviserinfo.sec.gov/ and search by our firm name or by our CRD #175083. Advisory services are only offered to clients or prospective clients where FIA and its representatives are properly licensed or exempted.