

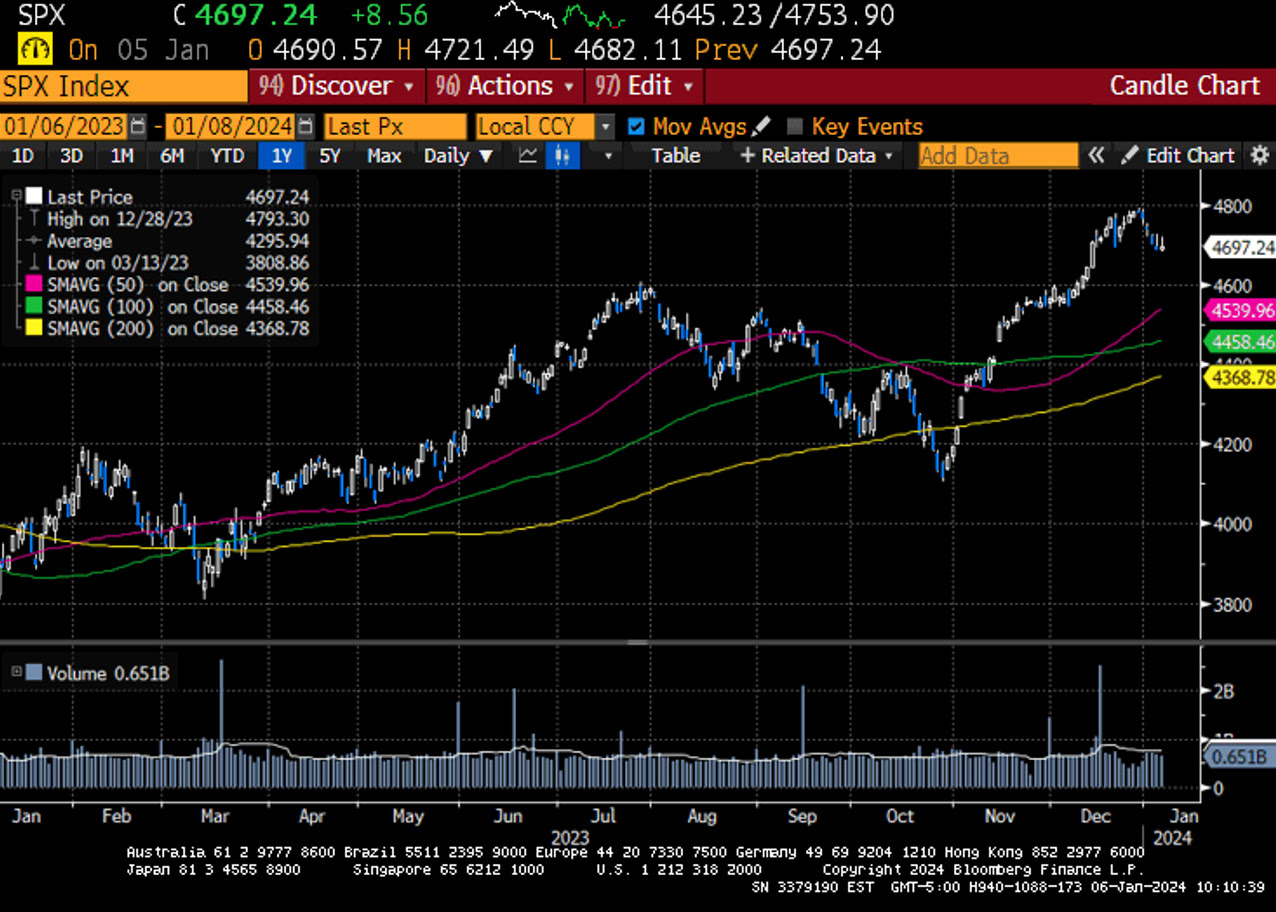
After nine weeks of gains, the market fell in the first week of trading in 2024. Interestingly, the losses incurred this week largely came from areas of the market that outperformed last year, namely growth and technology. Technically, the market was due for a pullback. Still, several factors catalyzed the sell-off this week, including multiple analyst downgrades of Apple, a more hawkish than expected tone from the Federal Open Market Committee minutes, increased geopolitical tensions in the Red Sea, and a stronger than anticipated jobs report.
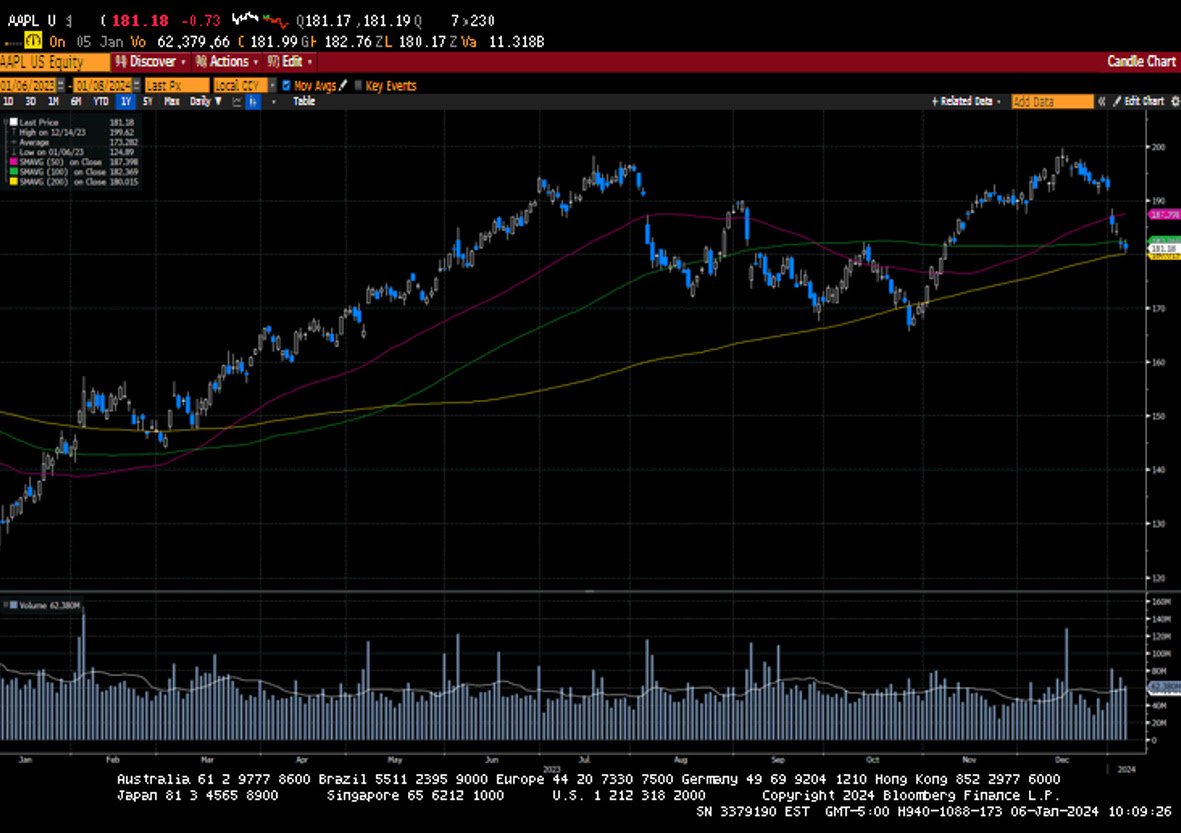
The largest company in the world, Apple, fell over 6% as Barclays and Piper Sandler downgraded their rating to underweight and neutral, respectively. Worries over higher inventories of iPhones, elevated valuations, and antitrust concerns were prominent themes in the downgrades. The sell-off hindered the mega-cap index, which lost 3% for the week.
The FOMC was watched much more intently this week as investors looked for clues on what caused Chairman J. Powell to come off as so dovish in his post-FOMC meeting Q&A, where it appeared that he did a 180-degree turn from his prior hawkish statements. The minutes provided a more balanced tone and perhaps was less dovish than the market had been looking for. That sense pulled back expectations for a March rate cut and catalyzed some selling across the yield curve.
The presence of an Iranian destroyer in the Red Sea has increased concerns that the Israel and Hamas war could be broadening out. Military strikes in Beirut that killed the Hamas leader of the West Bank, along with the bombing that killed over 100 people at a ceremony celebrating an Iranian Military official, increased tensions further. As I write, there are reports that Hezbollah has fired a barrage of rockets into Israel. This comes as Secretary of State Blinken tries to de-escalate the situation.
The S&P 500 fell by 1.5%, the Dow lost 0.6%, the NASDAQ gave back 3.3%, and the Russell 2000 shed 3.8%. US Treasuries across the curve were sold. The 2-year yield increased by fourteen basis points to close at 4.39%, while the 10-year yield increased by sixteen basis points to close at 4.04%. Oil prices increased by 2.6% or $1.89 to $73.73 a barrel. Gold prices fell by $21 to $2051.30 an Oz. Copper prices fell to $3.81 per Lb., down $0.09. Bitcoin topped 45k but then receded to close at just under 44k. The US Dollar index gained 1% this week.
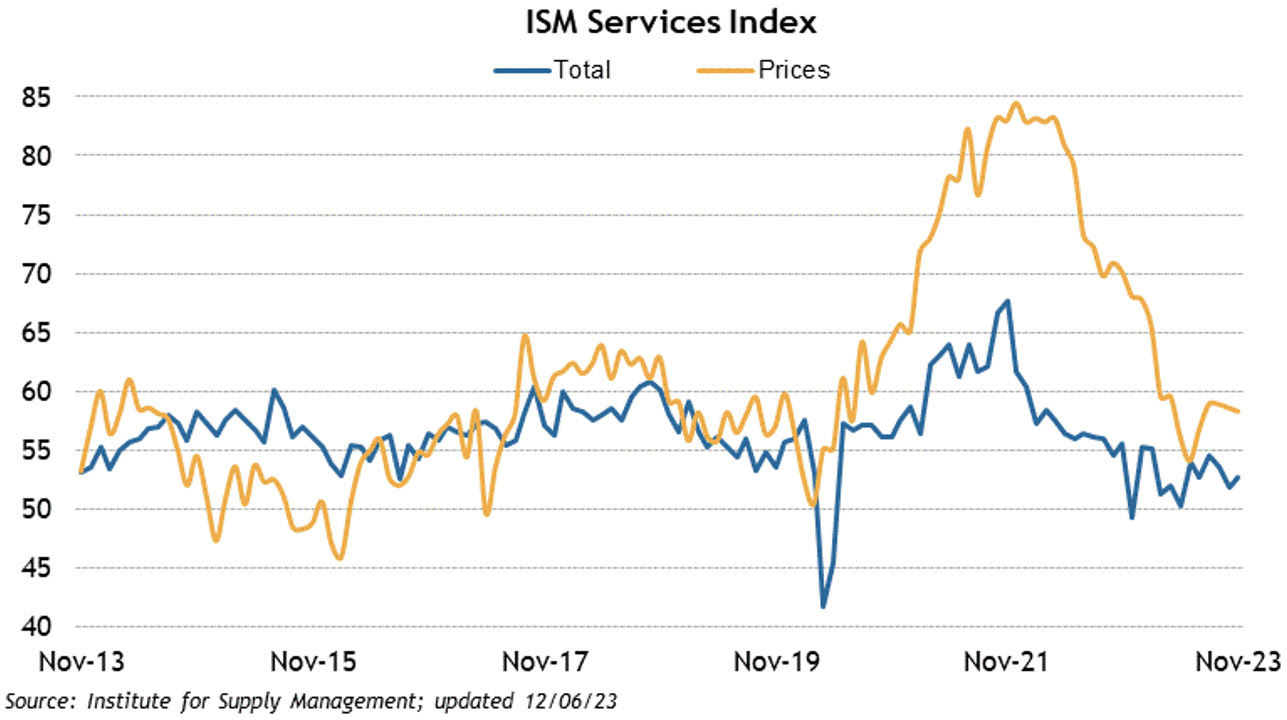
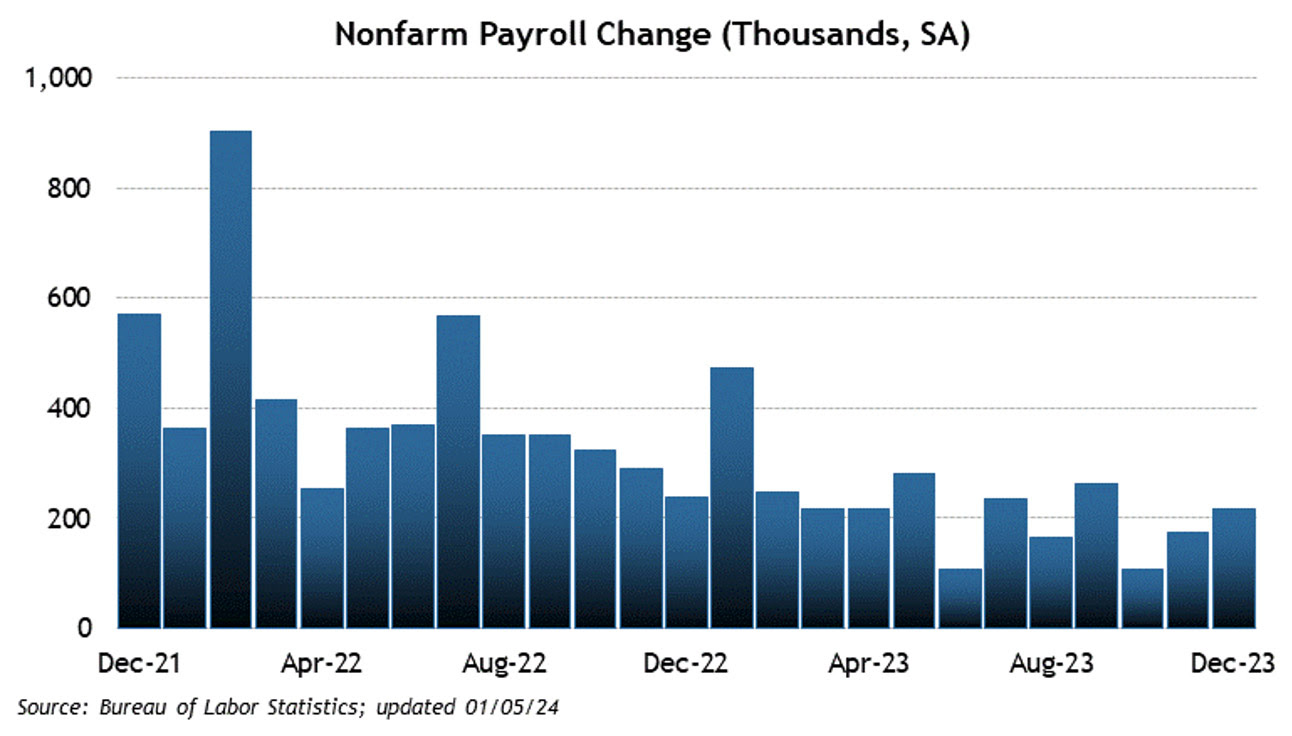
The economic calendar was packed in the first week of 2024 and highlighted by a stronger than anticipated Employment Situation report. Non-farm payrolls increased by 216k more than the consensus estimate of 175k. Similarly, Private Payrolls increased by 164k vs. the forecast of 132k. The Unemployment rate remained at 3.7%, less than the expected 3.8%. Average hourly earnings increased by 0.4% and were up 4.1% year-over-year from 4% in November. The Average work week came in at 34.3 vs. the estimate of 34.4. Jolts data showed fewer job openings in December, at 8.79m, down from 8.852m in November. Initial Jobless Claims and Continuing Claims reinforced the resiliency of the labor market. Initial claims fell to 202k, and Continuing Claims fell by 20k to 1855k. ISM Manufacturing remained in contraction at 47.4 but was better than the prior reading of 46.7. ISM Services showed the service sector slowing. Services fell to 50.6, down from November’s 52.7.
Investment advisory services offered through Foundations Investment Advisors, LLC (“FIA”), an SEC registered investment adviser. FIA’s Darren Leavitt authors this commentary which may include information and statistical data obtained from and/or prepared by third party sources that FIA deems reliable but in no way does FIA guarantee the accuracy or completeness. All such third party information and statistical data contained herein is subject to change without notice. Nothing herein constitutes legal, tax or investment advice or any recommendation that any security, portfolio of securities, or investment strategy is suitable for any specific person. Personal investment advice can only be rendered after the engagement of FIA for services, execution of required documentation, including receipt of required disclosures. All investments involve risk and past performance is no guarantee of future results. For registration information on FIA, please go to https://adviserinfo.sec.gov/ and search by our firm name or by our CRD #175083. Advisory services are only offered to clients or prospective clients where FIA and its representatives are properly licensed or exempted.



