

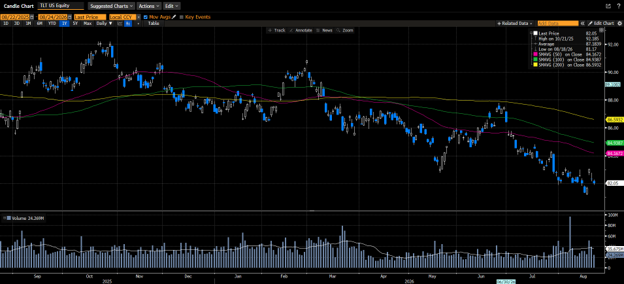
US equity markets took a step back last week in what turned out to be a very busy week. Increased yields on the long end of the curve prompted Treasury Secretary Scott Bessent to double buybacks of 10- to 30-year US Treasuries in an effort to temper the rise in rates. The move was met with a rally in both bonds and stocks; however, it was short-lived, with much of the gains being given back within a day of the announcement. A global debasement narrative has emerged as the US deficit topped $40 trillion. The US Dollar sold off to levels not seen since May, while precious metals and Bitcoin prices soared. Interestingly, the correlation between Gold and Bitcoin is the highest since Covid, following massive liquidity injections by global governments. It’s notable that several other developed markets are facing similar pressure on their sovereign debt, including Japan, the UK, France, and Germany. A crowding-out effect, or competition for funding, has also been prevalent as corporations have tapped the debt market to finance massive AI capital expenditures. Bessent will outline additional measures the Treasury can take to address liquidity on the long end of the curve this week. The buybacks will not fix the problem in the long run; they are a band-aid and will likely have unintended consequences if there is no material change on the fiscal side of the blotter. Bessent is also expected to lay out new economic sanctions on Iran. President Trump appears comfortable with continuing the blockade on Iranian shipments, which has had a devastating impact on Iran’s economy but has not yet been enough to force Iran to agree to US terms to end the war. Brent crude topped $90 per barrel again this week and continues to elevate inflation expectations. Q2 earnings featured several retailers, including Walmart, Target, Home Depot, and Lowes. The results, for the most part, were solid, but commentary about passing increased costs on to consumers, along with tepid guidance from Walmart, kept post-earnings price action muted. In corporate news, Moderna announced progress on a melanoma cancer vaccine. The news sent shares higher by more than 100% and prompted a buying spree across the drug development sector.

The S&P 500 lost 1.39%, the Dow fell 0.78%, the Nasdaq fell by 2.02%, and the Russell 2000 gave back 1.61%. The yield curve flattened with shorter-dated maturities selling off more than longer-dated issues. The 2-year yield increased by six basis points to 4.23%, while the 10-year yield increased by four basis points to 4.74%. West Texas Intermediate Crude prices increased by 5.6% or $4.67 to $87.07 a barrel. Gold prices surged 5.4% to $4,680.10 per ounce. Silver prices increased by 6.69% to $69.47 per ounce. Copper prices rose by two cents to $6.59 per Lb. Bitcoin’s price increased the most in a week in three years, gaining $13,800 or 21.9% to close the week at $76,800. The US Dollar index declined by 0.8% to 98.81.

The economic calendar featured weaker-than-expected housing market data. Housing Starts came in at 1239k, below the estimated 1360k. Building Permits came in at 1443k versus the consensus estimate of 1390k. Pending Home Sales declined by 2.3%, below the estimate of an increase of 1.3%. A preliminary look at S&P Global’s Manufacturing and Services PMIs indicated economic expansion. The Manufacturing PMI came in at 53.2 versus the previous reading of 53.9, while the Services PMI increased to 56.8 from 54.6 in the prior month. Initial Jobless Claims increased by 6k to 206K, while Continuing Claims jumped by 18k to 1799k. Industrial Production increased by 0.2% in line with estimates, as Capacity Utilization climbed to 76.3. In the coming week, we will get a look at Consumer Confidence and Consumer Sentiment. We will also look at the Fed’s preferred inflation measure, the PCE, and the 2nd estimate of Q2 GDP.

Investment advisory services offered through Foundations Investment Advisors, LLC (“FIA”), an SEC registered investment adviser. FIA’s Darren Leavitt authors this commentary which may include information and statistical data obtained from and/or prepared by third party sources that FIA deems reliable but in no way does FIA guarantee the accuracy or completeness. All such third party information and statistical data contained herein is subject to change without notice. Nothing herein constitutes legal, tax or investment advice or any recommendation that any security, portfolio of securities, or investment strategy is suitable for any specific person. Personal investment advice can only be rendered after the engagement of FIA for services, execution of required documentation, including receipt of required disclosures. All investments involve risk and past performance is no guarantee of future results. For registration information on FIA, please go to https://adviserinfo.sec.gov/ and search by our firm name or by our CRD #175083. Advisory services are only offered to clients or prospective clients where FIA and its representatives are properly licensed or exempted.



