

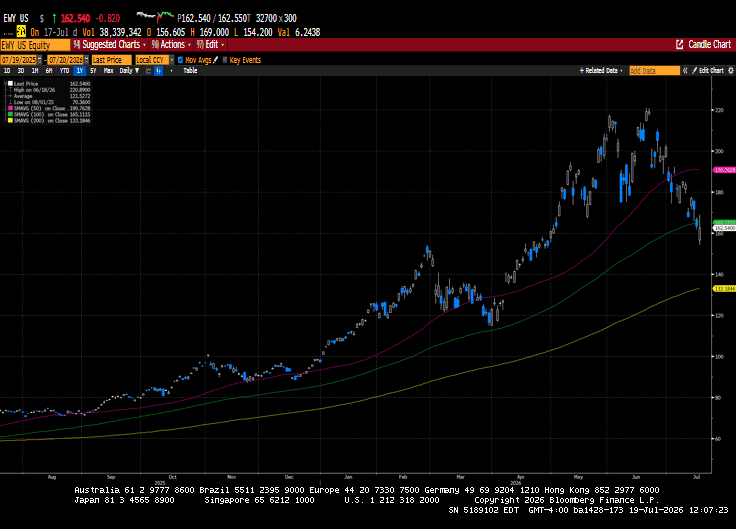
Markets took a step back last week despite a better-than-expected start to second-quarter earnings and benign inflation data. Semiconductor names continued to come under pressure, especially the memory names, as the sector entered into bear territory, off 20% in just over a month. South Korea’s market led declines amid weakness in semiconductor stocks, as leverage came off the table following the government’s ban on additional single-stock leveraged ETFs. Mega Cap Tech underperformed, while energy stocks were bid higher amid escalating tensions between the US and Iran. These tensions are likely to increase in the coming week as two US soldiers were killed and several injured in an Iranian attack on Jordan. The rotation away from sectors that have been leading the market, along with a muted response to this week’s better-than-expected bank and technology earnings and to the cooler inflation data, suggests this market could roll over further in the coming weeks. Another worry for me is that the highly touted SpaceX IPO has broken down below the issue price of $135, wiping out nearly $1 trillion in valuation since its peak.

The S&P 500 lost 1.8%, the Dow fell 1%, the NASDAQ gave back 3.3%, and the Russell 2000 slumped by 0.6%. The US yield curve enjoyed symmetric gains across tenors as the weaker-than-expected inflation data diminished rate hike probabilities. The 2-year yield fell by four basis points to 4.17%, while the 10-year yield declined by 3 basis points to 4.54%. Oil prices surged by 14.36% or $10.26 to $81.67 a barrel. Gold prices fell by 2.3% to $4018.70 per ounce. Silver prices declined by 6.56% to $56.22 per ounce. Copper’s price fell by one penny to $6.27 per Lb. Bitcoin’s price was unchanged on the week, closing at $64,000. The VIX (volatility index) increased by 20% on the week, closing at 18.77. The US Dollar index fell by 0.2% to 100.76.

The economic calendar was showcased by weaker-than-expected inflation data. Headline CPI came in down 0.4% on a month-over-month basis and fell to 3.5% from 3.8% year over year. The Core CPI was flat over the prior month but declined to 2.6% year over year, down from 2.8%. Headline PPI fell by 0.3% versus the estimate of 0.2% and fell to 5.5% from 6.5% year over year. Core PPI was up 0.2% over the prior month but fell to 4.7% from 4.9% year over year. Retail Sales were better after you stripped out the effects of falling gasoline prices and continued to show a resilient consumer. Retail sales increased by 0.2% while the Ex-auto figure also came in at up 0.2%. Housing Starts were better at 1427k, while Building Permits came in a tad light at 1367K. Initial Jobless Claims fell by 8k to 208K, while Continuing Claims dropped by 16k to 1821k. The first look at July’s University of Michigan Consumer Sentiment came in better than the previous reading at 54.4.

Investment advisory services offered through Foundations Investment Advisors, LLC (“FIA”), an SEC registered investment adviser. FIA’s Darren Leavitt authors this commentary which may include information and statistical data obtained from and/or prepared by third party sources that FIA deems reliable but in no way does FIA guarantee the accuracy or completeness. All such third party information and statistical data contained herein is subject to change without notice. Nothing herein constitutes legal, tax or investment advice or any recommendation that any security, portfolio of securities, or investment strategy is suitable for any specific person. Personal investment advice can only be rendered after the engagement of FIA for services, execution of required documentation, including receipt of required disclosures. All investments involve risk and past performance is no guarantee of future results. For registration information on FIA, please go to https://adviserinfo.sec.gov/ and search by our firm name or by our CRD #175083. Advisory services are only offered to clients or prospective clients where FIA and its representatives are properly licensed or exempted.



