

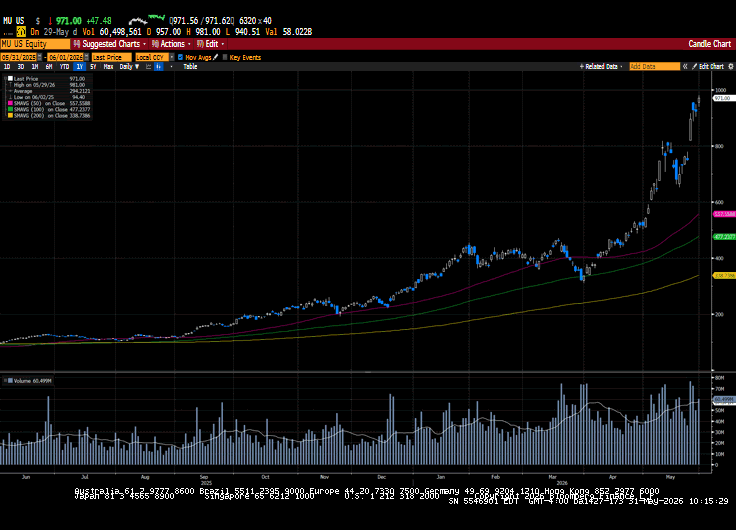
Global equity markets rallied in May and received a final boost in the final week of the month on optimism that the US and Iran were close to extending the current ceasefire agreement. However, the negotiations between the two parties were described as “clear as mud” in a recent article I read, and the analogy couldn’t be truer. Despite the day-to-day back-and-forth in the negotiations, markets were able to look past the fact that the Strait of Hormuz has been closed for three months, elevating energy costs around the world and increasing global inflation. Several inflation data points over the month were higher than expected, which in turn sent US yields higher and the prospect of a rate cut by the Federal Reserve lower. Q1 earnings continued to come in much better than expected, and commentary from several companies remained constructive, especially on the artificial intelligence front. Earnings per Share growth of nearly 30% was the catalyst that drove markets higher despite the current geopolitical landscape and a heightened inflationary environment. In the last week, Dell and Snowflake announced fantastic first-quarter results. Capital spending on AI pushed the market caps of Micron Technology, Samsung, and SK Hynix above $ 1 trillion. The rebound from the March lows was fast and steep, sending the S&P 500, Dow, and NASDAQ to several new highs in May. In the coming month, investors will await arguably the most anticipated IPO, SpaceX. The company is set to go public at a $2 trillion valuation, and the hype has sent shares of other space economy companies materially higher over the last few months. There is a ton of optimism in the market right now, and while it does appear the market may be over its skis a bit, we remain constructive on the idea of continued solid corporate earnings, positive inertia from the AI infrastructure build out, and on hopes that the US and Iran can end the conflict and open the Strait, which in time will lower global energy prices.

The S&P 500 gained 4.95% in May, added 1.44% this week, and is up 11.25% year to date. The Dow increased by 0.9% this week, gained 3.25% in May, and is up 6.86% for the year. NASDAQ added 2.44% this week, was up 7.47% in May, and has advanced 16.34% for the year. The Russell 2000 gained 1.7% for the week, was up 3.89% for May, and has increased by 18.27% this year.
The US Treasury curve flattened over the month of May as shorter tenured paper sold off more than the longer end of the curve. The 2-year yield fell eleven basis points this week to 4.01%, but its yield increased by twenty-four basis points in May. The 10-year yield also fell by eleven basis points this week to 4.45% and was up six basis points over the month of May. A recalibration of monetary policy was evident in May, as inflation remained elevated due to higher energy costs and evidence that these costs have begun to raise prices for other goods and services. Kevin Warsh was sworn in as the new Fed Chairman, where he will face a growing number of Fed officials who have voiced the need for higher rates for longer.
West Texas Intermediate Crude trade over the last month was volatile to say the least. Oil prices fell 9% last week and fell 16.8% for the month of May. WTI closed the month at $87.42 a barrel. Gold prices increased by 1.4% for the week and fell by $38.20 for the month, closing at $4,592.70 per ounce. Silver prices were unchanged for the week and gained 3.1% for the month, closing at $75.88 per ounce. Copper prices increased by a penny this week, adding $0.41, or 6.8%, for the month to close at $6.39 per pound. Bitcoin’s price ended the week at $73,800, down 2.12% for the week and off 3.09% for the month. The US Dollar index was up 0.8% for the month. Of note, the Japanese Yen closed the month at 159.22, just below the 160 level that induced the Bank of Japan to intervene. What is troubling is that, despite interventions throughout the month totaling nearly $73 billion, the Yen has crept back to this important level.

This week’s economic calendar was highlighted by the Fed’s preferred measure of inflation, the PCE. The reading showed better-than-expected results for both the headline and core on a month-over-month basis, but showed increased levels of inflation on a year-over-year basis. The headline reading showed an increase of 0.4% versus the consensus of 0.5%, while it increased by 3.8% from 3.5% in April. The Core reading, which strips out food and energy prices, increased by 0.2% in May versus the estimated increase of 0.3%. The year-over-year figure came in at 3.3%, up from 3.2% in April. Personal income in May was flat, while Personal Spending increased by 0.5%. Consumer Confidence fell to 93.1 from 93.8. The 2nd look at the 1st quarter GDP, fell to 1.6% from 2.2%. Initial Claims increased by 5k to 215k, while Continuing Claims increased by 15k to 1786k.

Investment advisory services offered through Foundations Investment Advisors, LLC (“FIA”), an SEC registered investment adviser. FIA’s Darren Leavitt authors this commentary which may include information and statistical data obtained from and/or prepared by third party sources that FIA deems reliable but in no way does FIA guarantee the accuracy or completeness. All such third party information and statistical data contained herein is subject to change without notice. Nothing herein constitutes legal, tax or investment advice or any recommendation that any security, portfolio of securities, or investment strategy is suitable for any specific person. Personal investment advice can only be rendered after the engagement of FIA for services, execution of required documentation, including receipt of required disclosures. All investments involve risk and past performance is no guarantee of future results. For registration information on FIA, please go to https://adviserinfo.sec.gov/ and search by our firm name or by our CRD #175083. Advisory services are only offered to clients or prospective clients where FIA and its representatives are properly licensed or exempted.



