

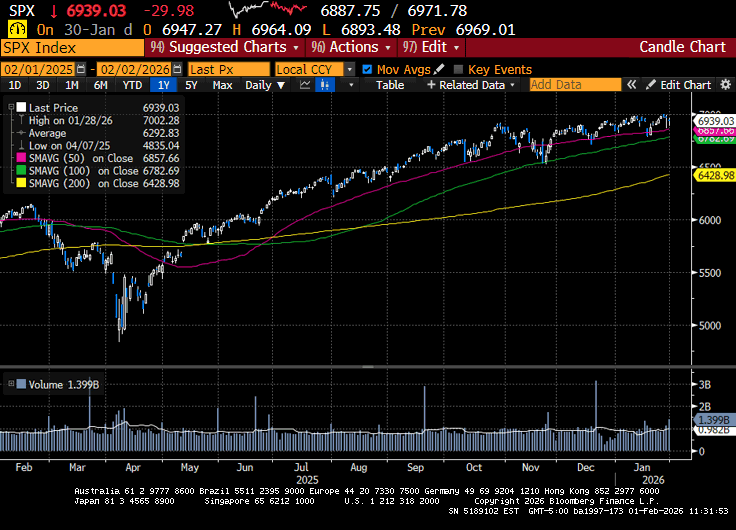
Markets ended the week mixed. With just over a third of the S&P 500 having reported fourth-quarter earnings, this earnings season appears much better than anticipated. That said, despite better-than-expected results, many companies have sold off after the announcement. Microsoft is a perfect example, posting a solid quarter; investors sold the name on concerns that its capex spending did not drive more robust cloud sales growth. ASML also posted stellar results but faced selling pressure after the earnings announcement. So, despite the solid earnings, some of these results appear to already be reflected in the stock price. Meta announced solid results and doubled its AI capex for 2026. The company also announced a six-billion-dollar deal with Corning for fiber and cable connection solutions. Texas Instruments, UPS, GE Vernova, Raytheon, IBM, and Lam Research all posted impressive results and traded higher after their announcements. With nearly a third of the S&P having reported, earnings per share growth has come in at 11.9%, well above the anticipated 8.3% growth coming into the quarter. The top-line results have grown by 8.2%, which is above the 7.8% anticipated. 127 S&P 500 companies are scheduled to report in the coming week.
The Federal Open Market Committee meeting yielded very little for investors to act on. The Fed kept its policy rate unchanged at 3.5% to 3.75%. The decision was made with a 10-2 vote, with Miran and Waller dissenting. Fed Chairman Jerome Powell navigated the Q&A without providing any additional catalysts. The Fed will remain data-dependent, and, in all likelihood, there will be no further rate cuts during the remainder of Powell’s chairmanship. President Trump announced that Kevin Warsh would be his nominee for Fed Chairman. Warsh should bring institutional credibility to the position, having served as a governor from 2006 to 2011, appointed by President Bush. Warsh holds a PHD in economics and statistics from Stanford and has a law degree from Harvard. He has been critical of the current Fed and of Powell for the late response to inflation induced by the COVID stimulus. He is known as a hawk and will likely seek to reduce the Fed’s balance sheet. It is also likely that he will try to be less data-dependent and more strategic in framing Fed policy.

The S&P gained 0.3%, the Dow lost 0.4%, the NASDAQ fell 0.2%, and the Russell 2000 gave back 2.1%. The Russell 200 led indices in January, gaining 5.3%, while the S&P returned 1.4% for the month. Treasury yields fell across most of the curve but increased on the long end. The 2-year yield fell by seven basis points to 3.53%, while the 10-year yield was unchanged at 4.24%. Yields increased across the curve in January. Currently, the market is pricing in a 25-basis-point rate cut in July. There was significant volatility in commodity markets. Gold prices fell 15% in Friday’s session, while silver prices plunged 38%. The decline in gold prices on Friday was the largest single-day slide in four decades. For the week, gold lost 4.2%, and silver prices fell by 22%. Oil prices rose $7.57, or 13.1%, amid rising tensions between the US and Iran. Bitcoin’s price fell by nearly 13% over the week to $77,200. The US Dollar index ended the week little changed after coming under significant pressure early in the week and falling to a 4-year low on speculation that the US Treasury would intervene to strengthen the Japanese Yen. The US Dollar index fell by 1.3% in January.

Gold 1/30/2026
The economic calendar showed weakening consumer confidence and a surprise uptick in producer prices. Consumer Confidence in January fell to 84.5 from the prior reading of 94.2, the lowest level since 2014. Concerns about the economy and the labor market drove the decline. The Producer Price Index (PPI) increased by 0.5%, above the consensus estimate of 0.2%, and rose 3% year over year, unchanged from the November reading. The Core PPI, which excludes food and energy, increased by 0.6%, above the anticipated 0.3% increase. On a year-over-year basis, the Core figure rose by 3.2% in December, up from 3% in November. Initial Jobless Claims fell by 1k to 209K, while Continuing Claims decreased by 38k to 1827k. Q3 Productivity remained steady at 4.9%, while Q3 Unit Labor Costs declined by 1.9%. In the coming week, we will receive data on the ISM Manufacturing and Services and the BLS Employment Situation report for January.

Investment advisory services offered through Foundations Investment Advisors, LLC (“FIA”), an SEC registered investment adviser. FIA’s Darren Leavitt authors this commentary which may include information and statistical data obtained from and/or prepared by third party sources that FIA deems reliable but in no way does FIA guarantee the accuracy or completeness. All such third party information and statistical data contained herein is subject to change without notice. Nothing herein constitutes legal, tax or investment advice or any recommendation that any security, portfolio of securities, or investment strategy is suitable for any specific person. Personal investment advice can only be rendered after the engagement of FIA for services, execution of required documentation, including receipt of required disclosures. All investments involve risk and past performance is no guarantee of future results. For registration information on FIA, please go to https://adviserinfo.sec.gov/ and search by our firm name or by our CRD #175083. Advisory services are only offered to clients or prospective clients where FIA and its representatives are properly licensed or exempted.



