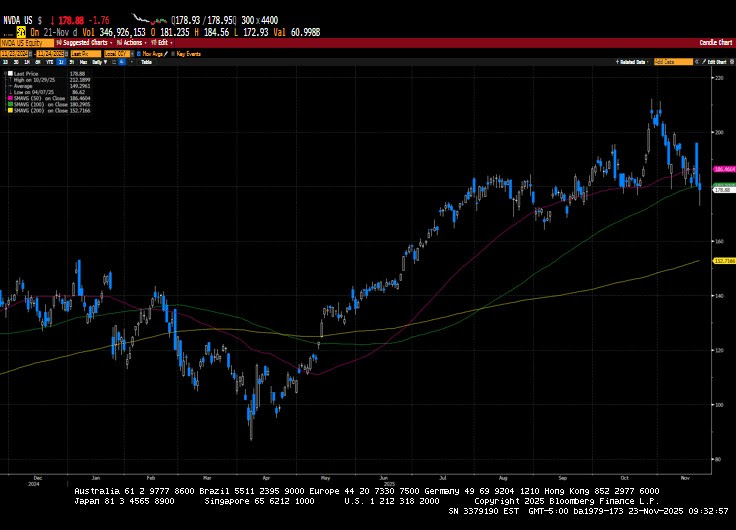
The holiday-shortened week saw global financial markets trade higher. Increased optimism for a December rate cut, along with some constructive news on the AI front, catalyzed buying across risk assets. Several Fed officials indicated they were inclined to support a December rate cut, which pushed the probability of a cut to over 80%. Of note, Kevin Hassett, the National Economic Council Director, has apparently become the frontrunner for President Trump’s choice for Fed Chairman. The Philadelphia Semiconductor index gained 9.7% on the week, even as Nvidia struggled after the news that Meta is considering Google’s rival chip as an alternative to Nvidia’s GPU solutions. Intel soared by more than 10% on news that Apple may source Intel chips. Dell posted solid earnings, boosting the artificial intelligence trade.

The S&P 500 regained its 50-day moving average, gaining 3.7% for the week, 0.13% for the month of November, and is up 17.79% year to date. The Dow added 3.2%, the NASDAQ increased by 4.9% but still ended the month with a 1.5% loss, and the Russell 2000 jumped 5.5% on the week. The Healthcare sector led the market in November, rising by 9.1% over the month. US Treasuries end the week higher across the curve despite weak auctions of 2-year, 5-year, and 7-year notes. The 2-year yield fell by two basis points to 3.49%, while the 10-year yield fell by four basis points to 4.02%. Oil prices advanced by $1.38 or 2.4% despite what appeared to be constructive negotiations to end the war between Russia and Ukraine. West Texas Intermediate crude closed at $59.44 a barrel. Gold prices moved sharply higher, gaining 4.3% on the week, closing at $4255.70 per ounce. Silver prices went to new all-time highs, increasing by 13% on the week and closing at $56.45 per ounce. Copper prices also had a nice week, gaining 4.98% to close at $5.27 per Lb. Bitcoin prices bounced off the recent sell-off, advancing 8.3% to $90,850. The US Dollar index fell by 0.7% to close at 99.47.

The economic calendar was a little lighter than expected, with September PCE, Personal Spending, Personal Income, and the 2nd look at 3rd-quarter GDP growth delayed further. The September reading of the Producer Price Index came in line with estimates at 0.3%, while the Core figure came in at 0.1% versus the estimated 0.3%. Retail Sales for September were a bit light on the headline figure, which came in at 0.2% versus the expectation of a 0.3% gain. The Ex-Autos figure increased by 0.3% versus the consensus estimate of 0.1%. It did appear that the consumer held back on buying goods in September. However, this data is quite old, and readings of Black Friday spending activity suggest that the consumer is still out spending and very resultant. Consumer Confidence came in well below the prior figure at 88.7. The expectations index fell as sentiment about business conditions, the labor market, and household income fell. ADP private payroll data showed a 4-week average drop of 13,500 payrolls. However, Initial Claims fell by 6k to 216k, as Continuing Claims increased by 7k to 1960k.

Investment advisory services offered through Foundations Investment Advisors, LLC (“FIA”), an SEC registered investment adviser. FIA’s Darren Leavitt authors this commentary which may include information and statistical data obtained from and/or prepared by third party sources that FIA deems reliable but in no way does FIA guarantee the accuracy or completeness. All such third party information and statistical data contained herein is subject to change without notice. Nothing herein constitutes legal, tax or investment advice or any recommendation that any security, portfolio of securities, or investment strategy is suitable for any specific person. Personal investment advice can only be rendered after the engagement of FIA for services, execution of required documentation, including receipt of required disclosures. All investments involve risk and past performance is no guarantee of future results. For registration information on FIA, please go to https://adviserinfo.sec.gov/ and search by our firm name or by our CRD #175083. Advisory services are only offered to clients or prospective clients where FIA and its representatives are properly licensed or exempted.