

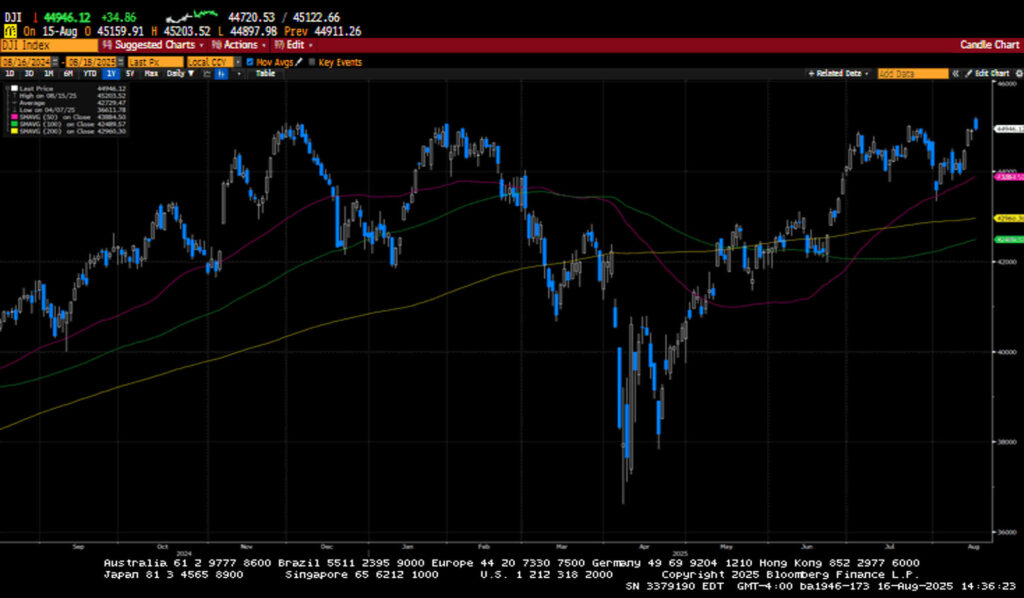
Global financial markets had another positive week as the Dow Jones Industrial Average finally joined the S&P 500 and the NASDAQ with a new all-time high. Benign consumer inflation increased the probability of a September rate cut to 99% and fostered the idea of a chance for a 50 basis point cut. However, elevated inflation from the Producer Price Index tempered rate cut expectations to 85% and pushed back on the idea of a larger cut at the next Federal Reserve meeting. Several Fed officials highlighted elevated inflation and noted that inflation is likely to move higher in the short term, but also acknowledged what appears to be weakening labor market. Fed Chairman J. Powell will speak at the Kansas City Fed’s Jackson Hole Economic Symposium next week, where investors will be listening for either hawkish or dovish overtones from the Chairman. Notably, Treasury Secretary Bessent suggested the Fed could cut by 50 basis points at the September meeting and also provided an opinion that the neutral rate is 1.50%lower than the current policy rate of 4.25%- 4.50%.

Mega-cap issues took a breather while cyclicals, mid-cap, and small-cap issues outperformed. Small-caps in particular had a very strong performance on the back of lower rate expectations. Q2 earnings reports have, for the most part, beaten expectations with double-digit earnings growth and revenue growth above 6%. Corporate highlights this week included Nvidia’s and AMD’s decision to pay 15% of their revenues from Chinese chip sales to the US government, reports that the US government is considering a stake in Intel, a bid of 34.5 billion from Perplexity for Google’s Chrome offering and another bid from Open AI, a very strong IPO for Crypto exchange company Bullish, and reports that Warren Buffet and Hedge manager David Tepper had taken stakes in beaten down UnitedHealthcare.
News from the Oval Office was relatively muted this week, but the President did extend negotiations on trade with China for an additional90 days and met with Vladimir Putin in Alaska to discuss a path to end the Russian/Ukraine war. Reports suggest that a deal was not made and that Ukraine’s President Zelensky would travel to Washington on Monday to meet with President Trump. Putin is reportedly asking for full control of the Donetsk and Luhansk regions, and as I am writing this note, it appears that Trump is backing the plan to cede land to end the war.

The S&P 500 gained 0.8% and is up nearly 30% from the April lows. The Dow added 1.7% and, as I mentioned, hit all-time highs this week. The NASDAQ rose by 0.8% and the Russell led with an advance of3.1%. US Treasuries ended the week with shorter tenured paper outperforming longer duration paper. The 2-year yield finished the week unchanged at 3.76%, while the 10-year yield increased by four basis points to 4.33%. Oil prices continued their decline, losing1.8% or $1.15 to close at $62.73 a barrel. Gold prices slumped after Trump announced that there would not be a levy on gold bars. Gold prices fell by$108.70 to close the week at $3383.50 per ounce. Copper price rose by two cents to close at$4.49 per Lb. Bitcoin’s price fell by$847 to $117,837. The US Dollar index fell by 0.34 to 97.84.
The economic calendar was highlighted by inflation data from the Consumer Price Index and the Producer Price Index. The CPI came in as expected on the headline and core readings. Headline CPI increased by 0.2% over the prior month and increased by 2.7% annually, which was in line with June’s reading. The Core, which excludes food and energy, increased by 0.3% over the prior month and by 3.1% on a year-over-year basis, which was above the increase of 2.9% in June. Notably, the Services Index increased by 3.8% year-over-year, and used car and truck prices increased by0.5%. The in-line report sent markets higher on the idea that the Federal Reserve could cut rates at its September meeting. However, a hotter-than-expected PPI pushed back the probability of a cut lower, but it still sits at an 85% likelihood.

The hotter print pushed back on the idea of a 50-basis-pointcut. Headline PPI came in at 0.9% versus an expected 0.2% and increased by 3.3%on an annual basis, versus an annual increase in June of 2.4%. The Core reading of PPI also increased by0.9% versus the consensus estimate of 0.2% and increased 3.7% year-over-year versus 2.6% in June. The services component increased by 1.1% the largest increase since March of 2022. Inflation at the producer level could start to eat into corporate margins, and this reading may suggest that tariff effects are beginning to flow through the supply chain and may eventually be passed onto the consumer, possibly increasing future CPI prints. Retail sales for July came in line at 0.5%with the Ex-Autos reading beating the consensus at 0.3%. Additionally, the prior months’ Retail Sales figures were increased. The numbers were decent and suggest the consumer is still out spending. We will get several consumer products companies reporting earnings in the coming week, which will also provide us with evidence on how the consumer is holding up. Finally, a preliminary August reading of the University of Michigan’s Consumer Sentiment Index declined for the first time in 4 months to 58.6 from July’s 61.7. Inflation expectations ramped up in the survey, and unemployment concerns were also elevated.
Investment advisory services offered through Foundations Investment Advisors, LLC (“FIA”), an SEC registered investment adviser. FIA’s Darren Leavitt authors this commentary which may include information and statistical data obtained from and/or prepared by third party sources that FIA deems reliable but in no way does FIA guarantee the accuracy or completeness. All such third party information and statistical data contained herein is subject to change without notice. Nothing herein constitutes legal, tax or investment advice or any recommendation that any security, portfolio of securities, or investment strategy is suitable for any specific person. Personal investment advice can only be rendered after the engagement of FIA for services, execution of required documentation, including receipt of required disclosures. All investments involve risk and past performance is no guarantee of future results. For registration information on FIA, please go to https://adviserinfo.sec.gov/ and search by our firm name or by our CRD #175083. Advisory services are only offered to clients or prospective clients where FIA and its representatives are properly licensed or exempted.



