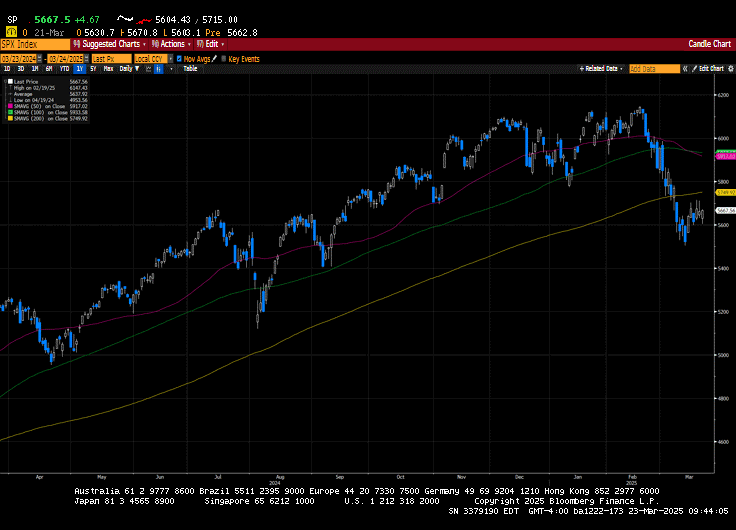
The S&P 500 avoided a fifth straight week of losses as investors continued to assess the impact of Trump’s policies. A late rally on Friday afternoon, fueled on heavy volume from quarterly options’ expiration, helped propel the S&P 500 higher and avoid another weekly loss. As expected, the Federal Reserve kept its monetary policy unchanged at 4.25%-4.50% but at the same time announced that it would reduce the amount of assets running off its balance sheet from $25 billion to $5 billion, a form of quantitative easing. Fed Chairman Powell endorsed the idea that tariffs could have a “transitory” effect on inflation and acknowledged that inflation continues to be elevated and that it was likely that economic growth would slow. However, the Chairman remained constructive on the US economy, which helped to send markets higher after his post-meeting Q&A. The Summary of Economic Projections showed that the committee had reduced its forecast on 2025 GDP growth to 1.7% from 2.1% and increased its Core PCE forecast to 2.8% from 2.5%. The Committee also forecasts the Fed Funds rate to be 3.9% by the end of 2025, translating to two twenty-five basis point cuts this year.
President Trump’s call with Russian President Putin appeared to yield a framework for a ceasefire centered on energy and infrastructure while opening the door to a maritime ceasefire in the Black Sea. Further technical negotiations are scheduled in the coming weeks, but the timeline remains vague.
NVidia’s GTC event showcased its newest chip and applications in AI and robotics, but the developers’ conference received a sell-the-news response on Wall Street. FedEx earnings results were disappointing, as were earnings from Nike, Lennar Homes, and Micron Technology.
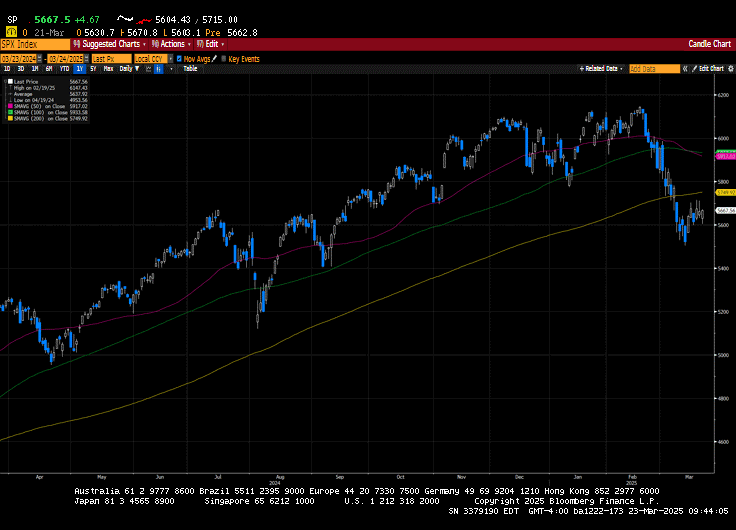
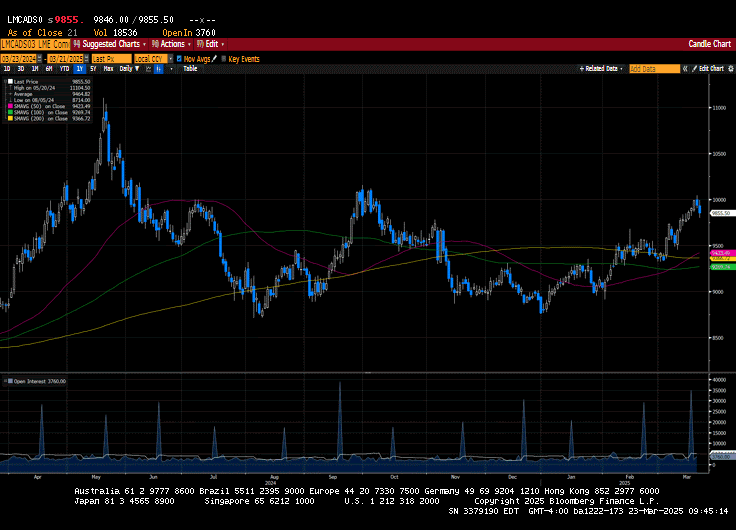
The S&P 500 gained 0.5%, the Dow rose by 1.2%, the NASDAQ added 0.2%, and the Russell 2000 increased by 0.6%. US Treasuries rallied across the curve but favored the front end and the belly. The 2-year yield fell by seven basis points to 3.95%, while the 10-year yield fell by six basis points to 4.25%. Oil prices increased by $1.07 or 1.6%, closing at $68.27 a barrel. Gold prices rose by $21.10 to close at $3,022.10 an Oz. Copper prices continued to trade higher, adding $0.21 to close at $5.11 per Lb. Bitcoin prices increased by ~$1,800, closing at $84,390 on Friday. The US Dollar index added 0.3% to 104.6.
Economic data for the week was mixed. Retail sales increased by 0.2%, less than the estimated increase of 0.7%. The Ex-auto print was up 0.3% versus the consensus estimate of 0.4%. The control group figure came in up 1%, which was materially better than the 1% decline in January and gave investors solace that the consumer is still spending, albeit at a more measured pace. Housing data for the week was better than expected, with Housing Starts and Permits coming in above estimates. Existing Home sales also topped estimates at 4.26M versus 3.95M. Industrial production came in at 0.7%, above the estimated 0.2%, while capacity utilization rose to 78.2% compared to the estimated 77.7%. Initial Claims increased by 2k to 223K, while Continuing Claims jumped by 33k to 1.892M.
Investment advisory services offered through Foundations Investment Advisors, LLC (“FIA”), an SEC registered investment adviser. FIA’s Darren Leavitt authors this commentary which may include information and statistical data obtained from and/or prepared by third party sources that FIA deems reliable but in no way does FIA guarantee the accuracy or completeness. All such third party information and statistical data contained herein is subject to change without notice. Nothing herein constitutes legal, tax or investment advice or any recommendation that any security, portfolio of securities, or investment strategy is suitable for any specific person. Personal investment advice can only be rendered after the engagement of FIA for services, execution of required documentation, including receipt of required disclosures. All investments involve risk and past performance is no guarantee of future results. For registration information on FIA, please go to https://adviserinfo.sec.gov/ and search by our firm name or by our CRD #175083. Advisory services are only offered to clients or prospective clients where FIA and its representatives are properly licensed or exempted.