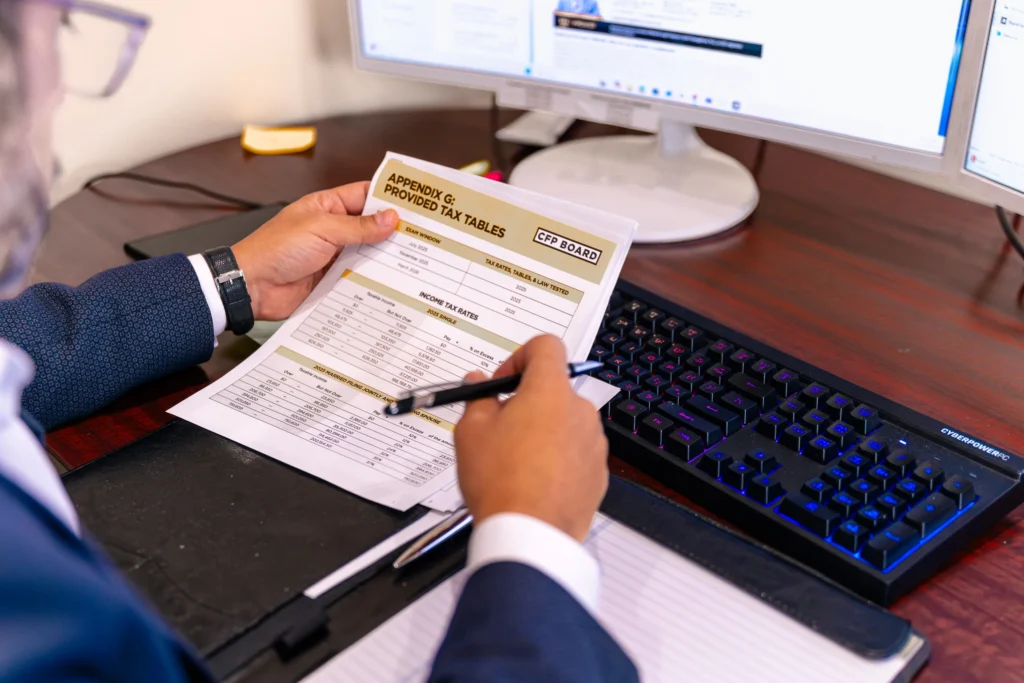
As April 15 approaches, many people assume the window for tax planning has already closed. The truth is, there may still be time to make a few smart financial moves that could help reduce taxable income, strengthen retirement savings, and improve long-term financial security. For most taxpayers, April 15, 2026 is the deadline to file a 2025 federal tax return, and it is also generally the deadline to make 2025 IRA contributions and 2025 HSA contributions.
Whether you are still preparing your return or simply doing a final review, here are a few last-minute areas worth checking before tax day.
1. Review Whether You Can Still Contribute to an IRA
One of the most common last-minute tax strategies is making a contribution to an Individual Retirement Account, or IRA. For many people, this can be a valuable way to continue building retirement savings while also potentially creating a tax advantage for the prior year. The IRS states that, for most people, the deadline for making 2025 IRA contributions is Wednesday, April 15, 2026.
Depending on your situation, a traditional IRA contribution may be tax-deductible, while a Roth IRA may offer future tax-free withdrawals for qualified distributions. Even if the contribution does not reduce your current tax bill, adding to retirement savings before the deadline can still be a strong long-term move.
This is also a good time to ask:
- Have you already maxed out your retirement contributions for 2025?
- Would a traditional IRA or Roth IRA make more sense based on your income and tax bracket?
- Are you missing an opportunity to strengthen your retirement strategy before the deadline?
2. Don’t Overlook HSA Contributions
If you were eligible for a Health Savings Account in 2025, you may still be able to make a contribution before April 15 and count it for the prior tax year. IRS instructions for Form 8889 say that 2025 HSA contributions can generally be made through April 15, 2026.
An HSA is one of the more powerful planning tools available because it can offer multiple tax benefits: contributions may be tax-deductible, growth can be tax-deferred, and qualified medical withdrawals can be tax-free. For individuals and families who are eligible, this can be an important last-minute planning opportunity.
Before filing, it is worth checking:
- Were you HSA-eligible during 2025?
- Have you contributed the full amount allowed for your coverage type?
- Would an additional contribution help lower your taxable income?
3. Make Sure Your Retirement Plan Still Matches Your Goals
Tax season is not just about forms and deadlines. It is also a natural time to review whether your retirement plan is still aligned with your current life and financial goals.
Your income, expenses, family needs, and timeline may have changed over the last year. That makes April a smart checkpoint for reviewing:
- Current retirement account contributions
- Beneficiary designations
- Risk tolerance and investment mix
- Long-term income planning
- Whether you are saving enough for the lifestyle you want in retirement
A last-minute IRA or HSA contribution is helpful, but the bigger opportunity is making sure all of your financial pieces are working together.
4. Check for Missed Deductions and Planning Opportunities
Many people focus only on getting their return submitted, but a quick review before filing may help uncover missed opportunities. Depending on your circumstances, that may include retirement contributions, health savings contributions, or changes in income that could affect your planning choices.
This is especially important if you experienced major life changes in 2025, such as:
- Marriage or divorce
- A new job or job loss
- Retirement or partial retirement
- A home purchase or refinance
- Higher medical expenses
- A change in business income or self-employment income
Even when the tax impact is modest, the planning conversation can still be valuable because it often reveals larger opportunities for insurance, retirement, and estate planning.
5. Use Tax Season as a Financial Reset
For many families, tax season is one of the few times each year when they gather income documents, review accounts, and take a serious look at their finances. That makes this the perfect time to reset and prepare for the rest of the year.
A good review right now may help you:
- Improve cash flow
- Increase retirement contributions moving forward
- Revisit life insurance or income protection needs
- Organize accounts more efficiently
- Make better decisions before next year’s deadline arrives
The most important point is this: tax day should not only be about filing on time. It should also be a chance to make smarter decisions for the future.
Final Thoughts
If you have not yet finalized your 2025 return, there may still be time to make meaningful financial moves before April 15, 2026. For most taxpayers, that includes reviewing IRA contributions and HSA contributions, both of which may still count for 2025 if completed by the deadline.
A few thoughtful adjustments now could help you lower taxes, boost retirement savings, and build a stronger overall financial plan.
Need help reviewing your options before the deadline?
Now is a great time to take a closer look at your retirement strategy, tax planning opportunities, and overall financial protection plan.