Does your Medicare plan cover gym memberships and other fitness benefits?

There’s no age limit on exercise – physical activity is for everyone! In fact, as you get older, physical activity becomes an even more important part of your overall health. According to the Centers for Disease Control and Prevention, regular exercise can help prevent chronic conditions, boost heart and circulatory health, and increase muscle strength.

But how can you get the exercise you need? One way to explore being active and healthy is to check if your Medicare plan (including dual eligible Medicare and Medicaid plans) offers additional fitness benefits.

This means your plan may cover some or all of your gym membership or provide you with other resources to help maintain your physical health. It’s common for a health plan to partner with another company, like SilverSneakers®, to offer members support on their exercise journeys.

Gym memberships and other fitness benefits Medicare may cover

Traditionally, Original Medicare (Parts A and B) doesn’t cover gym memberships and other fitness benefits unless they are considered “medically necessary.” This means you’d need to pay entirely out of pocket if you want to join a gym or exercise program. However, private plans like Medicare Advantage (Part C) often provide additional coverage for fitness.

This can include things like gym benefits and at-home exercise resources, as well as other services like physical therapy, diabetes prevention, nutrition therapy and weight management counseling.

How a fitness benefit works

A Medicare plan fitness benefit is a great way to improve both your physical and mental health. It makes being more active simple and affordable because it’s typically covered at no extra cost.  This can include gym memberships, at-home workout resources, transportation to exercise facilities and more – however, it’s up to each plan what’s covered.

Low- or no-cost gym memberships

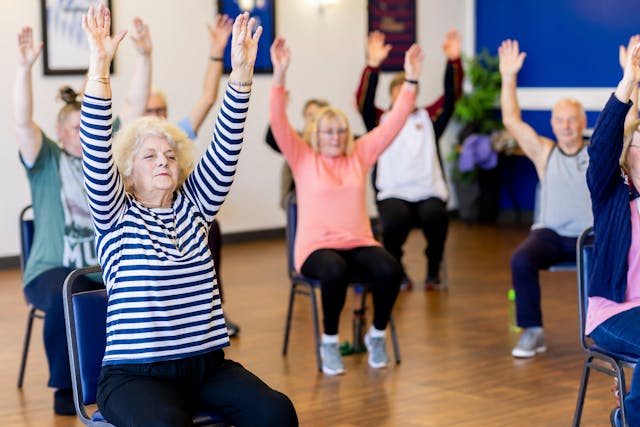
Your plan may provide you access to a fitness center or gym at no (or a reduced) cost to you. With no minimum visit requirements, you can use the facilities as often as you like. And specially trained instructors may teach classes adapted to the needs of older people.

At-home workout kits

Some plans provide kits so you can work out at home. These resources may include DVDs, apps to stream workouts to your smart device, guides and equipment to help you exercise on your own. Usually, you can choose one or two kits per year, depending on your Medicare plan benefit. And you’ll likely have a variety of fitness topics to choose from like strength training, walking, yoga, dance and more.

Your program may have added perks like a newsletter with healthy tips or a rewards program for tracking your activity. Some plans for people with low income, like a Minnesota Senior Health Options (MSHO) plan, also offer free transportation to fitness centers.

Getting started on a program

Generally, you can begin using the fitness benefit by showing your member ID card at the participating gym/fitness center or by downloading your plan’s fitness app. Here are some more ways to learn about your benefits and find the right center near you.

  1. Check your health plan materials, such as the Evidence of Coverage or the Member Handbook.
  2. Call your health plan’s Member Services at the phone number on the back of your member ID card. They’ll tell you if your plan has a fitness benefit and can help you find a participating fitness center nearby.
  3. Get help from the fitness program once you know which program your plan covers. You can go to the fitness program’s website or contact their customer service. Learn about your gym options and get helpful information to support the new fit you.

https://www.healthpartners.com/blog/does-medicare-cover-gym-memberships-fitness-programs/
Share:

View the Latest Posts:

Your Medicare Plan May Be Changing—Even If Your Health Hasn’t

You’re happy with your doctors. Your prescriptions haven’t changed. Your Medicare coverage worked well this year. So, is reviewing your plan really necessary? It’s a worthwhile step. Your healthcare needs may stay the same while your plan’s costs and coverage change. Taking time to review the details this fall can help you make a more informed decision about the year ahead. Medicare Open Enrollment runs October 15 through December 7 each year. Changes made during this period take effect January 1, as long as the plan receives your enrollment request by December 7. That means this fall’s enrollment decisions affect your coverage for 2027. Start With the Notice You Might Be Tempted to Skip If you have a Medicare Advantage or prescription drug plan, your plan sends an Annual Notice of Change, often called an ANOC, each fall. It explains changes to costs, coverage, and other plan details that begin

Medicare Open Enrollment 2027: 7 Things to Review Before December 7

Medicare Open Enrollment is one of the most important times of the year for people who already have Medicare. From October 15 through December 7, 2026, Medicare beneficiaries have an opportunity to review their current coverage and make changes for 2027. Any coverage changes made during this period generally take effect on January 1, 2027. Even if you are satisfied with your current plan, taking time to review your coverage can be worthwhile. Medicare Advantage and prescription drug plans can change from year to year—including premiums, provider networks, prescription drug coverage, copays, deductibles, and additional benefits. Here are seven areas worth reviewing before making your Medicare decisions for 2027. 1. Review Your Current Plan’s Changes for 2027 One of the biggest Medicare mistakes is assuming that because a plan worked well this year, it will automatically work the same way next year. Plans may change their: Monthly premiums Deductibles Copayments

Before Your Next Appointment: 5 Medicare Questions That Can Help Prevent Costly Surprises

You schedule an appointment, hand over your insurance card, and assume your coverage will take care of the rest. Then a bill arrives—or the pharmacy tells you that your new prescription needs approval. Understanding your Medicare coverage before you use it can help you prepare for expenses, address paperwork, and ask better questions. Whether you are new to Medicare or have had coverage for years, these five questions are worth keeping handy. 1. Can I Use This Doctor With My Coverage? “Do you take Medicare?” is a starting point, but the next question depends on how you receive your benefits. With Original Medicare, you can generally use doctors and hospitals that accept Medicare throughout the United States. Ask whether the provider accepts assignment, meaning they agree to accept the Medicare-approved amount as full payment for covered services. With Medicare Advantage, you may need to use your plan’s network for non-emergency

7 Medicare Enrollment Mistakes to Avoid When Turning 65

Turning 65 is an exciting milestone—but it also brings important Medicare decisions. With multiple enrollment periods, coverage options, and deadlines to understand, even a small mistake could lead to delayed coverage, unexpected expenses, or lifelong penalties. Here are seven common Medicare enrollment mistakes and how you may be able to avoid them. 1. Assuming Medicare Enrollment Is Always Automatic Some people are automatically enrolled in Medicare Parts A and B, while others must enroll themselves. If you are already receiving Social Security or Railroad Retirement Board benefits before turning 65, enrollment may happen automatically. If you are not receiving these benefits, you will generally need to sign up for Medicare. Do not assume your coverage will begin automatically. Confirm your enrollment status before your 65th birthday. 2. Missing Your Initial Enrollment Period Your Medicare Initial Enrollment Period is a seven-month window that generally includes: The three months before your 65th